Ambulatory Services Market
Ambulatory Services Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711016 | Published On : September 28, 2026 |
Format : 


 | Author : Erika Grotto
Ambulatory Services Market Size
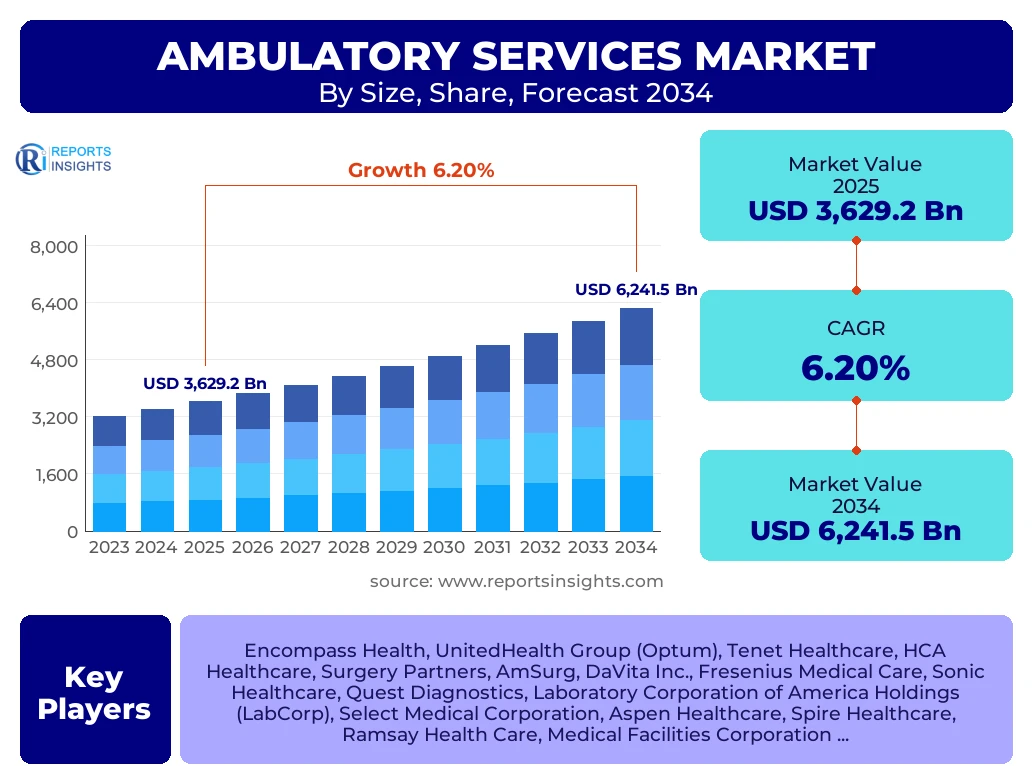
According to Reports Insights Consulting Pvt Ltd, The Ambulatory Services Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2026 and 2034. The market is estimated at USD 3,854.2 Billion in 2026 and is projected to reach USD 6,241.5 Billion by the end of the forecast period in 2034.
Key Ambulatory Services Market Trends & Insights
The global ambulatory services market is undergoing a significant paradigm shift as healthcare delivery migrates from traditional inpatient hospital settings to specialized outpatient environments. This transition is fueled by advancements in minimally invasive surgical techniques, the integration of digital health technologies, and a global emphasis on reducing healthcare expenditures. Stakeholders are increasingly prioritizing value-based care models, which reward ambulatory centers for efficiency and patient outcomes. Regional analysis indicates that while developed economies are optimizing existing infrastructure through AI and telehealth, emerging economies are focusing on expanding physical access to primary and emergency ambulatory care to support growing middle-class populations.
- Largest Region: North America remains the dominant market shareholder, driven by a mature healthcare infrastructure and the rapid adoption of Ambulatory Surgery Centers (ASCs).
- Fastest-Growing Region: Asia-Pacific is expected to witness the highest CAGR due to rising healthcare investments in China and India and an increasing burden of chronic diseases.
- Largest Segment by Share: Primary Care Clinics currently hold the largest market share by volume, serving as the first point of contact for the majority of patient populations globally.
- Leading Service Type: Surgical Services are experiencing the most rapid growth in terms of revenue contribution due to the high value of outpatient orthopedic and ophthalmic procedures.
Key Takeaways Ambulatory Services Market Size & Forecast
The market forecast reflects a robust trajectory supported by demographic shifts and technological maturation. As the global geriatric population increases, the demand for routine monitoring, diagnostic services, and age-related surgical interventions in ambulatory settings is expected to accelerate. Furthermore, the push for cost-containment by insurance providers is steering patients toward ambulatory centers, which typically offer lower overhead costs compared to full-scale hospitals. Key insights suggest that the integration of electronic health records (EHR) and data analytics will be critical for ambulatory providers to maintain competitive advantages and meet stringent regulatory reporting requirements.
- The market is anticipated to surpass the 6 trillion dollar mark by 2034, reflecting the permanent decentralization of healthcare services.
- United States and Germany are identified as leading countries in clinical innovation and the implementation of outpatient specialized care.
- The shift toward value-based reimbursement models is the single most influential factor affecting profit margins for ambulatory service providers.
- Technological integration, particularly in diagnostic imaging and remote patient monitoring, is becoming a standard requirement for market entry and sustainability.
Ambulatory Services Market Drivers Analysis
The primary drivers of the ambulatory services market revolve around the dual pressures of cost efficiency and clinical advancement. The evolution of anesthesia and surgical instrumentation has made it possible for complex procedures to be performed safely without overnight hospitalization. Furthermore, consumer preference has shifted toward ambulatory settings due to shorter wait times, lower risk of healthcare-associated infections, and the convenience of localized care centers. Governments and private insurers are also incentivizing the use of outpatient facilities to alleviate the burden on overstretched public hospital systems.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in Minimally Invasive Surgery (MIS) | +1.8% | Global | 2025 - 2034 |
| Rising Prevalence of Chronic Diseases | +1.5% | North America and Europe | 2025 - 2030 |
| Shift Toward Value-Based Care Models | +1.2% | United States | 2026 - 2034 |
| Governmental Support for Outpatient Infrastructure | +0.9% | Asia-Pacific (China, India) | 2025 - 2034 |
Ambulatory Services Market Restraints Analysis
Despite strong growth prospects, the market faces significant hurdles related to workforce management and regulatory complexity. There is a global shortage of specialized nursing and technical staff capable of operating in fast-paced ambulatory environments. Additionally, the initial capital expenditure required to equip specialized centers with high-end diagnostic and surgical technology can be prohibitive for smaller physician-owned practices. Regulatory variations across different jurisdictions also complicate the expansion strategies of multinational ambulatory service chains.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shortage of Skilled Healthcare Professionals | -0.7% | Global | 2025 - 2034 |
| Stringent Regulatory and Licensing Requirements | -0.5% | Europe and North America | 2025 - 2028 |
| High Initial Capital Investment | -0.4% | Developing Regions | 2025 - 2030 |
Ambulatory Services Market Opportunities Analysis
The convergence of Artificial Intelligence (AI) and telehealth presents a monumental opportunity for the ambulatory sector. AI-driven predictive analytics can optimize patient scheduling and resource allocation, while telehealth enables ambulatory centers to extend their reach into rural and underserved areas. There is also a burgeoning opportunity in the field of precision medicine, where ambulatory diagnostic centers can provide personalized genomic testing and targeted therapy monitoring. The expansion of private-public partnerships in emerging markets offers a gateway for established players to capture new patient demographics.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of AI and Machine Learning | +1.4% | Developed Economies | 2027 - 2034 |
| Expansion of Telehealth-Hybrid Models | +1.1% | Global (Rural Areas) | 2025 - 2034 |
| Growth in Precision Medicine Diagnostics | +0.8% | North America and APAC | 2026 - 2034 |
Ambulatory Services Market Challenges Impact Analysis
One of the most pressing challenges is the increasing threat of cybersecurity breaches as ambulatory centers become more digitized. Protecting sensitive patient data while maintaining seamless interoperability between different healthcare systems is a complex technical task. Additionally, ambulatory providers must navigate fluctuating reimbursement rates from both government and private payers, which can impact long-term financial planning. The competition for prime real estate in urban areas also poses a physical barrier to the expansion of new clinic locations.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Data Security and Cyber Threats | -0.6% | Global | 2025 - 2034 |
| Fluctuating Reimbursement Policies | -0.5% | United States and UK | 2025 - 2029 |
| Interoperability of Digital Health Platforms | -0.3% | Global | 2026 - 2034 |
Ambulatory Services Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global ambulatory services ecosystem, focusing on service delivery models, technological integration, and regional regulatory landscapes. It provides a granular breakdown of market dynamics across primary, emergency, and specialized care segments. The report also examines the strategic positioning of key market participants and the impact of macroeconomic factors such as healthcare policy reforms and demographic shifts on the long-term forecast. This comprehensive study serves as a critical tool for stakeholders to identify high-growth segments and optimize their investment strategies.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 3,629.2 Billion |
| Market Forecast in 2034 | USD 6,241.5 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Encompass Health, UnitedHealth Group (Optum), Tenet Healthcare, HCA Healthcare, Surgery Partners, AmSurg, DaVita Inc., Fresenius Medical Care, Sonic Healthcare, Quest Diagnostics, Laboratory Corporation of America Holdings (LabCorp), Select Medical Corporation, Aspen Healthcare, Spire Healthcare, Ramsay Health Care, Medical Facilities Corporation, Ardent Health Services, Community Health Systems, Lifepoint Health. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The ambulatory services market is segmented based on facility type, service category, and ownership model to provide a comprehensive view of the competitive landscape. The facility type segment highlights the dominance of primary care clinics while showcasing the rapid rise of specialty-specific centers such as orthopedic or oncology-focused ambulatory units. Service-based segmentation reveals a growing preference for diagnostic and wellness services as preventative medicine gains traction. Ownership analysis indicates a trend toward consolidation, with large corporate entities and hospital systems acquiring independent physician-owned practices to create integrated care networks.
- Primary Care Clinics: The foundational segment providing essential health services, including routine check-ups and chronic disease management.
- Ambulatory Surgery Centers (ASCs): Highly specialized facilities focusing on same-day surgical procedures, demonstrating high profitability and growth.
- Diagnostic Centers: Facilities providing imaging (MRI, CT, X-ray) and laboratory services, critical for early disease detection.
- Emergency Departments (Outpatient): Independent or hospital-affiliated units managing urgent but non-life-threatening conditions.
- Medical Specialty Clinics: Specialized units for cardiology, gastroenterology, dermatology, and other specific medical fields.
Regional Highlights
- North America: Holds the largest market share due to high healthcare spending, a robust network of ASCs, and advanced digital health adoption. The United States is the primary contributor, fueled by Medicare and private insurance policies favoring outpatient care.
- Europe: Characterized by strong government-backed healthcare systems in Germany, France, and the UK. There is an increasing trend toward privatizing certain ambulatory functions to improve efficiency and reduce public waiting lists.
- Asia-Pacific: The fastest-growing region, led by China and India. Rapid urbanization, a burgeoning middle class, and significant investments in healthcare infrastructure are driving the expansion of ambulatory clinics.
- Latin America: Showing steady growth in Brazil and Mexico, primarily through the expansion of private diagnostic networks and specialized outpatient clinics.
- Middle East & Africa: Experiencing growth in the GCC countries due to economic diversification efforts and a focus on building world-class medical cities that prioritize ambulatory care models.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Ambulatory Services Market.- Encompass Health
- UnitedHealth Group (Optum)
- Tenet Healthcare (United Surgical Partners International)
- HCA Healthcare
- Surgery Partners
- AmSurg (Envision Healthcare)
- DaVita Inc.
- Fresenius Medical Care
- Sonic Healthcare
- Quest Diagnostics
- Laboratory Corporation of America Holdings (LabCorp)
- Select Medical Corporation
- Aspen Healthcare
- Spire Healthcare
- Ramsay Health Care
- Medical Facilities Corporation
- Ardent Health Services
- Community Health Systems
- Lifepoint Health
- Universal Health Services, Inc.
Frequently Asked Questions
What is the current and projected size of the Ambulatory Services Market?
The Ambulatory Services Market is estimated at USD 3,854.2 Billion in 2026 and is projected to grow to USD 6,241.5 Billion by 2034, following a CAGR of 6.2%.
What are the primary factors driving the shift to ambulatory care?
The primary drivers include advancements in minimally invasive surgical techniques, the cost-effectiveness of outpatient care compared to inpatient stays, and a growing consumer preference for convenience and shorter recovery times.
Which region is expected to grow the fastest during the forecast period?
Asia-Pacific is anticipated to be the fastest-growing region, driven by rising healthcare investments, an aging population in countries like Japan and China, and improving access to medical services in emerging economies.
What are the main challenges facing ambulatory service providers?
Key challenges include a shortage of specialized healthcare professionals, high initial costs for medical technology, and the need for robust cybersecurity to protect patient data in increasingly digital environments.
How is technology influencing the ambulatory services market?
Technology is a major catalyst, with AI improving diagnostic accuracy, EHR systems enhancing patient data management, and telehealth expanding the reach of ambulatory services to remote populations.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted