Automotive Metal Market
Automotive Metal Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711075 | Published On : October 04, 2026 |
Format : 


 | Author : Ashraf Shehata
Automotive Metal Market Size
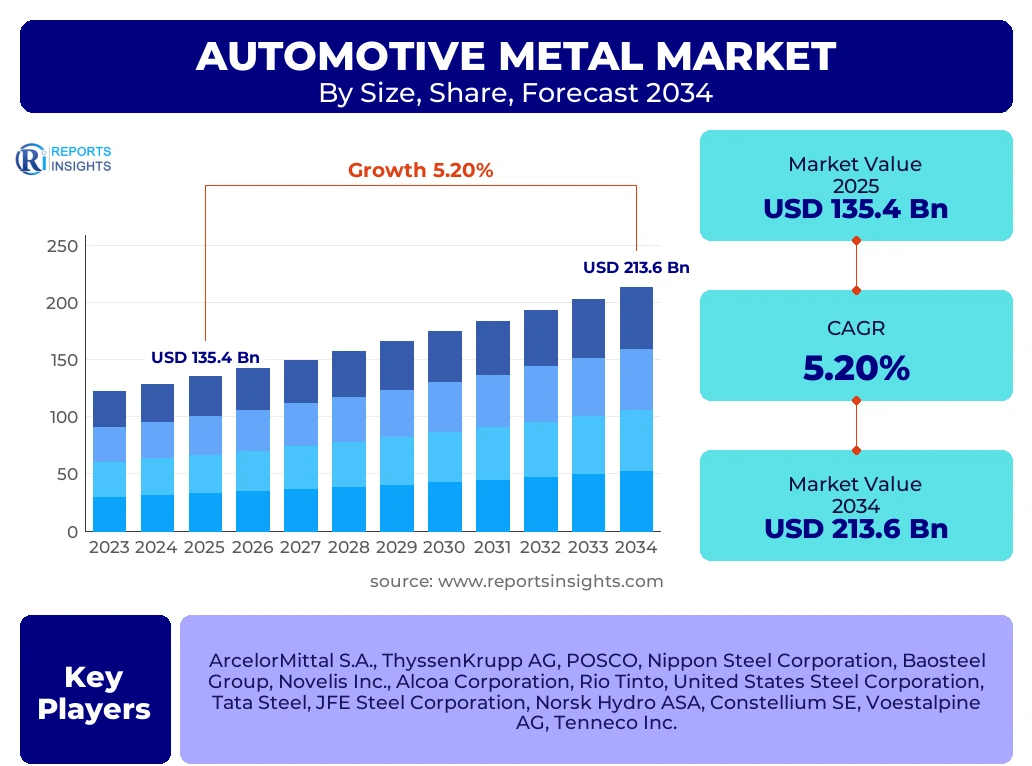
According to Reports Insights Consulting Pvt Ltd, The Automotive Metal Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% between 2025 and 2034. The market is estimated at USD 142.5 Billion in 2026 and is projected to reach USD 213.6 Billion by the end of the forecast period in 2034.
Key Automotive Metal Market Trends & Insights
The global automotive metal sector is undergoing a profound transformation driven by the dual imperatives of decarbonization and vehicle electrification. As manufacturers pivot toward electric vehicles (EVs), the demand for lightweight materials such as aluminum and high-strength steel (HSS) has intensified to offset the significant weight of battery packs. Furthermore, the industry is seeing a shift toward circular economy principles, with a heightened focus on scrap metal recovery and the utilization of green steel produced via hydrogen-based reduction. Regional dynamics indicate a strong consolidation in the Asia-Pacific region, fueled by massive production capacities in China and India, while North American and European markets focus on high-value specialty alloys and sustainable sourcing.
- Largest Region: Asia-Pacific remains the dominant market, accounting for over 45% of the global share due to high vehicle production volumes.
- Fastest Growing Region: Asia-Pacific is also expected to maintain the highest CAGR, supported by industrialization and the rapid adoption of electric mobility in China and Southeast Asia.
- Largest Segment: Steel remains the largest material segment by volume and value, though Aluminum is the fastest-growing sub-segment.
- Leading Application: Body-in-White (BIW) represents the largest application area, necessitating advanced structural metals for safety and aerodynamics.
Key Takeaways Automotive Metal Market Size & Forecast
The market trajectory for automotive metals is increasingly dictated by regulatory frameworks targeting carbon neutrality and the technical requirements of next-generation mobility. Key insights suggest that while traditional iron and steel continue to provide the structural backbone of the industry, the integration of Advanced High-Strength Steel (AHSS) and aluminum alloys is critical for meeting stringent fuel efficiency and range requirements. Stakeholders are investing heavily in metallurgy to produce metals that offer superior crashworthiness without compromising on weight. The forecast period will likely see a significant rise in copper consumption, specifically for EV motor windings and charging infrastructure, signaling a diversification of the metal mix beyond structural components.
- Material Substitution: A significant transition from conventional mild steel to AHSS and Aluminum is occurring to facilitate vehicle lightweighting.
- EV Influence: The surge in EV production is driving exponential demand for copper and specialized aluminum housing for battery thermal management.
- Sustainability Focus: Tier 1 suppliers are prioritizing green-certified metals to meet Scope 3 emission targets set by global automotive OEMs.
- Regional Leadership: China, the United States, and Germany are identified as the primary hubs for metallurgical innovation and automotive metal consumption.
Automotive Metal Market Drivers Analysis
The primary catalysts for the automotive metal market include the global expansion of the electric vehicle ecosystem and the implementation of aggressive corporate average fuel economy (CAFE) standards. These drivers compel manufacturers to adopt materials that enhance structural integrity while reducing mass. Additionally, the recovery of global automotive production following supply chain stabilizations has created a steady demand for primary and secondary metal processing.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Shift Toward Electric Vehicles (EVs) | +1.8% | Global (China, EU leading) | 2025 - 2034 |
| Stringent Emission and Fuel Efficiency Standards | +1.2% | North America, Europe | 2025 - 2030 |
| Rising Demand for Advanced High-Strength Steel (AHSS) | +0.9% | Asia-Pacific, Europe | 2026 - 2034 |
| Expansion of Automotive Production in Emerging Economies | +1.3% | India, Brazil, Southeast Asia | 2025 - 2034 |
Automotive Metal Market Restraints Analysis
Market growth is tempered by the high volatility of raw material prices, including iron ore and aluminum, which directly affects the profit margins of OEMs. Furthermore, the increasing competition from alternative materials like carbon fiber reinforced plastics (CFRP) and advanced composites presents a long-term threat to traditional metal dominance in high-performance and luxury vehicle segments.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Raw Material and Energy Prices | -0.8% | Global | 2025 - 2034 |
| Competition from Lightweight Composites and Plastics | -0.5% | Europe, North America | 2027 - 2034 |
| High Capital Expenditure for Advanced Smelting and Processing | -0.4% | Global | 2025 - 2030 |
Automotive Metal Market Opportunities Analysis
Significant opportunities reside in the development of green steel and the implementation of giga-casting technologies. Giga-casting, pioneered by leading EV manufacturers, allows for the production of large, single-piece aluminum structural components, drastically reducing the number of parts and manufacturing complexity. Moreover, the focus on closed-loop recycling offers a sustainable and cost-effective pathway for sourcing high-quality automotive-grade metals.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Giga-Casting and Mega-Casting Technologies | +1.5% | USA, China, Germany | 2026 - 2034 |
| Development of Low-Carbon Green Steel | +1.1% | Europe (Sweden, Germany) | 2025 - 2034 |
| Enhanced Recycling and Secondary Metal Utilization | +0.7% | Global | 2028 - 2034 |
Automotive Metal Market Challenges Impact Analysis
The industry faces critical challenges regarding supply chain resilience and geopolitical trade tensions. Dependence on specific regions for critical minerals, such as copper and magnesium, exposes the market to supply disruptions. Additionally, the energy-intensive nature of metal production creates a conflict with global sustainability goals, necessitating rapid innovation in low-emission manufacturing processes.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Geopolitical Trade Tensions and Export Restrictions | -0.6% | China, USA, Russia | 2025 - 2034 |
| Decarbonization Pressures on Metal Smelting Plants | -0.5% | Europe, Asia-Pacific | 2025 - 2030 |
Automotive Metal Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the global automotive metal landscape, covering various metal types, vehicle categories, and application areas. It provides a granular look at the competitive environment, regulatory shifts, and technological advancements that are redefining metal consumption in the automotive sector, with a specific focus on the transition toward sustainable and lightweight solutions.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 135.4 Billion |
| Market Forecast in 2034 | USD 213.6 Billion |
| Growth Rate | 5.2% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | ArcelorMittal S.A., ThyssenKrupp AG, POSCO, Nippon Steel Corporation, Baosteel Group, Novelis Inc., Alcoa Corporation, Rio Tinto, United States Steel Corporation, Tata Steel, JFE Steel Corporation, Norsk Hydro ASA, Constellium SE, Voestalpine AG, Tenneco Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The automotive metal market is segmented based on metal type, application, product form, and vehicle type. Steel continues to dominate the market share due to its cost-effectiveness and recyclability, while Aluminum is gaining ground rapidly in the premium and EV sectors for its weight-saving properties. Application-wise, the Body-in-White segment remains the largest consumer of metals, as it constitutes the primary structural frame of the vehicle. Emerging segments like battery trays for electric vehicles are creating new demand streams for extruded aluminum and specialty steel alloys.
- By Metal Type:
- Steel (Advanced High-Strength Steel, Mild Steel, Stainless Steel, Others)
- Aluminum (Castings, Sheets, Extrusions)
- Magnesium
- Copper
- Lead and Others
- By Application:
- Body Structure (BIW)
- Powertrain Components
- Chassis and Suspension
- Interior and Decorative Trim
- Electrical and Electronics (Copper wiring)
- By Vehicle Type:
- Passenger Cars (Sedans, SUVs, Hatchbacks)
- Light Commercial Vehicles (LCVs)
- Heavy Commercial Vehicles (HCVs)
- Electric and Hybrid Vehicles
Regional Highlights
The global distribution of the automotive metal market is heavily skewed toward manufacturing powerhouses in Asia and established automotive centers in Europe and North America. Each region is characterized by distinct regulatory drivers and consumer preferences that influence metal selection and procurement strategies.
- Asia-Pacific: The largest and fastest-growing market, led by China's massive vehicle production capacity and the burgeoning automotive sectors in India and Vietnam. The region benefits from localized raw material supply and rapid EV adoption.
- Europe: A pioneer in the adoption of green steel and advanced lightweight alloys. Stringent Euro emission standards drive high demand for aluminum and AHSS. Germany, France, and Italy remain key players.
- North America: Driven by the demand for Light Commercial Vehicles (LCVs) and SUVs, which require heavy-duty structural metals. The United States is seeing a resurgence in domestic steel and aluminum production to support local EV supply chains.
- Latin America: Brazil and Mexico are emerging as key export hubs for passenger vehicles, leading to a steady increase in automotive metal consumption.
- Middle East and Africa: A developing market with growth primarily centered around vehicle assembly plants in South Africa and Morocco.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Automotive Metal Market.- ArcelorMittal S.A.
- ThyssenKrupp AG
- POSCO Holdings Inc.
- Nippon Steel Corporation
- Baosteel Group
- Novelis Inc. (Hindalco Industries)
- Alcoa Corporation
- Rio Tinto PLC
- United States Steel Corporation
- Tata Steel Limited
- JFE Steel Corporation
- Norsk Hydro ASA
- Constellium SE
- Voestalpine AG
- Tenneco Inc.
- SSAB AB
- AK Steel Holding Corporation
- Magna International Inc.
- Hyundai Steel Company
- Kobe Steel, Ltd.
Frequently Asked Questions
The following frequently asked questions provide insights into the core concerns of stakeholders within the automotive metal industry, addressing technical, economic, and environmental factors.
Which metal is currently most dominant in the automotive industry?
Steel remains the most dominant metal in the automotive industry, accounting for the largest volume of vehicle weight. However, there is a distinct shift toward Advanced High-Strength Steel (AHSS) to provide better safety and weight reduction compared to traditional mild steel.
How is the rise of Electric Vehicles (EVs) affecting metal consumption?
EVs are significantly increasing the demand for Aluminum for lightweighting and Copper for electrical components. Aluminum is preferred for battery enclosures and structural frames to offset battery weight, while copper is essential for traction motors and high-voltage wiring.
What is Green Steel, and why is it important for automotive OEMs?
Green Steel is produced using renewable energy sources and hydrogen instead of coal, significantly reducing carbon emissions. It is crucial for automotive OEMs to meet their sustainability targets and comply with increasing environmental regulations regarding life-cycle vehicle emissions.
What role does Giga-casting play in the future of automotive metals?
Giga-casting involves using massive high-pressure die-casting machines to create large single-piece aluminum components. This technology reduces the number of individual steel parts and welds, leading to lighter vehicles and more efficient manufacturing processes.
Which region is expected to lead the automotive metal market growth through 2034?
The Asia-Pacific region is expected to lead the market growth due to the high volume of vehicle production in China and India, coupled with significant investments in both traditional and electric vehicle infrastructure across the continent.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted