Aerospace Parts Manufacturing Market
Aerospace Parts Manufacturing Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710893 | Published On : September 14, 2026 |
Format : 


 | Author : Ashraf Shehata
Aerospace Parts Manufacturing Market Size
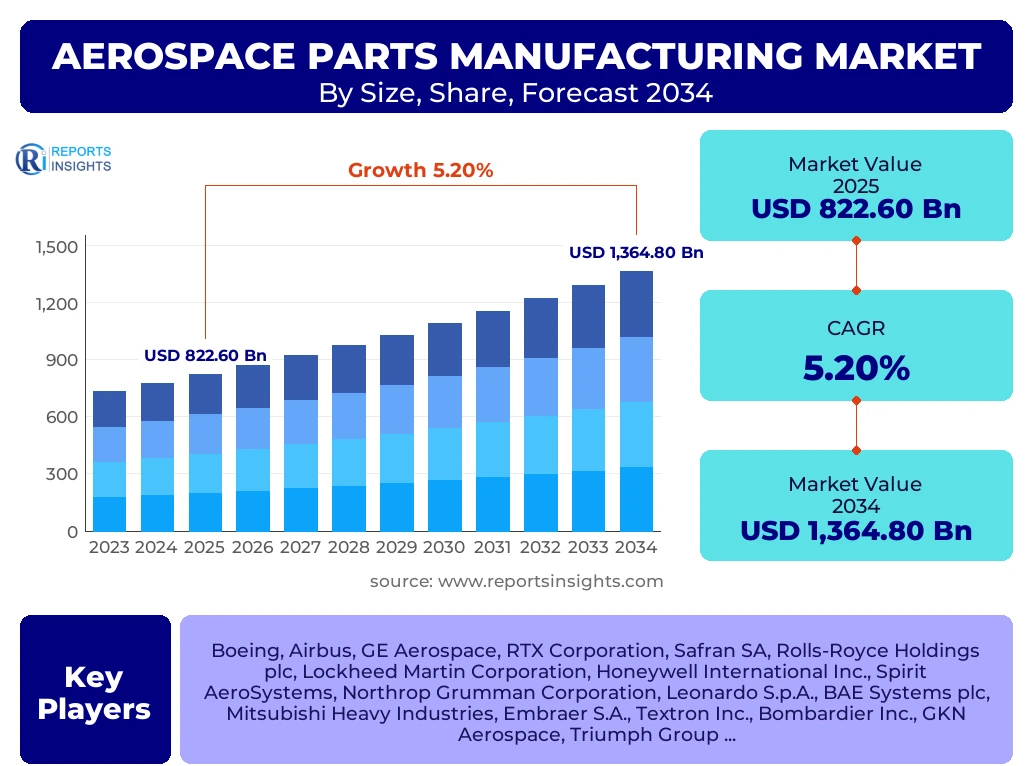
According to Reports Insights Consulting Pvt Ltd, The Aerospace Parts Manufacturing Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% between 2026 and 2034. The market is estimated at USD 865.40 Billion in 2026 and is projected to reach USD 1,364.80 Billion by the end of the forecast period in 2034.
Key Aerospace Parts Manufacturing Market Trends & Insights
The global aerospace parts manufacturing landscape is undergoing a profound transformation driven by the integration of Industry 4.0 technologies and a heightened focus on sustainability. Analysis of regional insights reveals that while North America remains the dominant revenue generator due to the presence of major original equipment manufacturers (OEMs), the Asia-Pacific region is experiencing the fastest growth, propelled by expanding commercial aviation sectors in China and India. Competitive benchmarking indicates a shift toward vertically integrated supply chains where Tier 1 suppliers are increasingly adopting advanced robotics and digital twin technology to optimize production cycles. Furthermore, the market is seeing a significant pivot toward lightweight composite materials and additive manufacturing to meet stringent fuel efficiency and emission standards. These trends suggest a market that is moving away from traditional subtractive manufacturing toward highly precise, data-driven production methodologies that prioritize structural integrity and environmental compliance.
- Largest Region: North America remains the primary market leader, accounting for the highest revenue share due to established defense spending and major commercial aircraft production hubs.
- Fastest Growing Region: Asia-Pacific is identified as the fastest-growing region, driven by increasing air passenger traffic and domestic aircraft development programs.
- Largest Segment: The Aerostructure segment continues to hold the largest market share, encompassing the fuselage, wings, and flight control surfaces.
- Technological Trend: Adoption of Additive Manufacturing (3D Printing) for complex engine components and interior brackets to reduce weight and lead times.
- Strategic Shift: Increased emphasis on sustainable aviation fuels (SAF) and electric propulsion systems influencing the design and manufacturing of future engine parts.
Key Takeaways Aerospace Parts Manufacturing Market Size & Forecast
The market size and forecast for aerospace parts manufacturing reflect a robust recovery phase following global supply chain disruptions. Key takeaways indicate that the commercial aircraft sector is the primary engine of growth, though military and defense applications provide a stable foundation for long-term contracts. Investors and stakeholders are focused on the "backlog" of major aircraft orders, which guarantees demand for components over the next decade. The integration of advanced materials, such as carbon-fiber-reinforced polymers, is no longer a niche requirement but a standard expectation for next-generation narrow-body and wide-body aircraft. Furthermore, the market is characterized by intense consolidation among small to medium-sized enterprises (SMEs) to form larger, more resilient entities capable of meeting the rigorous quality standards of global aerospace giants.
- Market Valuation: The sector is poised to exceed the trillion-dollar mark by 2030, reflecting steady demand in both civil and defense sectors.
- Leading Country: The United States maintains the strongest position globally, supported by the worlds largest defense budget and a massive commercial aerospace ecosystem.
- Defense Modernization: Increasing geopolitical tensions are driving the modernization of fighter jets and transport aircraft, boosting the demand for high-performance military components.
- Supply Chain Resilience: A shift toward "friend-shoring" and localizing supply chains to mitigate risks associated with international logistics and political instability.
- Maintenance, Repair, and Overhaul (MRO): The aging global aircraft fleet is creating a secondary but highly lucrative market for replacement parts and retrofitting services.
Aerospace Parts Manufacturing Market Drivers Analysis
The primary drivers of the aerospace parts manufacturing market are rooted in the rising global demand for air travel and the continuous need for fleet modernization. As airlines seek to replace aging, fuel-inefficient aircraft with newer models, the demand for sophisticated components—ranging from advanced avionics to high-bypass turbofans—intensifies. Additionally, the proliferation of low-cost carriers in emerging economies is necessitating the production of more narrow-body aircraft. Defense spending, particularly in the realm of unmanned aerial vehicles (UAVs) and next-generation stealth technology, also acts as a significant catalyst for innovation and production volume in the manufacturing sector.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Increasing Demand for Fuel-Efficient Aircraft | +1.5% | Global (Strongest in Europe/NA) | 2025 - 2034 |
| Expansion of Commercial Aviation in APAC | +1.2% | China, India, SE Asia | 2026 - 2034 |
| Rise in Global Defense Expenditures | +0.9% | USA, NATO, Middle East | 2025 - 2030 |
| Advancements in Additive Manufacturing | +0.6% | Germany, USA, Japan | 2027 - 2034 |
Aerospace Parts Manufacturing Market Restraints Analysis
Despite growth, the market faces significant restraints, most notably the high capital expenditure required for research, development, and manufacturing infrastructure. The aerospace industry is subject to some of the most stringent regulatory certifications in the world, which can delay the introduction of new parts and increase production costs. Additionally, the volatility of raw material prices—such as titanium, aluminum, and specialized alloys—can squeeze profit margins for manufacturers. Labor shortages in high-skill areas like precision engineering and metallurgy also pose a threat to production capacity.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Regulatory Compliance Costs | -0.7% | Europe (EASA), USA (FAA) | Ongoing |
| Raw Material Price Volatility | -0.5% | Global | 2025 - 2028 |
| Shortage of Skilled Labor Force | -0.4% | North America and Europe | 2025 - 2034 |
Aerospace Parts Manufacturing Market Opportunities Analysis
The emergence of Urban Air Mobility (UAM) and the development of electric vertical take-off and landing (eVTOL) aircraft represent a frontier of opportunity for parts manufacturers. These new aircraft types require unique components, including high-density battery enclosures, lightweight electric motors, and advanced composite frames. Furthermore, the digital transformation of the aftermarket through predictive maintenance provides an opportunity for manufacturers to offer "Parts-as-a-Service," where they manage the lifecycle and replacement of components using IoT data. Space exploration and the commercialization of low-earth orbit (LEO) also present a growing niche for specialized, high-durability aerospace parts.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Emergence of eVTOL and UAM Platforms | +1.1% | USA, Germany, China | 2028 - 2034 |
| Growth in Space Exploration Components | +0.8% | USA, India, Russia | 2026 - 2034 |
| Digitization of MRO Services | +0.5% | Global | 2025 - 2034 |
Aerospace Parts Manufacturing Market Challenges Impact Analysis
One of the most pressing challenges is the decarbonization of the aerospace sector. Manufacturers are under immense pressure to design parts that contribute to zero-emission goals, necessitating a total rethink of engine architecture and material science. Geopolitical instability also challenges global supply chains, as disruptions in the supply of critical minerals from certain regions can halt production lines for months. Furthermore, the cyber-security of connected manufacturing systems (Smart Factories) is becoming a critical concern, as a breach could compromise intellectual property or the structural integrity of safety-critical components.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Geopolitical Risks | -0.8% | Global (Transitioning sources) | 2025 - 2030 |
| Decarbonization and Emission Standards | -0.6% | Europe, North America | 2025 - 2034 |
| Cybersecurity in Digital Manufacturing | -0.3% | Technologically Advanced Nations | 2026 - 2034 |
Aerospace Parts Manufacturing Market - Updated Report Scope
This report provides a comprehensive analysis of the global aerospace parts manufacturing sector, covering commercial, military, and general aviation segments. It includes detailed revenue forecasts, competitive landscape mapping, and an analysis of the technological shifts impacting production. The scope extends from primary structural components to intricate avionics and cabin interior systems, offering a granular view of the value chain across all major geographic regions.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 822.60 Billion |
| Market Forecast in 2034 | USD 1,364.80 Billion |
| Growth Rate | 5.2% CAGR |
| Number of Pages | 256 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Boeing, Airbus, GE Aerospace, RTX Corporation, Safran SA, Rolls-Royce Holdings plc, Lockheed Martin Corporation, Honeywell International Inc., Spirit AeroSystems, Northrop Grumman Corporation, Leonardo S.p.A., BAE Systems plc, Mitsubishi Heavy Industries, Embraer S.A., Textron Inc., Bombardier Inc., GKN Aerospace, Triumph Group, Liebherr-International AG. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The aerospace parts manufacturing market is segmented primarily by product type and end-use application. The aerostructure segment remains the cornerstone of the industry, involving the production of complex fuselage sections and wing assemblies. Engine parts represent the highest value-to-weight ratio, where innovations in cooling systems and turbine blades are constant. Avionics and cabin interiors are seeing increased investment as passenger experience and cockpit automation become central to airline competitiveness. Material-based segmentation shows a definitive trend toward composite materials, which offer superior strength-to-weight ratios compared to traditional aluminum alloys.
- Aerostructures: Includes fuselage, wings, empennage, and flight control surfaces. This is the largest segment by physical volume and value.
- Engine Parts: High-precision components including turbine blades, compressors, and housings. High focus on thermal resistance and fuel efficiency.
- Avionics: Electronic systems used on aircraft, including communications, navigation, the display and management of multiple systems, and the hundreds of systems that are fitted to aircraft to perform individual functions.
- Cabin Interiors: Seating, galleys, lighting, and in-flight entertainment systems. Growing focus on lightweight materials and modularity.
- Insulation Components: Critical for thermal and acoustic management within the aircraft fuselage.
- End-use Commercial: Driven by narrow-body aircraft demand for short-haul and regional routes.
- End-use Military: Driven by stealth capabilities and high-performance jet engine requirements.
Regional Highlights
- North America: The largest market globally, the U.S. is the primary hub for both Boeing and major defense contractors like Lockheed Martin. It leads in technological innovation and high-value part manufacturing.
- Europe: Home to Airbus and major Tier 1 suppliers like Safran and Rolls-Royce. The region is a leader in sustainability initiatives and advanced engine technology.
- Asia-Pacific: The fastest-growing region. China’s COMAC and India’s growing defense and civil aviation sectors are driving local manufacturing capabilities and infrastructure development.
- Middle East: A major hub for MRO services and a growing base for defense-related parts manufacturing, supported by high state investment in Saudi Arabia and the UAE.
- Latin America: Embraer in Brazil remains a critical player, specializing in regional jets and narrow-body components, fostering a regional ecosystem for parts manufacturing.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Aerospace Parts Manufacturing Market.- Boeing
- Airbus
- GE Aerospace
- RTX Corporation (Pratt & Whitney/Collins Aerospace)
- Safran SA
- Rolls-Royce Holdings plc
- Lockheed Martin Corporation
- Honeywell International Inc.
- Spirit AeroSystems
- Northrop Grumman Corporation
- Leonardo S.p.A.
- BAE Systems plc
- Mitsubishi Heavy Industries
- Embraer S.A.
- Textron Inc.
- Bombardier Inc.
- GKN Aerospace
- Triumph Group
- Liebherr-International AG
- Stork BV
Frequently Asked Questions
What is the current market size of the Aerospace Parts Manufacturing industry?
The Aerospace Parts Manufacturing Market is estimated at USD 865.40 Billion in 2026 and is expected to grow significantly as aircraft delivery rates return to pre-pandemic levels and defense modernization programs accelerate globally.
Which factors are driving the growth of the aerospace parts market?
The primary growth drivers include the increasing demand for fuel-efficient aircraft, the rise of low-cost carriers in Asia-Pacific, significant increases in global defense spending, and the integration of advanced manufacturing technologies like 3D printing.
Who are the leading players in the aerospace parts manufacturing sector?
Major players include Boeing, Airbus, GE Aerospace, RTX Corporation, and Safran. These companies are increasingly focusing on sustainable technologies and digital transformation to maintain their competitive edge.
How is additive manufacturing impacting the aerospace parts industry?
Additive manufacturing, or 3D printing, allows for the production of complex, lightweight components that were previously impossible to manufacture. This reduces material waste, lowers aircraft weight, and simplifies supply chains by allowing on-demand production of spare parts.
Which region is expected to grow the fastest in the forecast period?
The Asia-Pacific region is projected to be the fastest-growing market due to rapid urbanization, increasing middle-class populations in China and India, and significant investments in domestic aircraft manufacturing programs.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted