Automotive Battery Market
Automotive Battery Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711345 | Published On : October 28, 2026 |
Format : 


 | Author : Ashraf Shehata
Automotive Battery Market Size
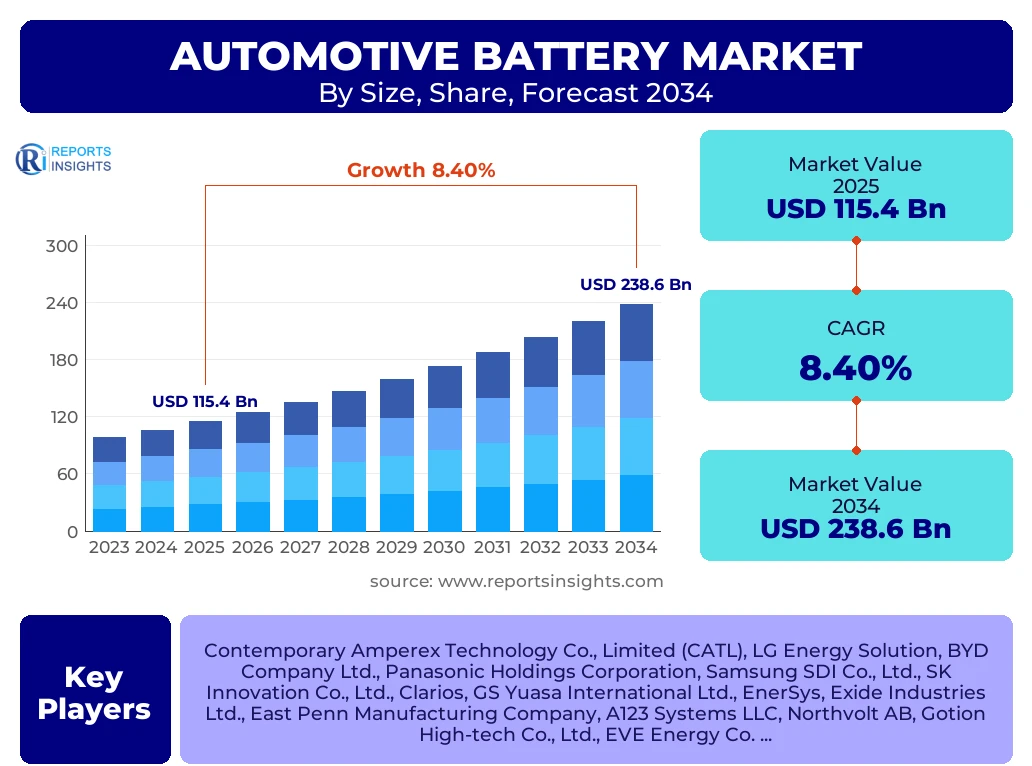
According to Reports Insights Consulting Pvt Ltd, The Automotive Battery Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.4% between 2025 and 2034. The market is estimated at USD 125.1 Billion in 2026 and is projected to reach USD 238.6 Billion by the end of the forecast period in 2034.
Key Automotive Battery Market Trends & Insights
The global automotive battery landscape is undergoing a radical transformation driven by the aggressive transition from internal combustion engines to electric drivetrains. The convergence of strict carbon emission mandates, substantial government subsidies, and rapid advancements in cell chemistry is redefining competitive benchmarks. Current market trends indicate a significant pivot toward Lithium Iron Phosphate (LFP) chemistry due to its cost-effectiveness and thermal stability, alongside intensive research into solid-state batteries which promise higher energy density and faster charging cycles. Furthermore, the integration of smart Battery Management Systems (BMS) and the development of circular economy initiatives for battery recycling are becoming critical pillars for sustainable growth across all regional clusters.
- Largest Region: Asia-Pacific remains the dominant force, accounting for over 45% of the total market share, bolstered by China’s massive manufacturing ecosystem.
- Fastest Growing Region: Europe is expected to witness the highest CAGR during the forecast period, driven by the implementation of the "Fit for 55" package and heavy investments in gigafactories.
- Largest Segment by Type: The Lithium-ion battery segment holds the majority share in terms of value, surpassing traditional lead-acid variants due to the proliferation of electric vehicles (EVs).
- Leading Propulsion Segment: Battery Electric Vehicles (BEVs) represent the largest and fastest-growing propulsion category within the battery market ecosystem.
Key Takeaways Automotive Battery Market Size & Forecast
The automotive battery market is poised for a decade of sustained expansion, characterized by a shift from auxiliary power applications to primary propulsion energy storage. Analysis suggests that the decline in battery pack prices—achieved through economies of scale and vertical integration—is the primary catalyst for reaching price parity between EVs and traditional vehicles. Stakeholders are increasingly focusing on securing upstream supply chains for critical minerals like lithium, cobalt, and nickel to mitigate price volatility. The forecast period will likely see the lead-acid market stabilize around heavy commercial vehicles and aftermarket replacements, while the lithium-based market dominates the passenger vehicle segment through 2034.
- Global Value Surge: The total market value is anticipated to nearly double by 2034, reflecting the global commitment to electrification.
- Chemistry Shift: LFP (Lithium Iron Phosphate) is rapidly gaining ground over NMC (Nickel Manganese Cobalt) in mass-market vehicle segments to reduce costs.
- Infrastructure Correlation: Market growth is intrinsically linked to the expansion of ultra-fast charging networks across North America and Europe.
- Strategic Localization: There is a visible trend of regionalizing battery production to reduce logistics costs and comply with domestic content requirements like the US Inflation Reduction Act (IRA).
- Aftermarket Potential: The replacement battery market for aging EV fleets is expected to emerge as a significant revenue stream by the early 2030s.
Automotive Battery Market Drivers Analysis
The primary impetus for the automotive battery market stems from the global regulatory push for decarbonization and the subsequent surge in consumer demand for zero-emission vehicles. As global economies strive to meet net-zero targets, the automotive sector is being forced to adopt cleaner energy solutions. Technological innovations that enhance energy density and reduce charging times are making electric vehicles more practical for the average consumer, thereby accelerating market adoption. Additionally, the decrease in the cost of raw materials and manufacturing processes is making high-performance batteries more accessible to a wider range of vehicle manufacturers.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Shift Toward Electric Vehicles (EVs) | +4.2% | Global | 2025-2034 |
| Stringent Government Emission Regulations | +2.5% | Europe, North America | 2025-2030 |
| Advancements in Battery Chemistry (Solid-State/LFP) | +1.8% | Japan, South Korea, China | 2027-2034 |
| Expansion of Charging Infrastructure | +1.2% | USA, China, Germany | 2025-2034 |
Automotive Battery Market Restraints Analysis
Despite the optimistic growth outlook, the market faces significant headwinds, primarily related to the volatility of raw material prices and supply chain vulnerabilities. The concentration of lithium and cobalt mining in specific geographic locations poses a risk to consistent production. Furthermore, the environmental concerns associated with mining and the lack of a standardized global recycling framework could act as deterrents for sustainable market growth. High initial costs of advanced battery systems compared to internal combustion engines also remain a barrier in price-sensitive emerging markets.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Raw Material Prices (Lithium, Cobalt) | -1.5% | Global | 2025-2028 |
| Environmental and Ethical Mining Concerns | -0.8% | Africa, South America | 2025-2034 |
| Supply Chain Disruptions and Geopolitical Tensions | -1.2% | China, USA, EU | 2025-2030 |
Automotive Battery Market Opportunities Analysis
The evolution of the automotive battery sector presents lucrative opportunities in the realm of second-life battery applications and the development of next-generation solid-state technology. Repurposing retired EV batteries for stationary energy storage systems (ESS) offers a sustainable way to extend the value chain. Moreover, the burgeoning research into sodium-ion batteries provides a cost-effective alternative for entry-level electric vehicles and micro-mobility solutions, potentially opening new market segments in developing economies. The integration of artificial intelligence in battery management systems also presents a high-growth avenue for software and hardware providers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Second-Life Battery Energy Storage Systems | +1.5% | Global | 2028-2034 |
| Commercialization of Solid-State Batteries | +3.2% | Japan, Germany, USA | 2029-2034 |
| Sodium-ion Battery Adoption for Low-cost EVs | +1.1% | India, China, Brazil | 2026-2034 |
Automotive Battery Market Challenges Impact Analysis
The industry must navigate complex technical and logistical challenges, including the need for extreme temperature performance and the mitigation of thermal runaway risks. Ensuring the safety and longevity of batteries under diverse climatic conditions remains a significant hurdle for manufacturers. Additionally, the rapid pace of technological obsolescence requires companies to invest heavily in R&D, which can strain the profit margins of smaller players. Establishing a comprehensive and efficient closed-loop recycling system is also a monumental task that requires cross-industry collaboration and supportive regulatory frameworks.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Safety Concerns and Thermal Management Issues | -0.5% | Global | 2025-2034 |
| Lack of Standardized Recycling Infrastructure | -0.9% | Global | 2025-2030 |
| Intense R&D Capital Requirements | -0.4% | Global | 2025-2034 |
Automotive Battery Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the global automotive battery market, providing granular insights into various battery chemistries, vehicle types, and propulsion technologies. It examines the entire value chain, from raw material sourcing and cell manufacturing to battery pack integration and end-of-life recycling. The report also evaluates the impact of macroeconomic factors, technological breakthroughs, and regional regulatory landscapes on market dynamics through 2034, offering a strategic roadmap for manufacturers, investors, and policymakers.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 115.4 Billion |
| Market Forecast in 2034 | USD 238.6 Billion |
| Growth Rate | 8.4% CAGR |
| Number of Pages | 254 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Contemporary Amperex Technology Co., Limited (CATL), LG Energy Solution, BYD Company Ltd., Panasonic Holdings Corporation, Samsung SDI Co., Ltd., SK Innovation Co., Ltd., Clarios, GS Yuasa International Ltd., EnerSys, Exide Industries Ltd., East Penn Manufacturing Company, A123 Systems LLC, Northvolt AB, Gotion High-tech Co., Ltd., EVE Energy Co., Ltd., CALB Co., Ltd., Farasis Energy, SVOLT Energy Technology, Verkor, Britishvolt (Recharge Industries) |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The automotive battery market is segmented based on technology and application to provide a detailed view of revenue streams and growth pockets. The shift from traditional lead-acid batteries, which dominated the SLI (Starting, Lighting, and Ignition) applications for decades, to high-energy lithium-ion batteries is the most significant structural change in the market. Each segment is influenced by different drivers, such as the electrification of public transport affecting the commercial vehicle segment and the rise of personal mobility driving the passenger car segment.
- By Battery Type:
- Lead-Acid: Remains vital for traditional ICE vehicles and auxiliary functions in EVs.
- Lithium-ion: The dominant chemistry for EV propulsion, split into NMC, LFP, and NCA.
- Nickel-Metal Hydride: Primarily used in older hybrid vehicle models.
- Others: Includes emerging Sodium-ion and Solid-state technologies.
- By Vehicle Propulsion:
- ICE: Utilizes lead-acid batteries for starting and electrical systems.
- BEV: Entirely dependent on large-capacity lithium-ion battery packs.
- HEV/PHEV: Uses a combination of internal combustion and electric battery support.
- By Vehicle Category:
- Passenger Cars: The largest consumer segment by volume.
- Light Commercial Vehicles: Growing segment due to last-mile delivery electrification.
- Heavy Commercial Vehicles: Emerging segment with high demand for high-capacity battery systems.
Regional Highlights
- Asia-Pacific: The regional leader, driven by China's dominant position in battery manufacturing and raw material processing. India is also emerging as a high-growth market due to the "Make in India" initiative and FAME-II subsidies.
- Europe: The fastest-growing region, characterized by aggressive carbon neutrality goals and a robust automotive manufacturing base. Countries like Germany, France, and Norway are at the forefront of EV adoption.
- North America: Significant growth is expected due to the Inflation Reduction Act (IRA), which incentivizes domestic battery production and mineral sourcing. The United States is seeing a surge in gigafactory announcements.
- Latin America: Growth is primarily centered in Brazil and Mexico, focusing on the electrification of urban bus fleets and lead-acid battery exports.
- Middle East and Africa: A developing market with potential in the mining of critical battery minerals (Africa) and the emergence of luxury EV markets in the GCC countries.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Automotive Battery Market.- Contemporary Amperex Technology Co., Limited (CATL)
- LG Energy Solution
- BYD Company Ltd.
- Panasonic Holdings Corporation
- Samsung SDI Co., Ltd.
- SK Innovation Co., Ltd.
- Clarios
- GS Yuasa International Ltd.
- EnerSys
- Exide Industries Ltd.
- East Penn Manufacturing Company
- A123 Systems LLC
- Northvolt AB
- Gotion High-tech Co., Ltd.
- EVE Energy Co., Ltd.
- CALB Co., Ltd.
- Farasis Energy
- SVOLT Energy Technology
- Verkor
- Northvolt AB
Frequently Asked Questions
What is the current market size of the global automotive battery market?
As of 2025, the global automotive battery market is valued at approximately USD 115.4 Billion, with a projected growth path to reach USD 238.6 Billion by 2034.
Which battery chemistry is expected to dominate the future market?
Lithium Iron Phosphate (LFP) is gaining rapid traction for mass-market EVs due to cost and safety, while Solid-State batteries are expected to dominate the high-performance and luxury segments after 2030.
How is the US Inflation Reduction Act affecting the battery market?
The IRA is compelling manufacturers to localize supply chains within North America to qualify for tax credits, leading to a massive investment influx in US-based gigafactories and mineral processing facilities.
What role does battery recycling play in the market forecast?
Battery recycling is critical for long-term sustainability and supply security. It is expected to become a significant part of the value chain by 2030, reducing the industry's reliance on virgin mineral mining.
What are the main growth drivers for the Asia-Pacific region?
Growth in APAC is driven by established manufacturing ecosystems, high domestic demand for EVs in China, government incentives in India, and the presence of world-leading battery technology companies in South Korea and Japan.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
