Automotive Aftermarket Market
Automotive Aftermarket Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711354 | Published On : October 29, 2026 |
Format : 


 | Author : Ashraf Shehata
Automotive AfterMarket Market Size
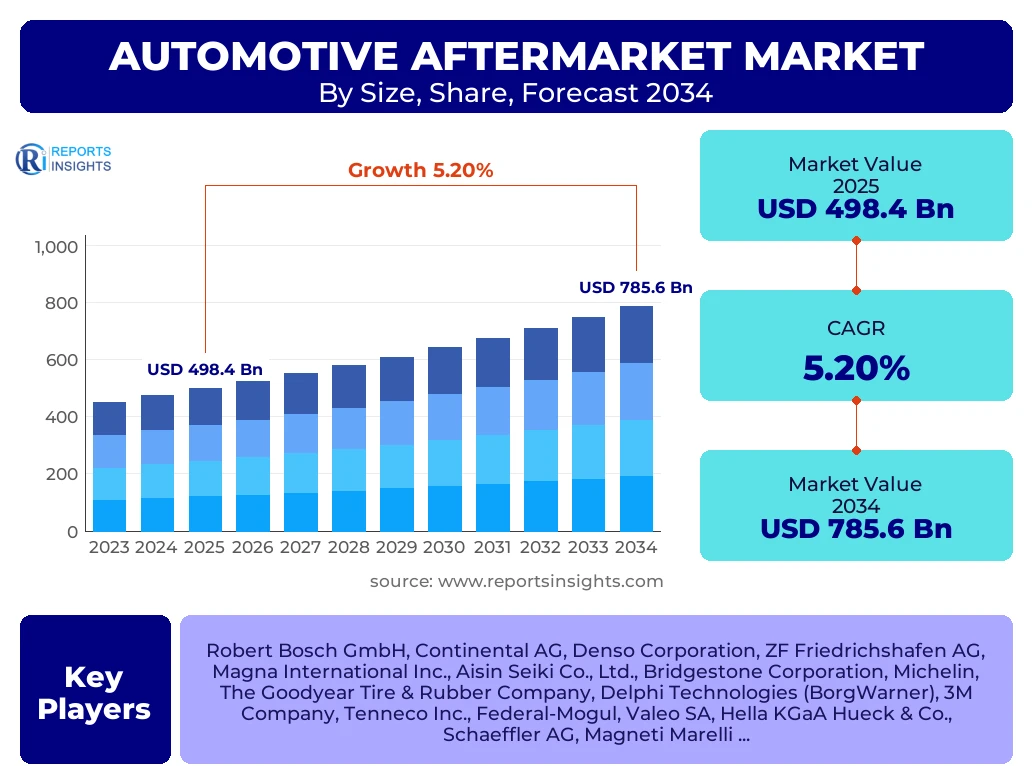
According to Reports Insights Consulting Pvt Ltd, The Automotive AfterMarket Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% between 2025 and 2034. The market is estimated at USD 524.3 Billion in 2026 and is projected to reach USD 785.6 Billion by the end of the forecast period in 2034.
Key Automotive AfterMarket Market Trends & Insights
The global automotive aftermarket is undergoing a profound structural transformation, driven by the convergence of digitalization, vehicle electrification, and changing consumer ownership models. Users frequently inquire about the impact of e-commerce on traditional distribution channels and the resilience of the aftermarket in the face of the rising electric vehicle (EV) penetration. Current market insights suggest a significant shift toward digital sales platforms, with B2B and B2C e-commerce expected to capture a larger share of the total market as workshops and end-users seek pricing transparency and rapid delivery. Furthermore, the integration of advanced telematics is enabling predictive maintenance, allowing service providers to engage with vehicle owners before a component failure occurs, thereby optimizing the supply chain and inventory management. Competitive benchmarking reveals that leading players are increasingly focusing on diagnostic software and high-tech components to cater to the growing complexity of modern vehicle architectures.
- Asia Pacific is the fastest-growing region due to a massive increase in vehicle parc and rising disposable income in emerging economies such as India and China.
- North America remains the largest region in terms of market share, supported by a high average vehicle age and a robust culture of vehicle maintenance and customization.
- The replacement parts segment, specifically tires and engine components, holds the largest market share due to their high wear-and-tear nature and essential role in vehicle operation.
- The digitalization of automotive workshops and the adoption of cloud-based diagnostic tools are emerging as critical trends for maintaining competitive advantages.
- There is a notable shift from Do-It-Yourself (DIY) to Do-It-For-Me (DIFM) services, driven by the increasing technical complexity of modern internal combustion engines and hybrid systems.
Key Takeaways Automotive AfterMarket Market Size & Forecast
The strategic outlook for the automotive aftermarket remains positive, characterized by steady growth in vehicle miles traveled and an aging global vehicle fleet. Stakeholders are particularly focused on the long-term implications of software-defined vehicles and the shift toward sustainable manufacturing processes in the parts industry. Insights into the market size and forecast indicate that while the core components of the internal combustion engine (ICE) will continue to dominate for the next decade, the aftermarket for EV-specific components, such as thermal management systems and high-voltage batteries, is entering a period of exponential growth. Market participants are advised to diversify their portfolios to include both traditional mechanical parts and advanced electronic sensors to mitigate risks associated with the energy transition.
- The average age of light vehicles globally has reached a record high, significantly boosting the demand for maintenance and repair services.
- China is expected to emerge as a dominant force in the global aftermarket, transitioning from a manufacturing hub to a primary consumer market for high-quality replacement parts.
- Sustainability and the circular economy are gaining traction, with remanufactured parts seeing increased adoption due to cost-effectiveness and lower environmental impact.
- Strategic partnerships between original equipment suppliers (OES) and independent aftermarket (IAM) distributors are reshaping the competitive landscape.
- Subscription-based service models and extended warranties are becoming popular tools for customer retention among dealership networks.
Automotive AfterMarket Market Drivers Analysis
The primary catalysts for the automotive aftermarket include the increasing complexity of vehicle electronics, which necessitates professional repair services, and the global trend of consumers holding onto their vehicles for longer periods. Additionally, the rise of ride-sharing and fleet-based mobility services has increased the utilization rates of vehicles, leading to more frequent maintenance cycles. The expansion of the global logistics sector has also bolstered the commercial vehicle aftermarket, as the demand for heavy-duty truck parts remains resilient.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Aging Global Vehicle Fleet | +1.5% | North America & Europe | 2025 - 2034 |
| Expansion of E-commerce Platforms | +1.2% | Global | 2025 - 2030 |
| Rise in Vehicle Miles Traveled (VMT) | +0.8% | Asia Pacific & Latin America | 2026 - 2034 |
| Increased Demand for Remanufactured Parts | +0.6% | Europe | 2025 - 2034 |
Automotive AfterMarket Market Restraints Analysis
Despite strong growth prospects, the market faces significant headwinds from the rapid transition to electric vehicles, which contain fewer moving parts and require less frequent mechanical maintenance compared to ICE vehicles. Furthermore, the volatility of raw material prices and the high costs associated with training technicians for advanced diagnostic tasks present challenges for small-scale independent workshops. Data privacy concerns and restricted access to proprietary vehicle data by OEMs also pose barriers to the independent aftermarket sector.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| EV Penetration & Reduced Part Count | -0.9% | Western Europe & China | 2028 - 2034 |
| OEM Data Access Restrictions | -0.5% | Global | 2025 - 2030 |
| Shortage of Skilled Technicians | -0.4% | North America | 2025 - 2034 |
Automotive AfterMarket Market Opportunities Analysis
The evolution of the automotive landscape presents lucrative opportunities in the realm of ADAS (Advanced Driver Assistance Systems) calibration and sensor replacement. As vehicles become more autonomous, the precision required in repair services increases, allowing specialized workshops to command higher margins. Moreover, the growth of the used car market in emerging economies creates a massive pipeline for aftermarket components. Software updates and cybersecurity services for connected cars represent a new, untapped revenue stream for forward-thinking aftermarket providers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| ADAS Calibration Services | +1.4% | North America & Europe | 2026 - 2034 |
| EV Battery Second-Life & Repair | +1.1% | China & Japan | 2027 - 2034 |
| Predictive Maintenance Telematics | +0.9% | Global | 2025 - 2034 |
Automotive AfterMarket Market Challenges Impact Analysis
The market is currently navigating complex logistical challenges and supply chain disruptions that have led to inventory shortages in critical segments such as semiconductors and specialized alloys. Additionally, the proliferation of counterfeit parts in online marketplaces poses a threat to brand reputation and consumer safety. Ensuring the security of connected vehicle data while providing open-access diagnostics remains a significant hurdle for the industry as a whole.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Counterfeit Parts Proliferation | -0.6% | Middle East & Africa | 2025 - 2034 |
| Supply Chain Fragmentations | -0.5% | Global | 2025 - 2028 |
| Cybersecurity Integration Costs | -0.3% | Global | 2026 - 2034 |
Automotive AfterMarket Market - Updated Report Scope
This comprehensive report provides an in-depth analysis of the global automotive aftermarket, covering replacement parts, accessories, and service components across various vehicle types and distribution channels. The scope encompasses detailed regional analysis, competitive intelligence, and a focus on the emerging technological trends that are redefining the industry's future. It provides a strategic framework for understanding the interplay between OEM strategies and independent aftermarket developments.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 498.4 Billion |
| Market Forecast in 2034 | USD 785.6 Billion |
| Growth Rate | 5.2% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Robert Bosch GmbH, Continental AG, Denso Corporation, ZF Friedrichshafen AG, Magna International Inc., Aisin Seiki Co., Ltd., Bridgestone Corporation, Michelin, The Goodyear Tire & Rubber Company, Delphi Technologies (BorgWarner), 3M Company, Tenneco Inc., Federal-Mogul, Valeo SA, Hella KGaA Hueck & Co., Schaeffler AG, Magneti Marelli, Cooper Tire & Rubber Company, Gates Corporation, Brembo S.p.A. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The automotive aftermarket is segmented by replacement parts, service channels, and vehicle categories to provide a granular view of the revenue streams. Replacement parts constitute the largest segment, with tires and batteries being recurring high-volume items. The distribution channel segment is seeing a rapid migration toward digital platforms, although physical wholesalers still manage the bulk of last-mile logistics for local workshops. The distinction between DIY and DIFM continues to blur as sophisticated tools become more accessible to enthusiasts, though the complexity of modern electronics favors professional service providers.
- By Replacement Parts: Tires, Batteries, Brake Parts, Filters, Lighting & LEDs, Spark Plugs, Collision Body Parts, Exhaust Components, Sensors & Controllers, Steering & Suspension.
- By Service Channel: Do-It-Yourself (DIY), Do-It-For-Me (DIFM), Original Equipment (OE) Service.
- By Distribution Channel: Wholesalers and Distributors, Retailers (Brick-and-Mortar), Online Retailers (E-commerce).
- By Vehicle Type: Passenger Cars, Light Commercial Vehicles (LCV), Heavy Commercial Vehicles (HCV), Off-Road Vehicles.
- By Certification: Genuine Parts, Certified Parts, Uncertified Parts.
Regional Highlights
- North America: The largest market share holder, driven by the United States where the average vehicle age is nearly 12.5 years, creating a massive demand for aging-car maintenance.
- Asia Pacific: The fastest-growing region, with China and India leading the surge due to rapid motorization and the development of local parts manufacturing hubs.
- Europe: A mature market focused on premium services, remanufacturing, and strict environmental regulations that drive the demand for high-efficiency exhaust and emission systems.
- Latin America: Showing steady recovery with Brazil and Mexico as key contributors, primarily in the commercial vehicle and affordable replacement parts segments.
- Middle East & Africa: An emerging market with high demand for cooling systems and heavy-duty parts due to extreme climatic conditions and infrastructure projects.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Automotive AfterMarket Market.- Robert Bosch GmbH
- Continental AG
- Denso Corporation
- ZF Friedrichshafen AG
- Magna International Inc.
- Aisin Seiki Co., Ltd.
- Bridgestone Corporation
- Michelin
- The Goodyear Tire & Rubber Company
- Delphi Technologies (BorgWarner Inc.)
- 3M Company
- Tenneco Inc.
- Federal-Mogul
- Valeo SA
- Hella KGaA Hueck & Co.
- Schaeffler AG
- Magneti Marelli
- Cooper Tire & Rubber Company
- Gates Corporation
- Brembo S.p.A.
Frequently Asked Questions
What is the current size of the global automotive aftermarket?
The global automotive aftermarket is estimated to be valued at USD 498.4 Billion in 2025 and is projected to reach USD 785.6 Billion by 2034, growing at a CAGR of 5.2%.
Which region is expected to grow the fastest during the forecast period?
Asia Pacific is expected to be the fastest-growing region, fueled by the expanding vehicle parc in China and India and an increasing focus on organized vehicle service centers.
How is the transition to electric vehicles affecting the aftermarket?
While EVs require less frequent maintenance for traditional mechanical components, they are creating new high-value opportunities in battery management, thermal cooling, and advanced electronics segments.
What role does e-commerce play in the automotive aftermarket?
E-commerce is revolutionizing the industry by providing better price transparency, a wider range of SKUs, and more efficient logistics, particularly in the B2B segment where workshops order parts for just-in-time delivery.
Who are the leading companies in the automotive aftermarket sector?
The market is led by major global suppliers including Robert Bosch GmbH, Continental AG, Denso Corporation, ZF Friedrichshafen, and Michelin, among other specialized parts manufacturers.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
