Aircraft Mounts Market
Aircraft Mounts Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711946 | Published On : November 22, 2026 |
Format : 


 | Author : Ashraf Shehata
Aircraft Mounts Market Size
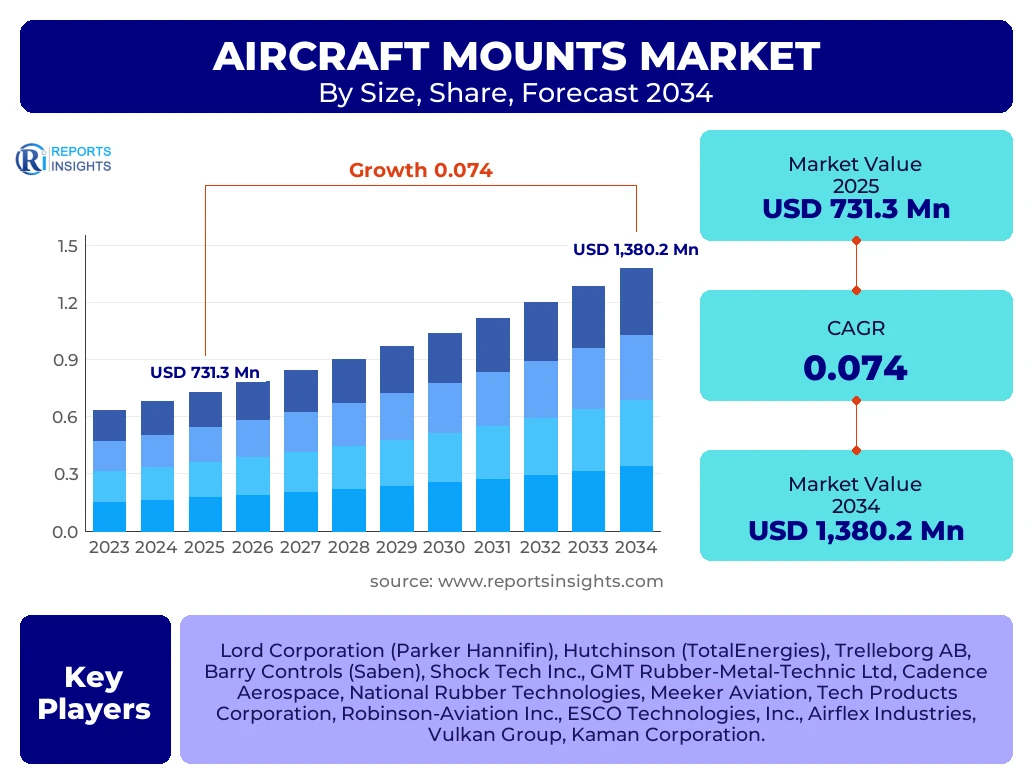
According to Reports Insights Consulting Pvt Ltd, The Aircraft Mounts Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.4% between 2025 and 2034. The market is estimated at USD 785.4 Million in 2026 and is projected to reach USD 1,380.2 Million by the end of the forecast period in 2034.
Key Aircraft Mounts Market Trends & Insights
The aircraft mounts market is currently undergoing a significant technological shift, primarily driven by the aviation industry's relentless pursuit of fuel efficiency and noise reduction. Market research indicates that the integration of advanced damping materials, such as high-performance elastomers and carbon-fiber composites, is becoming a standard in new-generation aircraft. Regional insights suggest that the Asia-Pacific region is experiencing the highest growth due to a surge in low-cost carrier (LCC) fleets and indigenous aircraft manufacturing programs in China and India. Meanwhile, North America maintains the largest market share, anchored by a robust defense sector and the presence of major aerospace OEMs. Competitive benchmarking reveals that leading players are increasingly focusing on active vibration control systems (AVCS) to replace traditional passive mounts, offering superior comfort for passengers and enhanced protection for sensitive avionics equipment.
- Largest Region: North America remains the dominant market owing to high aircraft production rates and extensive MRO (Maintenance, Repair, and Overhaul) activities.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR due to rapid urbanization, increasing air passenger traffic, and significant investments in defense aviation.
- Largest Segment by Share: The Engine Mounts segment holds the largest market share, necessitated by the critical requirement to isolate high-frequency engine vibrations from the airframe.
- Emerging Material Trend: There is a notable transition from traditional steel and aluminum mounts to lightweight, corrosion-resistant alloys and composite materials to meet stringent weight-reduction targets.
Key Takeaways Aircraft Mounts Market Size & Forecast
Analysis of market dynamics and user queries reveals a critical focus on the lifecycle management of aircraft mounts. Stakeholders are increasingly concerned with the durability and maintenance intervals of vibration isolators, which directly impact aircraft downtime and operational costs. The forecast suggests that the aftermarket segment will witness substantial growth as aging commercial fleets require frequent replacement of mounts to ensure structural integrity. Furthermore, the rise of Electric Vertical Takeoff and Landing (eVTOL) aircraft presents a nascent but high-potential opportunity for specialized mounting solutions designed for electric propulsion systems.
- Dominant Country: The United States leads the global market, supported by the presence of major industry players and a massive fleet of both commercial and military aircraft.
- Strategic Focus: Manufacturers are prioritizing the development of multi-axis vibration isolation systems to cater to the complex dynamic environments of modern rotorcraft and tilt-rotor aircraft.
- Inventory Growth: The increasing delivery of narrow-body aircraft, particularly for short-haul domestic routes, is a primary driver for the volume of aircraft mounts produced globally.
- Regulatory Influence: Stringent FAA and EASA safety certifications regarding fire-smoke-toxicity (FST) compliance for interior mounts are shaping material selection strategies among suppliers.
Aircraft Mounts Market Drivers Analysis
The fundamental growth of the aircraft mounts market is fueled by the expansion of the global commercial aviation fleet and the modernization of military aircraft. As global air travel demand returns to pre-pandemic trajectories, airlines are placing record-breaking orders for new-generation aircraft that require advanced mounting solutions for engines, APUs, and cabin interiors. Additionally, the increasing complexity of airborne electronic systems necessitates sophisticated vibration isolation to prevent hardware failure and maintain operational readiness.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Demand for Narrow-Body Aircraft | +2.1% | Global (High in Asia-Pacific) | 2025–2034 |
| Advancements in Vibration Damping Technology | +1.8% | North America and Europe | 2026–2030 |
| Expansion of Defense Budgets | +1.5% | USA, China, India, Poland | 2025–2034 |
| Growing Aftermarket and MRO Services | +1.2% | Global (High in Middle East) | 2025–2034 |
Aircraft Mounts Market Restraints Analysis
Despite positive growth indicators, the market faces significant restraints, including the high cost of raw materials and the complexity of certification processes. The aerospace industry operates under zero-tolerance safety standards, meaning any new mount design must undergo years of rigorous testing before reaching the market. Furthermore, volatility in the supply of aerospace-grade titanium and specialized elastomers can disrupt production timelines and increase costs for manufacturers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Regulatory and Safety Certifications | -0.8% | Europe and North America | Ongoing |
| Volatility in Raw Material Prices | -0.6% | Global | 2025–2028 |
| High Initial Design and R&D Costs | -0.5% | Global | 2025–2034 |
Aircraft Mounts Market Opportunities Analysis
The emergence of Urban Air Mobility (UAM) and the development of hydrogen-powered aircraft present transformative opportunities for the aircraft mounts sector. These new platforms require unique vibration profiles and thermal management solutions that differ significantly from traditional combustion engine aircraft. Companies that can pioneer lightweight, high-performance mounts for electric motors and cryogenic fuel tanks will likely secure a competitive advantage in the coming decade.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Growth in Electric and Hybrid Propulsion | +1.4% | Europe and USA | 2028–2034 |
| Adoption of 3D Printing for Custom Mounts | +0.9% | Global | 2026–2034 |
| Development of Smart/Active Mounts | +1.1% | North America | 2027–2034 |
Aircraft Mounts Market Challenges Impact Analysis
One of the primary challenges in the aircraft mounts market is the supply chain fragmentation that persists following global economic shifts. Ensuring a steady supply of high-purity metals and chemical precursors for elastomers is a constant struggle for mid-tier suppliers. Additionally, the rapid pace of aircraft design evolution requires mount manufacturers to be highly agile, often needing to provide customized solutions within shortened development cycles while maintaining cost-competitiveness.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Disruptions and Lead Times | -0.7% | Global | 2025–2027 |
| Integrating Active Systems into Legacy Airframes | -0.4% | Global | 2025–2030 |
Aircraft Mounts Market - Updated Report Scope
This report provides a granular analysis of the global aircraft mounts market, encompassing various mount types, materials, and end-user applications across both commercial and military sectors. It evaluates the impact of macroeconomic factors, technological breakthroughs, and regulatory changes on market growth from 2025 to 2034. The scope includes detailed competitive landscape mapping and strategic recommendations for market participants looking to capitalize on emerging aerospace trends.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 731.3 Million |
| Market Forecast in 2034 | USD 1,380.2 Million |
| Growth Rate | 7.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Lord Corporation (Parker Hannifin), Hutchinson (TotalEnergies), Trelleborg AB, Barry Controls (Saben), Shock Tech Inc., GMT Rubber-Metal-Technic Ltd, Cadence Aerospace, National Rubber Technologies, Meeker Aviation, Tech Products Corporation, Robinson-Aviation Inc., ESCO Technologies, Inc., Airflex Industries, Vulkan Group, Kaman Corporation. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The aircraft mounts market is segmented into several critical categories based on technical requirements and installation locations. Engine mounts represent the most technically demanding segment, requiring materials capable of withstanding extreme temperatures and constant cyclic loading. Interior mounts, while less demanding in terms of load, are subject to strict aesthetics and safety regulations regarding cabin air quality and fire retardation. The aftermarket segment is a significant revenue generator, as mounts are considered wear-and-tear components that must be replaced during scheduled heavy maintenance checks (C-checks and D-checks).
- By Mount Type: Engine Mounts, APU Mounts, Avionics Mounts, Interior Mounts, Landing Gear Mounts, Weapon Mounts (Military).
- By Material Type: High-grade Steel, Lightweight Aluminum Alloys, Titanium Alloys, Synthetic Rubber, Polymer Composites.
- By Aircraft Category: Narrow-body Aircraft, Wide-body Aircraft, Very Large Aircraft, Regional Transport Aircraft, Business Jets, Fighter Jets, Military Transports, Rotary-wing Aircraft (Helicopters), UAVs.
- By Sales Channel: Original Equipment Manufacturer (OEM) and Maintenance, Repair, and Overhaul (MRO/Aftermarket).
Regional Highlights
- North America: The largest market globally, driven by the presence of major aerospace giants like Boeing and Lockheed Martin. The region also hosts the world's most extensive fleet of general aviation and military aircraft, ensuring steady demand for both OEM and aftermarket mounts.
- Europe: A key hub for innovation, with Airbus driving significant demand for narrow-body aircraft mounts. The region is at the forefront of implementing environmental regulations that favor lightweight and sustainable materials in aircraft components.
- Asia-Pacific: The fastest-growing region, fueled by the rapid expansion of air travel in China, India, and Southeast Asia. Local manufacturing initiatives, such as the COMAC C919, are creating new supply chain opportunities for regional mount manufacturers.
- Middle East: Demand is primarily driven by the large wide-body fleets of major carriers like Emirates and Qatar Airways, which require specialized high-performance mounts for long-haul operations in hot and sandy environments.
- Latin America & MEA: These regions show steady growth in the military aviation and general aviation sectors, with increasing investments in regional connectivity projects.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Aircraft Mounts Market.- Lord Corporation (Parker Hannifin)
- Hutchinson (TotalEnergies)
- Trelleborg AB
- Barry Controls
- Shock Tech Inc.
- GMT Rubber-Metal-Technic Ltd
- Cadence Aerospace
- National Rubber Technologies
- Meeker Aviation
- Tech Products Corporation
- Robinson-Aviation Inc.
- ESCO Technologies, Inc.
- Airflex Industries
- Vulkan Group
- Kaman Corporation
- Meggitt PLC
- Skandia, Inc.
- Dura-Bar
- Aeroflex
- Vibration Management Corporation
Frequently Asked Questions
Analyze common user questions about the Aircraft Mounts market and generate a concise list of summarized FAQs reflecting key topics and concerns.What are the primary functions of aircraft mounts in modern aviation?
Aircraft mounts serve the critical role of securing major components such as engines, APUs, and avionics to the airframe while simultaneously isolating and damping vibrations and noise. This protects the aircraft structure from fatigue, ensures the longevity of sensitive electronic systems, and enhances passenger comfort by reducing cabin noise levels.
Why is there a shift toward composite materials in aircraft mount manufacturing?
The shift is primarily driven by the industry's focus on weight reduction and fuel efficiency. Composite materials offer a superior strength-to-weight ratio compared to traditional metals, are naturally resistant to corrosion, and provide excellent inherent damping properties, which can simplify the design of vibration isolation systems.
How does the growth of the UAV market affect the aircraft mounts industry?
The UAV (Unmanned Aerial Vehicle) sector is a significant growth catalyst. Drones require specialized, miniature mounting solutions for high-resolution cameras, sensors, and communication equipment to ensure stability and data accuracy during flight. This has opened a new segment for manufacturers to develop lightweight, high-precision mounts.
Which aircraft type is expected to dominate the market share during the forecast period?
Narrow-body aircraft are expected to dominate the market share. This is due to the high volume of deliveries in this category, driven by the expansion of low-cost carriers globally and the replacement of older fleets with more fuel-efficient models like the Boeing 737 MAX and Airbus A320neo families.
What role do active vibration control systems (AVCS) play in the future of the market?
AVCS represents the next generation of aircraft mounting technology. Unlike passive mounts, active systems use sensors and actuators to generate "counter-vibrations" that cancel out mechanical noise and oscillation in real-time. This technology is increasingly being adopted in premium business jets and helicopters to provide an ultra-quiet cabin environment.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
