Wool Market
Wool Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711579 | Published On : November 07, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Wool Market Size
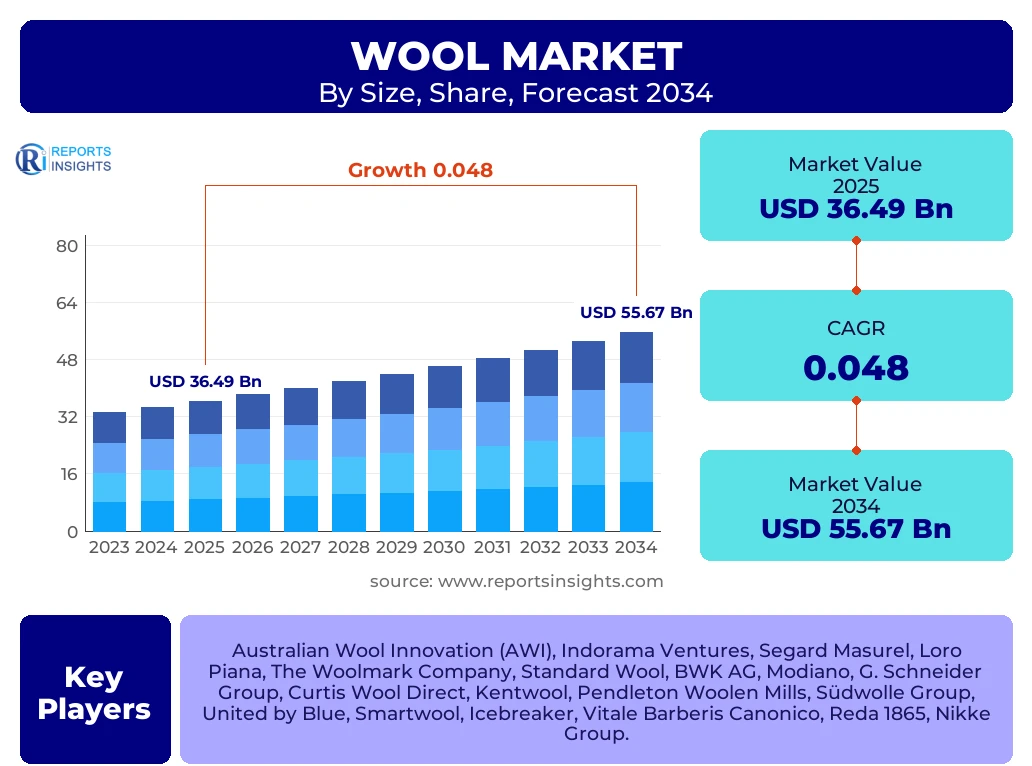
According to Reports Insights Consulting Pvt Ltd, The Wool Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 4.8% between 2025 and 2034. The market is estimated at USD 38.24 Billion in 2026 and is projected to reach USD 55.67 Billion by the end of the forecast period in 2034.
The global wool market is currently navigating a transformative era characterized by a significant shift toward high-value, sustainable fibers. This growth is fundamentally underpinned by the rising consumer preference for natural, biodegradable materials in the face of escalating environmental concerns regarding microplastic pollution from synthetic textiles. As the premiumization of the textile industry continues, wool—particularly fine Merino wool—has transitioned from being a seasonal staple to a year-round performance fiber, widely integrated into luxury apparel, high-performance activewear, and sustainable home furnishings. The market's expansion is further supported by technological advancements in wool processing, which have enhanced the fiber's versatility, making it softer, machine-washable, and more durable for modern lifestyle requirements.
Structurally, the market is benefiting from a robust recovery in global supply chains and a resurgence in demand from key economies such as China, India, and the European Union. Strategic investments in animal welfare standards and regenerative farming practices are also playing a crucial role in securing the long-term viability of the wool industry. These initiatives are not only improving the quality of the wool produced but are also aligning the industry with the environmental, social, and governance (ESG) goals of major global retail brands. Consequently, the projected CAGR reflects a steady and resilient growth trajectory, driven by both traditional applications and innovative new use cases in technical textiles and medical applications.
Key Wool Market Trends & Insights
The contemporary wool market is defined by a rigorous focus on traceability and the "circular economy" model, where transparency from farm to fashion is no longer optional but a baseline requirement for market entry. Consumers are increasingly utilizing digital platforms to verify the origins of their garments, leading to the widespread adoption of blockchain technology and digital product passports within the wool supply chain. Furthermore, the integration of wool into the "athleisure" and outdoor performance segments has broken the fiber's traditional winter-only cycle. By leveraging wool’s natural thermoregulation and moisture-wicking properties, manufacturers are successfully competing with synthetic alternatives in the sportswear domain, creating a consistent year-round demand profile that mitigates seasonal volatility.
- Largest Region: Asia Pacific remains the dominant regional market, fueled by China's massive processing capacity and the growing domestic consumption of luxury wool products in the region.
- Fastest Growing Region: North America is emerging as the fastest-growing market, driven by a surge in demand for sustainable activewear and high-performance outdoor gear.
- Leading Segment by Share: The Merino Wool segment holds the largest market share due to its superior softness and dominance in the high-end apparel and performance wear sectors.
- Strategic Trend: Regenerative agriculture is becoming a key differentiator, with brands offering price premiums for wool sourced from farms that actively improve soil health and biodiversity.
Key Takeaways Wool Market Size & Forecast
The long-term outlook for the wool market remains exceptionally positive, supported by the fiber's inherent alignment with the global sustainability movement. Market dynamics suggest that while traditional formal wear continues to provide a stable base, the real growth engine lies in the diversification of wool applications into non-traditional areas like footwear, interior acoustics, and eco-friendly insulation. The forecast period anticipates a narrowing of the price gap between premium wool and high-tech synthetics, as the externalized environmental costs of petroleum-based fibers begin to influence carbon taxation and consumer pricing. Investors and stakeholders are increasingly viewing wool as a strategic asset in the transition toward a more sustainable and less fossil-fuel-dependent textile industry.
- Market Resilience: Despite competition from low-cost synthetics, the wool market is projected to maintain a consistent CAGR of 4.8%, buoyed by luxury demand.
- Apparel Dominance: The apparel industry remains the primary revenue contributor, accounting for over 60% of total market value throughout the forecast period.
- China’s Central Role: China continues to be the world’s leading importer of greasy wool and the largest exporter of finished wool textiles.
- Sustainability Premium: Certified sustainable wool (such as RWS or ZQRX) is expected to fetch a 15-20% price premium over conventional wool by 2034.
- Innovation in Blends: The development of wool-Tencel and wool-hemp blends is opening new market niches in the casual and summer-wear categories.
Wool Market Drivers Analysis
The primary catalysts for the wool market involve a blend of consumer behavioral shifts and industrial innovation. The "Slow Fashion" movement is perhaps the most significant driver, encouraging consumers to invest in high-quality, long-lasting garments rather than disposable items. Additionally, the inherent functional properties of wool—flame resistance, odor suppression, and breathability—are making it a preferred choice in the burgeoning technical textiles market, including automotive interiors and protective clothing.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shift Toward Sustainable & Natural Fibers | +1.5% | Global (Strongest in Europe) | 2025–2034 |
| Growth of Performance Athleisure | +1.2% | North America & APAC | 2026–2032 |
| Expansion of Luxury Retail in Emerging Markets | +0.9% | China, India, Brazil | 2025–2030 |
| Advancements in Wool Processing Tech | +0.7% | Italy, Germany, Japan | 2027–2034 |
Wool Market Restraints Analysis
The wool industry faces several structural headwinds, most notably the high cost of production compared to synthetic alternatives like polyester and acrylic. Sheep farming is labor-intensive and subject to the complexities of land management and animal health. Furthermore, the volatility in greasy wool prices can pose a significant challenge for textile manufacturers trying to maintain stable margins, often leading to a temporary shift toward fiber blending to mitigate financial risk.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition from Low-Cost Synthetics | -1.1% | Global | Continuous |
| High Production & Labor Costs | -0.8% | Australia, New Zealand | 2025–2029 |
| Stringent Animal Welfare Regulations | -0.5% | European Union | 2025–2034 |
Wool Market Opportunities Analysis
Future growth opportunities are concentrated in the circular economy and high-tech applications. Recycled wool is gaining significant traction as brands seek to reduce their carbon footprint, providing a new revenue stream for the "shoddy" (reprocessed wool) industry. Moreover, the biomedical sector is exploring the use of keratin derived from wool for wound healing and tissue engineering, representing a high-value frontier for the industry that moves beyond traditional textiles.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Recycled and Upcycled Wool Products | +1.4% | Europe & North America | 2026–2034 |
| Wool-Based Technical & Medical Textiles | +0.8% | USA, Japan, Germany | 2028–2034 |
| E-commerce Expansion for Bespoke Woolen Goods | +0.6% | Global | 2025–2030 |
Wool Market Challenges Impact Analysis
Climate change remains the most pressing challenge, as shifting weather patterns and prolonged droughts in major producing regions like Australia and South Africa directly impact flock sizes and fiber quality. Additionally, the industry must overcome the negative perceptions regarding the carbon footprint of livestock, requiring scientific validation of the carbon sequestration potential of well-managed grazing lands to satisfy increasingly critical environmental regulators.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Climate Change & Drought Conditions | -1.2% | Australia, South Africa | Continuous |
| Environmental Scrutiny of Methane Emissions | -0.7% | New Zealand, UK | 2025–2034 |
| Logistical Bottlenecks in Supply Chains | -0.4% | Global Trade Routes | 2025–2027 |
Wool Market - Updated Report Scope
This report provides a comprehensive examination of the global wool industry, covering the entire value chain from raw fiber production to end-user applications. It includes detailed quantitative analysis of market size, growth projections, and competitive positioning. The scope extends to analyzing the impact of global trade policies, environmental regulations, and consumer lifestyle trends on market dynamics across six major geographical regions.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 36.49 Billion |
| Market Forecast in 2034 | USD 55.67 Billion |
| Growth Rate | 4.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Australian Wool Innovation (AWI), Indorama Ventures, Segard Masurel, Loro Piana, The Woolmark Company, Standard Wool, BWK AG, Modiano, G. Schneider Group, Curtis Wool Direct, Kentwool, Pendleton Woolen Mills, Südwolle Group, United by Blue, Smartwool, Icebreaker, Vitale Barberis Canonico, Reda 1865, Nikke Group. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The wool market is segmented based on fiber type, source, and end-use application, each exhibiting distinct growth characteristics. The Merino Wool segment remains the most significant in terms of value, driven by its unparalleled softness and its status as the fiber of choice for luxury and athletic brands. Crossbred wool, while typically lower in price, finds extensive use in the interior textiles and flooring sectors, where durability and bulk are prioritized. From a source perspective, sheep wool dominates the market, though specialty fibers like cashmere and mohair are seeing high growth in the ultra-luxury segment. Application-wise, the Apparel sector continues to lead, but the Technical Textiles segment is projected to grow at the fastest rate due to wool’s natural fire-retardant and acoustic properties.
- By Type:
- Merino Wool (Premium Apparel)
- Crossbred Wool (Flooring and Blankets)
- Fine/Medium/Coarse Wool (Industrial and Home Use)
- By Source:
- Sheep (Mainstream production)
- Goat (High-value Cashmere and Mohair)
- Camelids (Alpaca, Llama for niche markets)
- By Application:
- Apparel (Outerwear, Suiting, Sportswear)
- Interior Textiles (Carpets, Rugs, Upholstery)
- Technical Textiles (Acoustic Insulation, Thermal Liners)
- Medical Textiles (Wound Care, Orthopedics)
Regional Highlights
- Asia Pacific: Holds the largest market share (over 40%), acting as the primary global hub for wool processing and manufacturing. China is the dominant player, while India is emerging as a significant consumer of wool-based home textiles.
- North America: Identified as the fastest-growing region. This is driven by a massive cultural shift toward "outdoor lifestyle" brands and a high concentration of premium activewear companies focusing on sustainable materials.
- Europe: The global center for luxury wool processing. Italy remains the world leader in high-end wool spinning and weaving (Biella region), while the UK and France are key markets for premium wool apparel and interior design.
- Australia and New Zealand: These remain the primary supply-side powerhouses, producing the vast majority of the world’s fine apparel-grade wool. Their market relevance is tied to the export of greasy wool and the setting of global quality benchmarks.
- Middle East & Africa: A growing market for technical wool used in construction and high-end carpets, with South Africa maintaining its position as a key producer of fine wool and mohair.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Wool Market.- Australian Wool Innovation (AWI)
- Indorama Ventures (Through wool processing acquisitions)
- Segard Masurel
- Loro Piana (LVMH Group)
- The Woolmark Company
- Standard Wool
- BWK AG (Bremer Woll-Kämmerei)
- Modiano S.A.
- G. Schneider Group
- Curtis Wool Direct
- Kentwool
- Pendleton Woolen Mills
- Südwolle Group
- United by Blue
- Smartwool (VF Corporation)
- Icebreaker (VF Corporation)
- Vitale Barberis Canonico
- Reda 1865
- Nikke Group (The Nippon-Keori Kaisha, Ltd.)
- Dormeuil
Frequently Asked Questions
What is driving the growth of the wool market in the apparel sector?
The growth is primarily driven by the "activewear" and "athleisure" trends, where wool's natural breathability, odor resistance, and moisture management are preferred over synthetic fibers. Additionally, the shift toward sustainable "slow fashion" encourages consumers to choose durable, natural fibers like wool over fast-fashion alternatives.
Which country is the largest producer of raw wool?
Australia is the world's leading producer of raw wool, particularly high-quality fine Merino wool used in the global apparel industry. It accounts for a significant portion of the global greasy wool exports, followed by countries like New Zealand and South Africa.
How does the wool market contribute to the circular economy?
Wool is a 100% natural, renewable, and biodegradable fiber. It is also one of the most recycled textile fibers in the world. The industry contributes to the circular economy through high rates of reuse and the mechanical recycling of old woolen garments into new products, known as the "closed-loop" textile system.
What are the main challenges facing wool producers today?
Producers face significant challenges from climate change, including water scarcity and heat stress for livestock. Additionally, rising labor costs for shearing and the high cost of meeting international animal welfare and environmental certifications (like RWS) impact producer margins.
What is the future outlook for technical wool applications?
The outlook for technical wool is highly positive, with significant expansion expected in acoustic insulation, automotive interiors, and protective industrial wear. Wool’s natural flame retardancy and thermal regulation make it an ideal, sustainable alternative to synthetic technical textiles.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
