Wood Fencing Market
Wood Fencing Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711645 | Published On : November 10, 2026 |
Format : 


 | Author : Jonathan Sikka
Wood Fencing Market Size
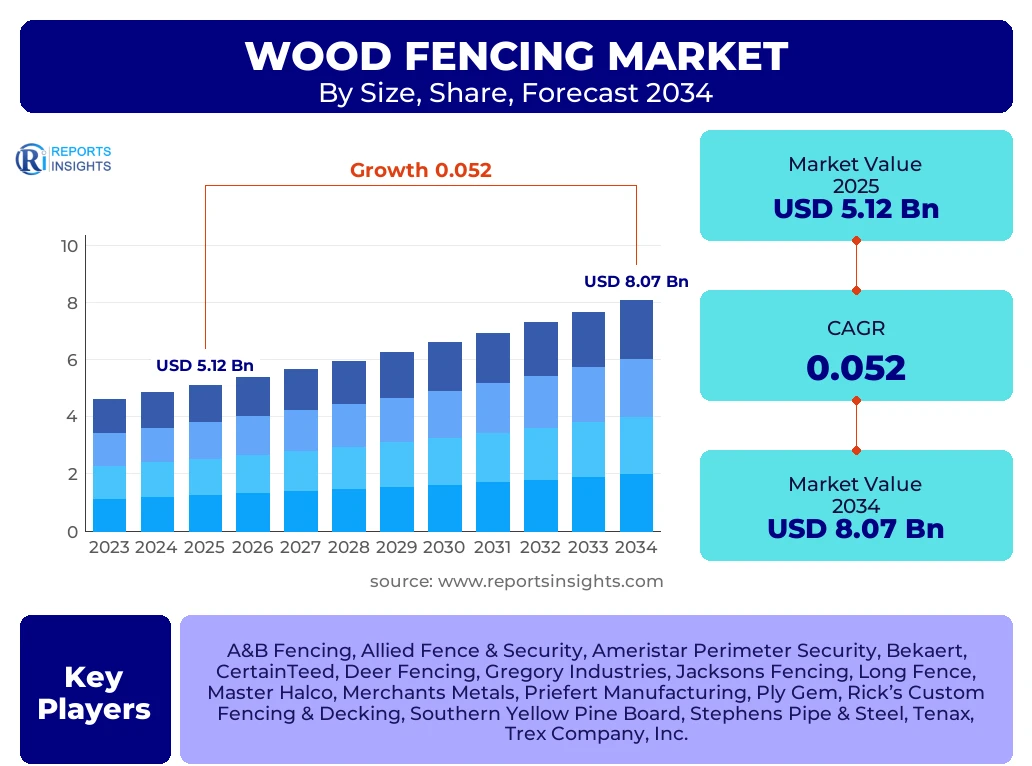
According to Reports Insights Consulting Pvt Ltd, The Wood Fencing Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.2% between 2025 and 2034. The market is estimated at USD 5.38 Billion in 2026 and is projected to reach USD 8.07 Billion by the end of the forecast period in 2034.
Key Wood Fencing Market Trends & Insights
The global wood fencing landscape is undergoing a significant transformation driven by the dual pillars of aesthetic personalization and sustainable material innovation. Stakeholders are increasingly prioritizing longevity and environmental stewardship, leading to a surge in demand for thermally modified timber and ethically sourced hardwoods. Research indicates that the integration of wood fencing with modern architectural styles, such as horizontal slat designs and mixed-material installations, is redefining curb appeal in the residential sector. Furthermore, the market is seeing a localized shift toward domestic timber supplies to mitigate the risks associated with global supply chain volatility and fluctuating lumber prices.
- Largest Region: North America remains the dominant market shareholder, driven by a deep-rooted culture of suburban residential ownership and extensive agricultural land use.
- Fastest Growing Region: Asia Pacific is anticipated to exhibit the highest CAGR due to rapid urbanization, increasing middle-class disposable income, and expanding commercial infrastructure in emerging economies.
- Largest Segment by Type: Privacy fencing continues to hold the largest market share as homeowners prioritize secluded outdoor living spaces in increasingly dense suburban developments.
- Key Material Trend: Pressure-treated pine and cedar maintain a lead in volume, while thermally modified wood is the fastest-growing niche segment due to its superior rot resistance and chemical-free processing.
Key Takeaways Wood Fencing Market Size & Forecast
The trajectory of the wood fencing market suggests a steady upward momentum, anchored by the resilient home improvement and renovation sector. Analysis of consumer behavior reveals that while initial costs are a factor, the long-term ROI of premium wood species—known for their natural beauty and durability—is becoming a primary selling point. The forecast period will likely see a professionalization of the installation sector, where integrated service providers offer end-to-end solutions from design to maintenance, addressing the historically fragmented nature of the fencing industry. Digital marketplaces are also streamlining the procurement of fencing materials, making specialized wood types more accessible to the DIY segment.
- Residential Dominance: The residential sector accounts for over 65% of the total market value, sustained by a robust pipeline of new housing starts and remodeling activities.
- Sustainable Forestry: Certification standards like FSC (Forest Stewardship Council) and PEFC are no longer optional but are becoming essential for market entry in European and North American territories.
- Lumber Pricing Resilience: Despite historical price spikes, wood remains the preferred material over vinyl or metal for its organic aesthetic and ease of customization.
- Innovation in Preservatives: The development of eco-friendly, non-toxic wood preservatives is expanding the application of wood fencing in organic farming and pet-friendly residential environments.
Wood Fencing Market Drivers Analysis
The growth of the wood fencing market is primarily fueled by the expansion of the global construction industry and a renewed consumer focus on outdoor living. As urban sprawl continues, the need for boundary definition and security becomes paramount. Additionally, the psychological shift toward "nesting" and improving existing home equity has led to a sustained boom in the landscaping and perimeter security sectors. Government initiatives promoting green building materials also favor wood as a renewable resource compared to petroleum-based alternatives.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Home Renovation and Remodeling Spending | +1.8% | United States, Canada, Germany | 2025 - 2030 |
| Rapid Urbanization and Residential Expansion | +1.5% | India, China, Southeast Asia | 2026 - 2034 |
| Preference for Sustainable and Biodegradable Materials | +1.1% | European Union, UK | 2025 - 2034 |
| Expansion of Agricultural and Livestock Sectors | +0.8% | Brazil, Australia, USA | 2027 - 2032 |
Wood Fencing Market Restraints Analysis
While the market is growing, it faces headwinds from the increasing popularity of low-maintenance alternatives such as Vinyl (PVC) and Composite fencing. Wood requires periodic staining, sealing, and treatment to prevent rot, warping, and insect infestation, which adds to the total cost of ownership. Furthermore, the industry is highly sensitive to the volatility of raw timber prices, which can fluctuate wildly based on trade policies, forest fire seasons, and logging regulations.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Maintenance Requirements and Long-term Costs | -1.2% | Global | 2025 - 2034 |
| Competition from Synthetic and Composite Alternatives | -1.5% | North America, Western Europe | 2026 - 2034 |
| Fluctuations in Raw Timber and Lumber Prices | -0.9% | Global (Import-heavy regions) | 2025 - 2028 |
Wood Fencing Market Opportunities Analysis
There is a significant opportunity for market players to diversify into value-added segments such as thermally modified wood and "smart fences" that integrate lighting and security sensors. The growing trend of "Do-It-For-Me" (DIFM) services provides a platform for manufacturers to partner with professional installation networks. Additionally, the luxury market for exotic, sustainably sourced hardwoods remains underserved, offering high-margin possibilities for specialized retailers and exporters.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Thermally Modified Timber (TMT) | +2.2% | Scandinavia, Northern Europe, Canada | 2026 - 2034 |
| Integration of Smart Security and IoT Lighting | +1.4% | Smart Cities, High-end Residential | 2028 - 2034 |
| Expansion into Emerging Markets with Low Cost Sourcing | +1.7% | Southeast Asia, Latin America | 2025 - 2034 |
Wood Fencing Market Challenges Impact Analysis
The primary challenge lies in balancing environmental conservation with the industrial demand for lumber. Deforestation concerns and tightening logging quotas in key exporting regions like the Amazon and parts of Southeast Asia create supply bottlenecks. Moreover, the shortage of skilled labor for professional fence installation is driving up project costs and leading to longer lead times, which may deter potential customers from initiating new projects.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Labor Shortages in Skilled Carpentry/Installation | -1.0% | USA, UK, Australia | 2025 - 2030 |
| Environmental Regulations and Logging Restrictions | -1.3% | Brazil, Indonesia, Russia | 2025 - 2034 |
| Logistics and Supply Chain Disruptions | -0.7% | International Trade Routes | 2025 - 2027 |
Wood Fencing Market - Updated Report Scope
The scope of this report encompasses a granular analysis of the global wood fencing ecosystem, covering the entire value chain from timber harvesting and processing to retail distribution and end-user installation. It provides a detailed assessment of material science innovations, competitive positioning, and the regulatory landscape governing forest products. The report focuses on providing actionable intelligence for manufacturers, distributors, and investors looking to capitalize on the shifting dynamics of the perimeter security and decorative landscaping markets.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 5.12 Billion |
| Market Forecast in 2034 | USD 8.07 Billion |
| Growth Rate | 5.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | A&B Fencing, Allied Fence & Security, Ameristar Perimeter Security, Bekaert, CertainTeed, Deer Fencing, Gregory Industries, Jacksons Fencing, Long Fence, Master Halco, Merchants Metals, Priefert Manufacturing, Ply Gem, Rick’s Custom Fencing & Decking, Southern Yellow Pine Board, Stephens Pipe & Steel, Tenax, Trex Company, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The wood fencing market is segmented primarily by material type and application, reflecting the diverse needs of the global consumer base. Residential applications dominate the volume, where aesthetic appeal and privacy are the primary drivers. Conversely, the agricultural segment focuses on utility and cost-effectiveness, favoring durable post-and-rail configurations. Material-wise, pressure-treated pine remains the workhorse of the industry due to its affordability, while cedar and redwood occupy the premium tier, valued for their natural oils that resist decay and their superior visual finish. The rise of composite wood is also bridging the gap between natural wood aesthetics and synthetic durability.
- By Material:
- Cedar (Western Red, Northern White)
- Pine (Pressure-Treated)
- Redwood
- Cypress
- Exotic Hardwoods (Ipe, Teak)
- By Type:
- Privacy (Solid Board, Shadowbox)
- Picket (Spaced, Scalloped)
- Post and Rail (Split Rail, Round Rail)
- Lattice and Decorative
- By Application:
- Residential (New Construction, Replacement)
- Commercial and Institutional
- Agricultural and Farming
- Industrial and Infrastructure
Regional Highlights
- North America: The largest market globally, characterized by high consumer spending on home improvement and a strong preference for large, private backyard spaces. The United States leads in the consumption of pressure-treated pine and Western Red Cedar.
- Europe: A mature market with a focus on high-quality, sustainable materials and strict environmental regulations. Countries like the UK, Germany, and France are seeing a shift toward modern horizontal fencing and lattice designs.
- Asia Pacific: The fastest-growing region, fueled by massive residential development in China and India. The commercial and agricultural sectors in Australia and New Zealand also contribute significantly to the regional demand for high-durability fencing.
- Latin America: Growth is driven by the agricultural sector, particularly in Brazil and Argentina, where post-and-rail fencing is essential for livestock management and land boundary definition.
- Middle East & Africa: Emerging demand in urban centers like Dubai and Riyadh for high-end residential communities, though the market is constrained by the extreme climate which requires specialized wood treatments.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Wood Fencing Market.- Master Halco
- Merchants Metals
- CertainTeed (Saint-Gobain)
- Ply Gem (Cornerstone Building Brands)
- Ameristar Perimeter Security (ASSA ABLOY)
- Jacksons Fencing
- Long Fence
- Rick’s Custom Fencing & Decking
- Stephens Pipe & Steel
- Gregory Industries
- Allied Fence & Security
- A&B Fencing
- Priefert Manufacturing
- Bekaert
- Southern Yellow Pine Board
- Trex Company, Inc.
- Tenax
- Deer Fencing
Frequently Asked Questions
What is the current market size of the global wood fencing industry?
The Wood Fencing Market is valued at USD 5.12 Billion in 2025 and is expected to grow steadily at a CAGR of 5.2%, reaching over USD 8 Billion by 2034.
Which wood species is most preferred for residential fencing?
Pressure-treated Pine is the most widely used due to its cost-effectiveness, while Western Red Cedar and Redwood are preferred for premium projects due to their natural rot resistance and aesthetic appeal.
How does wood fencing compare to vinyl (PVC) fencing in terms of market share?
Wood fencing still holds a significant majority of the market share due to its lower upfront cost and natural look, though vinyl is growing in the residential sector because of its zero-maintenance requirements.
What are the main growth drivers for the Asia Pacific wood fencing market?
Key drivers include rapid urbanization, the rise of gated residential communities, and the expansion of the agricultural sector in countries like India, China, and Australia.
Is sustainable sourcing a major factor in the wood fencing market?
Yes, sustainability is a critical factor, with increasing demand for FSC-certified wood and thermally modified timber as consumers and governments prioritize eco-friendly and renewable building materials.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
