Commercial HVAC Rooftop Units Market
Commercial HVAC Rooftop Units Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711532 | Published On : November 05, 2026 |
Format : 


 | Author : Jonathan Sikka
Commercial HVAC Rooftop Units Market Size
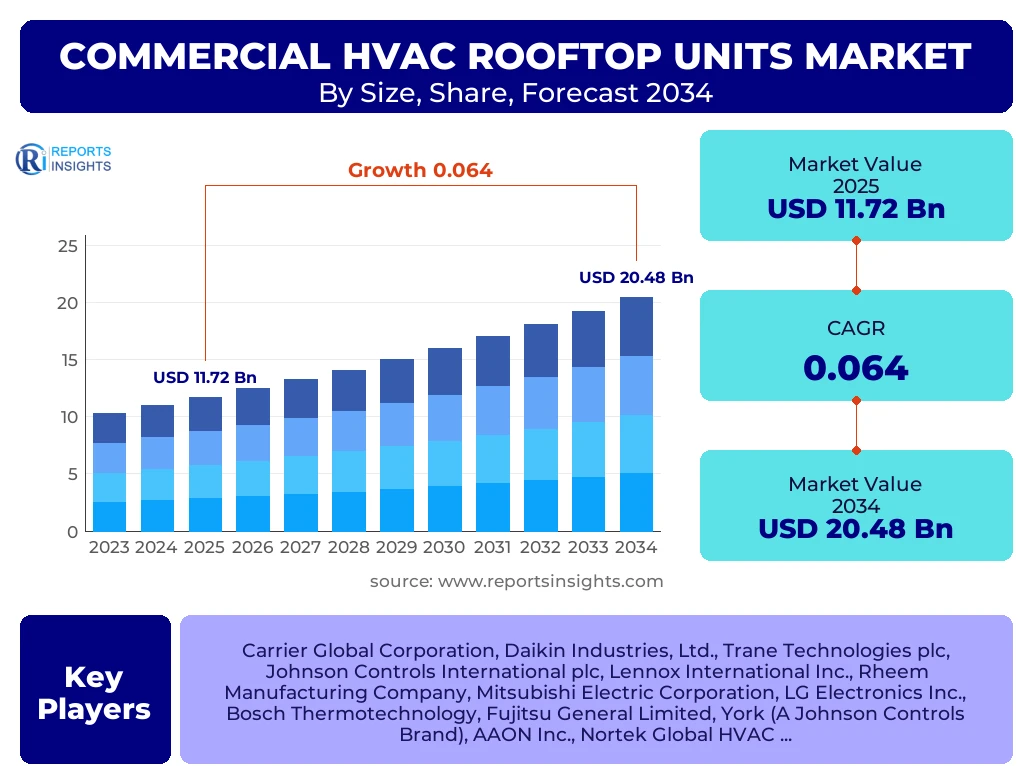
According to Reports Insights Consulting Pvt Ltd, The Commercial HVAC Rooftop Units Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.4% between 2025 and 2034. The market is estimated at USD 12.45 Billion in 2026 and is projected to reach USD 20.48 Billion by the end of the forecast period in 2034.
Key Commercial HVAC Rooftop Units Market Trends & Insights
The global landscape for commercial rooftop units is undergoing a significant transition driven by the dual imperatives of decarbonization and digital transformation. Modern commercial infrastructure is moving away from traditional fossil-fuel-based heating towards high-efficiency electrified solutions, such as cold-climate heat pump rooftop units (RTUs). This shift is heavily influenced by evolving building codes and corporate environmental, social, and governance (ESG) targets, which prioritize energy performance and carbon footprint reduction. Furthermore, the integration of advanced sensor arrays and cloud-based diagnostics is transforming RTUs from passive mechanical assets into intelligent, data-generating nodes within the broader Building Management System (BMS) ecosystem.
Competitive benchmarking reveals that leading manufacturers are increasingly focusing on modularity and "plug-and-play" installation designs to mitigate the rising costs of on-site labor. Regional insights suggest that while North America remains the largest market due to its extensive inventory of low-rise retail and office buildings, the Asia-Pacific region is experiencing the fastest growth, underpinned by rapid urbanization and the expansion of organized retail sectors. The market is also seeing a surge in demand for high-Indoor Air Quality (IAQ) features, such as HEPA filtration and UV-C sterilization modules, as facility managers prioritize occupant health in post-pandemic commercial environments.
- Largest Region: North America currently holds the highest market share, driven by a mature commercial real estate sector and high replacement rates for aging infrastructure.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR due to massive infrastructure investments in China, India, and Southeast Asia.
- Largest Segment by Capacity: The 5-15 Tons capacity segment remains the dominant share contributor, widely utilized in retail and mid-sized office applications.
- Key Technology Trend: Transition to low-GWP (Global Warming Potential) refrigerants like R-32 and R-454B in compliance with international environmental protocols.
- Leading Application: The retail sector continues to be the primary end-user, though the industrial and warehouse segment is growing rapidly due to the e-commerce boom.
Key Takeaways Commercial HVAC Rooftop Units Market Size & Forecast
The Commercial HVAC Rooftop Units market is entering a phase of sustained growth characterized by technological maturation and regulatory-driven replacement cycles. Analysts observe that the market's trajectory is no longer solely dependent on new construction starts but is increasingly bolstered by the "retrofit and replace" economy. As existing RTUs reach their 15-to-20-year lifespan, facility managers are opting for modern units that offer superior Integrated Energy Efficiency Ratio (IEER) ratings to offset rising utility costs. This trend is particularly pronounced in Western Europe and North America, where stringent efficiency standards like the SEER2 and DOE 2023 mandates have effectively raised the floor for minimum performance requirements.
- Market Growth Foundation: The transition from gas-fired heating to electric heat pumps is the single most significant factor driving value growth in the forecast period.
- Dominant Country: The United States represents the largest individual country market, supported by federal tax incentives like the Inflation Reduction Act (IRA).
- Segment Leadership: Service and maintenance contracts are becoming a high-margin revenue stream for OEMs, complementing hardware sales through predictive maintenance offerings.
- Forecast Stability: Despite macroeconomic fluctuations, the essential nature of climate control in sectors like healthcare and data centers ensures high market resilience.
- Innovation Focus: Variable Speed Drive (VSD) compressors and electronically commutated motors (ECM) are becoming standard features in premium and mid-range RTU models.
Commercial HVAC Rooftop Units Market Drivers Analysis
The growth of the commercial RTU market is fundamentally anchored in regulatory mandates and the global drive toward energy conservation. Governments worldwide are implementing stricter efficiency standards, such as the US Department of Energy's (DOE) tiered efficiency increases, which compel manufacturers to innovate and end-users to upgrade. Additionally, the rapid expansion of the logistics and warehousing sector, fueled by global e-commerce, has created a substantial new footprint requiring sophisticated rooftop climate control solutions. The economic appeal of RTUs, specifically their space-saving design and ease of maintenance, remains a primary driver for small-to-medium enterprise (SME) commercial buildings.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Electrification and Heat Pump Adoption | +1.8% | Europe and North America | 2025-2034 |
| E-commerce Driven Warehouse Expansion | +1.5% | Global / Asia-Pacific Focus | 2025-2030 |
| Strict Energy Efficiency Regulations (DOE/EU EcoDesign) | +1.2% | United States, Germany, France | 2025-2034 |
| Smart Building & IoT Integration | +0.9% | Developed Economies | 2026-2034 |
Commercial HVAC Rooftop Units Market Restraints Analysis
Despite robust growth prospects, the market faces significant headwinds from the rising cost of raw materials and the complexity of refrigerant transitions. The phase-out of R-410A in favor of mildly flammable (A2L) refrigerants requires extensive supply chain retooling and technician retraining, which can temporarily inflate costs. Furthermore, high interest rates in key markets have increased the cost of capital for large-scale commercial real estate projects, leading to delays in new installations and large-scale retrofit programs. The specialized nature of rooftop installations also faces a shortage of skilled HVAC technicians, which can bottleneck project timelines and increase labor expenses.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Refrigerant Transition Costs (A2L Compliance) | -0.7% | North America, European Union | 2025-2028 |
| Skilled Labor Shortages for Specialized Installation | -0.5% | Global | 2025-2034 |
| High Upfront Capital Requirements for Energy-Efficient Models | -0.4% | Middle East and Latin America | 2025-2027 |
Commercial HVAC Rooftop Units Market Opportunities Analysis
The convergence of artificial intelligence and mechanical engineering presents a major opportunity for market participants to offer "HVAC-as-a-Service" models. By leveraging real-time performance data, OEMs can move from transactional sales to long-term service agreements based on guaranteed uptime and energy savings. There is also a burgeoning opportunity in the "Cold Climate" heat pump segment, where recent technological breakthroughs allow RTUs to operate efficiently in sub-zero temperatures, opening up markets in Northern Europe, Canada, and the Northern US that were previously reliant on gas furnaces. Furthermore, the integration of solar-ready RTU platforms aligns with the growing commercial interest in onsite renewable energy generation.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Predictive Maintenance & AI-Driven Diagnostics | +1.4% | USA, Japan, South Korea | 2026-2034 |
| Cold Climate Heat Pump Technology | +1.1% | Canada, Northern Europe | 2025-2030 |
| Modular & Custom-Configured RTU Solutions | +0.8% | Middle East (Luxury Retail) | 2027-2034 |
Commercial HVAC Rooftop Units Market Challenges Impact Analysis
Supply chain volatility remains a persistent challenge, particularly concerning specialized electronic components and high-grade copper or aluminum required for heat exchangers. Geopolitical tensions can lead to sudden price spikes or lead-time extensions, disrupting the just-in-time delivery models common in the HVAC industry. Additionally, the increasing complexity of control systems means that interoperability between different brands and existing building automation systems is a recurring technical hurdle. Manufacturers must also navigate a fragmented regulatory landscape where different states or cities may have varying mandates regarding carbon emissions and equipment noise levels.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Instability for Semiconductors | -0.6% | Global Manufacturing Hubs | 2025-2026 |
| System Interoperability & Cybersecurity Risks | -0.3% | High-Tech Commercial Offices | 2026-2034 |
Commercial HVAC Rooftop Units Market - Updated Report Scope
This report provides a comprehensive examination of the global Commercial HVAC Rooftop Units industry, encompassing technological advancements, regulatory shifts, and competitive dynamics. It offers detailed volumetric and value-based forecasts, segmented by capacity, technology, and end-use vertical. The scope includes an in-depth analysis of the transition toward sustainable refrigerants and the impact of the Inflation Reduction Act on North American market dynamics. By analyzing over 500 data points across the six major geographic regions, the report equips stakeholders with the necessary intelligence to navigate the evolving commercial climate control landscape through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 11.72 Billion |
| Market Forecast in 2034 | USD 20.48 Billion |
| Growth Rate | 6.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Carrier Global Corporation, Daikin Industries, Ltd., Trane Technologies plc, Johnson Controls International plc, Lennox International Inc., Rheem Manufacturing Company, Mitsubishi Electric Corporation, LG Electronics Inc., Bosch Thermotechnology, Fujitsu General Limited, York (A Johnson Controls Brand), AAON Inc., Nortek Global HVAC, Allied Commercial, Haier Group, Samsung Electronics Co., Ltd., Panasonic Corporation |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Commercial HVAC Rooftop Units market is segmented based on technology, capacity, and end-use application to reflect the diverse requirements of modern commercial spaces. The capacity segment is particularly critical, as it determines the suitability of a unit for specific building footprints; for example, the 5-15 ton units are the workhorses of the standalone retail sector, while larger >25 ton units are tailored for industrial facilities and large shopping malls. The technology segment is currently seeing a rapid shift towards heat pump units, which are gaining market share from traditional gas/electric hybrid models in regions with aggressive carbon-reduction targets. Application-wise, the retrofit market is outperforming new construction in mature economies as the aging building stock is upgraded to meet modern efficiency standards.
- By Product Type:
- Gas/Electric Units: Traditional units utilizing gas for heating and electricity for cooling.
- Electric/Electric Units: Fully electric units primarily used in regions with moderate climates.
- Heat Pump RTUs: High-efficiency units capable of providing both heating and cooling through refrigerant reversal.
- Dual Fuel: Hybrid systems that switch between heat pump and gas heating for optimized performance.
- By Capacity:
- Under 5 Tons: Targeted at small retail shops and boutique offices.
- 5 to 15 Tons: The high-volume segment serving mid-sized commercial structures.
- 15 to 25 Tons: Ideal for medium-to-large box retail and educational facilities.
- Over 25 Tons: Heavy-duty units for large industrial and multi-story applications.
- By End-Use Sector:
- Retail: Includes shopping malls, standalone retailers, and grocery stores.
- Office Buildings: Corporate office parks and administrative centers.
- Healthcare: Hospitals and clinics requiring high filtration and reliability.
- Education: Schools and universities focusing on indoor air quality and efficiency.
- Hospitality: Hotels and convention centers.
- Warehousing & Industrial: High-ceiling logistics centers and manufacturing plants.
Regional Highlights
The regional distribution of the commercial HVAC RTU market is heavily influenced by climate conditions, energy costs, and local building regulations. North America currently dominates the global landscape, largely because the rooftop unit configuration is the standard architectural choice for the continent's vast inventory of single-story commercial buildings. In the United States, the replacement cycle is a major market engine, with approximately 70% of sales categorized as retrofits. Europe is the leading region for the adoption of low-GWP refrigerants and electrified heating, driven by the F-Gas regulation and the Green Deal, which incentivizes the transition away from natural gas.
- North America: Largest market share; driven by US commercial building density and federal efficiency tax credits.
- Asia-Pacific: Fastest-growing region; fueled by massive commercial development in Tier 2 and Tier 3 cities across China and India.
- Europe: Focus on high-efficiency and sustainability; leading in the adoption of heat pump RTU technology.
- Middle East & Africa: Significant demand for high-capacity units with advanced cooling capabilities for extreme ambient temperatures.
- Latin America: Emerging market with growth centered in Brazil and Mexico's expanding retail and industrial corridors.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Commercial HVAC Rooftop Units Market.- Carrier Global Corporation
- Daikin Industries, Ltd.
- Trane Technologies plc
- Johnson Controls International plc
- Lennox International Inc.
- Rheem Manufacturing Company
- Mitsubishi Electric Corporation
- LG Electronics Inc.
- Bosch Thermotechnology
- Fujitsu General Limited
- AAON Inc.
- Nortek Global HVAC
- Allied Commercial
- Haier Group
- Samsung Electronics Co., Ltd.
- Panasonic Corporation
- York (A Johnson Controls Brand)
- Modine Manufacturing Company
- Tane Water and Air
- Zamil Air Conditioners
Frequently Asked Questions
What is the primary factor driving the growth of the Commercial HVAC Rooftop Units market?
The primary driver is the global shift toward energy efficiency and decarbonization. Stricter government regulations (such as the DOE standards in the US) and the transition from fossil-fuel-based heating to electrified heat pumps are compelling facility managers to upgrade to modern, high-efficiency RTU systems.
How is the transition to low-GWP refrigerants affecting the market?
The phase-out of R-410A in favor of low-GWP alternatives like R-32 and R-454B is a major technical transition. While it ensures environmental compliance, it requires manufacturers to redesign equipment for A2L (mildly flammable) refrigerant safety and necessitates specialized training for service technicians.
Which capacity segment holds the largest share in the commercial RTU market?
The 5 to 15-ton capacity segment currently holds the largest market share. This range is the industry standard for most mid-sized commercial applications, including standalone retail stores, restaurants, and suburban office buildings, offering the best balance of cooling power and installation flexibility.
What role does IoT play in modern rooftop units?
IoT integration allows for real-time monitoring and predictive maintenance. Sensors within the RTU track performance metrics and alert facility managers to potential failures before they occur, significantly reducing downtime and optimizing energy consumption through cloud-based analytics.
Which region is expected to show the highest growth rate through 2034?
The Asia-Pacific region is projected to exhibit the highest CAGR. This is driven by rapid urbanization, the proliferation of large-scale shopping malls, and the expansion of the industrial sector in emerging economies like India, Vietnam, and Indonesia.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
