Workload Scheduling Automation Market
Workload Scheduling Automation Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711563 | Published On : November 06, 2026 |
Format : 


 | Author : Jonathan Sikka
Workload Scheduling Automation Market Size
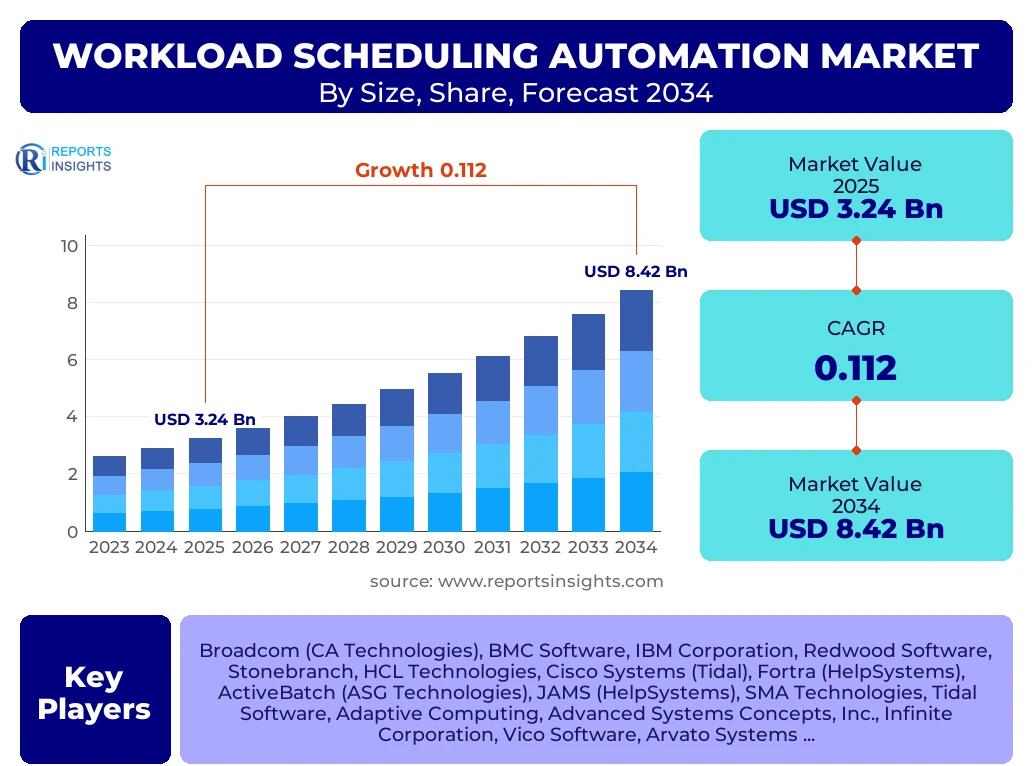
According to Reports Insights Consulting Pvt Ltd, The Workload Scheduling Automation Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 11.2% between 2025 and 2034. The market is estimated at USD 3.60 Billion in 2026 and is projected to reach USD 8.42 Billion by the end of the forecast period in 2034.
The global landscape for workload scheduling automation is undergoing a radical transformation as enterprises transition from traditional job scheduling to sophisticated service orchestration and automation platforms. This evolution is necessitated by the increasing complexity of hybrid and multi-cloud environments, where the seamless execution of data-intensive tasks is paramount for maintaining competitive advantage. Modern workload automation solutions are no longer confined to backend IT processes; they have become central to the delivery of real-time business services, integrating deeply with DevOps pipelines and big data ecosystems.
The acceleration of digital transformation initiatives across diverse industry verticals, including BFSI, healthcare, and retail, serves as a primary catalyst for market expansion. Organizations are increasingly prioritizing operational resilience and agility, seeking to eliminate manual intervention in repetitive tasks to mitigate human error and reduce operational expenditure. The integration of advanced analytics and machine learning within these platforms allows for predictive scheduling and proactive bottleneck identification, further enhancing the value proposition for large-scale enterprise deployments.
Key Workload Scheduling Automation Market Trends & Insights
The Workload Scheduling Automation market is characterized by a significant shift toward cloud-native architectures and the adoption of AI-driven orchestration. Enterprises are increasingly seeking unified platforms that can manage workloads across disparate environments—on-premises, public clouds, and edge locations—without creating operational silos. Current market dynamics indicate a strong preference for "Automation-as-a-Service" models, which provide the scalability required for fluctuating compute demands while ensuring robust security and compliance standards are maintained across the board.
- North America remains the largest regional market due to early adoption of cloud-native technologies and a high concentration of global enterprise headquarters.
- The Asia-Pacific region is the fastest-growing market, driven by rapid industrial digitalization in China, India, and Southeast Asia.
- The Cloud-based deployment segment holds the largest market share as organizations prioritize scalability and remote accessibility.
- AI-augmented automation is emerging as a dominant trend, enabling self-healing workflows and intelligent resource allocation.
- Vertical-specific automation solutions are gaining traction, particularly in BFSI for complex transaction processing and in Healthcare for data interoperability.
Key Takeaways Workload Scheduling Automation Market Size & Forecast
The forecast period from 2025 to 2034 reflects a robust trajectory for the workload scheduling automation market, underpinned by the necessity for hyper-automation in modern business environments. As data volumes continue to explode, the ability to orchestrate complex data pipelines and application workflows becomes a critical differentiator. Market insights suggest that the convergence of IT Operations and Development (DevOps) will continue to fuel demand for tools that support continuous integration and continuous delivery (CI/CD) while maintaining enterprise-grade governance.
- The United States leads the global market in terms of both technological innovation and total investment in automation infrastructure.
- The transition from legacy job schedulers to modern Service Orchestration and Automation Platforms (SOAP) is the primary driver for replacement cycles in large enterprises.
- Small and Medium-sized Enterprises (SMEs) are emerging as a high-growth segment due to the availability of cost-effective SaaS-based automation tools.
- Interoperability with Kubernetes and containerized environments has become a mandatory feature for market-leading workload scheduling solutions.
- The BFSI sector remains the leading end-user vertical, accounting for a significant portion of the total market value due to stringent regulatory requirements and high-volume processing needs.
Workload Scheduling Automation Market Drivers Analysis
The primary growth engines for this market revolve around the urgent need for operational efficiency and the management of heterogeneous IT environments. As businesses scale, the manual management of inter-dependent tasks becomes unsustainable, leading to a strategic pivot toward centralized automation frameworks that can bridge the gap between legacy systems and modern cloud applications.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shift to Hybrid and Multi-Cloud Orchestration | +3.2% | Global (Strong in NA & Europe) | 2025 - 2034 |
| Rising Demand for Big Data and Real-time Processing | +2.8% | APAC, North America | 2026 - 2032 |
| Need for Operational Cost Reduction and Error Mitigation | +2.5% | Global (Strong in EMEA) | 2025 - 2034 |
| Integration of AI/ML for Predictive Analytics | +2.7% | USA, China, Germany | 2027 - 2034 |
Workload Scheduling Automation Market Restraints Analysis
Despite the high growth potential, certain factors impede the seamless adoption of workload scheduling automation. The complexity of migrating legacy workflows and the high initial cost of enterprise-grade software often deter budget-conscious organizations, while a shortage of skilled personnel capable of managing complex automation scripts remains a persistent hurdle.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Implementation Costs and License Fees | -1.5% | Developing Economies (LAMEA) | 2025 - 2029 |
| Complexity in Integrating with Legacy Infrastructures | -1.2% | Europe, Japan | 2025 - 2030 |
| Security Concerns Over Automated Access Privileges | -0.8% | Global | 2026 - 2034 |
Workload Scheduling Automation Market Opportunities Analysis
The market presents significant opportunities for vendors who can innovate in the space of low-code/no-code automation and edge computing. As the Internet of Things (IoT) matures, the need to schedule and automate tasks at the network edge will open new revenue streams, particularly in manufacturing and smart city infrastructure projects.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into SME Segments via SaaS Models | +2.4% | India, Brazil, Southeast Asia | 2026 - 2034 |
| Edge Computing Task Orchestration | +1.9% | USA, South Korea, China | 2028 - 2034 |
| Low-Code Automation for Business Users | +2.1% | Global | 2025 - 2034 |
Workload Scheduling Automation Market Challenges Impact Analysis
Maintaining security and compliance across increasingly decentralized automated workflows is a significant challenge. Vendors must ensure that their platforms are resilient against cyber threats while providing the visibility required for audit trails in highly regulated sectors.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Maintaining Compliance in Global Hybrid Environments | -0.9% | European Union (GDPR Relevance) | 2025 - 2034 |
| Skills Gap in Advanced Automation Orchestration | -1.1% | Global | 2025 - 2030 |
Workload Scheduling Automation Market - Updated Report Scope
This report provides a comprehensive examination of the workload scheduling automation sector, offering detailed quantitative and qualitative analysis across various dimensions including technology adoption, regional trends, and competitive dynamics. It serves as a strategic roadmap for stakeholders to navigate the evolving IT automation landscape through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 3.24 Billion |
| Market Forecast in 2034 | USD 8.42 Billion |
| Growth Rate | 11.2% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Broadcom (CA Technologies), BMC Software, IBM Corporation, Redwood Software, Stonebranch, HCL Technologies, Cisco Systems (Tidal), Fortra (HelpSystems), ActiveBatch (ASG Technologies), JAMS (HelpSystems), SMA Technologies, Tidal Software, Adaptive Computing, Advanced Systems Concepts, Inc., Infinite Corporation, Vico Software, Arvato Systems, Rocket Software. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented to reflect the diverse needs of the modern enterprise, ranging from deployment preferences to specific industry requirements. The cloud segment is experiencing the most significant growth due to the flexibility it offers for modern distributed workforces. Large enterprises continue to dominate the market share as they possess the complex IT infrastructures that require centralized orchestration, though the SME segment is rapidly adopting SaaS-based models to streamline their growing digital operations.
- By Deployment Mode:
- Cloud-based: Dominates for scalability and cost-efficiency.
- On-Premise: Preferred by industries with extreme security requirements.
- Hybrid: Growing rapidly as a bridge between legacy and cloud.
- By Organization Size:
- Large Enterprises: Driving the demand for multi-platform orchestration.
- Small and Medium-Sized Enterprises: Adopting low-complexity, high-value tools.
- By Solution Component:
- Software: Includes core scheduling engines and management consoles.
- Services: Encompasses consulting, implementation, and managed automation support.
- By Industry Vertical:
- BFSI: Large volumes of batch processing and data reconciliation.
- IT & Telecommunications: Network automation and continuous delivery.
- Healthcare: Data integration for electronic health records.
- Retail: Supply chain and inventory management automation.
Regional Highlights
- North America: This region holds the largest market share, approximately 38% in 2025. This dominance is driven by the presence of major technology providers and a mature cloud ecosystem that encourages the early adoption of advanced IT automation.
- Asia-Pacific: Forecasted to be the fastest-growing region with a CAGR of over 13%. The primary drivers include the massive scale of digital transformation in China and India, along with the rapid expansion of the banking and e-commerce sectors requiring high-efficiency data processing.
- Europe: Maintains a steady market position with a focus on data privacy and sovereign cloud automation. Germany, the UK, and France are the key contributors to the regional market growth.
- Latin America & MEA: These regions are showing significant potential, particularly in the banking and government sectors, as they upgrade their legacy infrastructures to more resilient automated systems.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Workload Scheduling Automation Market.- Broadcom (CA Technologies)
- BMC Software
- IBM Corporation
- Redwood Software
- Stonebranch
- HCL Technologies
- Cisco Systems (Tidal)
- Fortra (HelpSystems)
- ActiveBatch (ASG Technologies)
- JAMS (HelpSystems)
- SMA Technologies
- Tidal Software
- Adaptive Computing
- Advanced Systems Concepts, Inc.
- Infinite Corporation
- Vico Software
- Arvato Systems
- Rocket Software
- Turbonomic
- Apptio
Frequently Asked Questions
What is the primary difference between job scheduling and workload scheduling automation?
Traditional job scheduling typically focuses on running tasks on a single server at a specific time. In contrast, workload scheduling automation (or SOAP) manages complex, interdependent workflows across distributed, hybrid environments, including cloud, containers, and mainframes, often triggered by events rather than just time.
How does AI impact the Workload Scheduling Automation market?
AI and machine learning introduce predictive capabilities, allowing the system to forecast resource needs, identify potential failures before they occur (self-healing), and optimize scheduling windows based on historical performance data, thereby maximizing infrastructure ROI.
Why is the Cloud-based segment growing faster than On-Premise?
Cloud-based solutions offer lower upfront capital expenditure, faster deployment times, and the inherent scalability required to manage modern, highly elastic cloud workloads. They also facilitate easier management of remote and distributed IT assets.
Which industry vertical is the largest adopter of these automation tools?
The BFSI (Banking, Financial Services, and Insurance) sector remains the largest adopter due to the critical nature of its data processing requirements, the high volume of daily transactions, and the need for strict compliance and auditability in automated workflows.
What are the main challenges in implementing workload automation in 2025?
Key challenges include the complexity of integrating with disparate legacy systems, the internal skills gap within IT departments to manage advanced orchestration scripts, and maintaining robust security and access controls across increasingly fragmented cloud environments.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
