Wind Turbine Casting Market
Wind Turbine Casting Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711888 | Published On : November 20, 2026 |
Format : 


 | Author : Seema Bhateja
Wind Turbine Casting Market Size
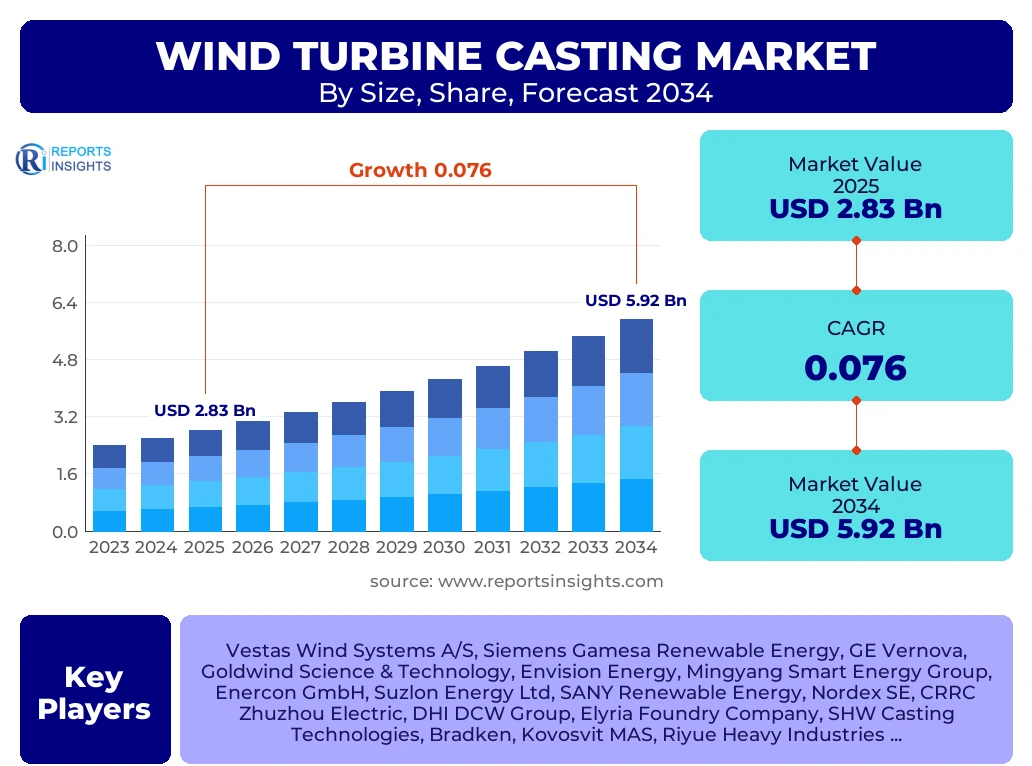
According to Reports Insights Consulting Pvt Ltd, The Wind Turbine Casting Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.6% between 2025 and 2034. The market is estimated at USD 3.05 Billion in 2026 and is projected to reach USD 5.92 Billion by the end of the forecast period in 2034.
Key Wind Turbine Casting Market Trends & Insights
The global wind turbine casting sector is undergoing a profound transformation driven by the escalating transition toward renewable energy and the technical demands of next-generation wind power systems. Stakeholders are increasingly focused on the transition from onshore to high-capacity offshore installations, which necessitates larger, more complex cast components capable of withstanding extreme marine environments. Current market intelligence indicates a significant shift toward the utilization of high-grade ductile iron and nodular cast iron to enhance the structural integrity of hubs and nacelles. Competitive benchmarking reveals that leading foundries are integrating advanced simulation software and automated finishing processes to reduce lead times and improve dimensional accuracy for massive components weighing over 50 metric tons. Furthermore, regional insights suggest that while China remains the production powerhouse due to its integrated supply chains, European manufacturers are pivoting toward high-value, high-precision offshore components to maintain a competitive edge.
- Largest Region: Asia-Pacific, specifically China, dominates the market share due to massive domestic installations and extensive foundry infrastructure.
- Fastest Growing Region: Europe is expected to witness the highest growth rate during the forecast period, spurred by aggressive offshore wind targets and the development of floating wind platforms.
- Largest Segment by Component: The Rotor Hub segment currently holds the largest market share, as it is a critical structural element that requires high-precision casting for every turbine manufactured.
- Largest Segment by Application: Onshore wind applications remain the largest segment by volume, although offshore applications are gaining rapid ground in terms of market value.
Key Takeaways Wind Turbine Casting Market Size & Forecast
The wind turbine casting market is poised for robust expansion as global decarbonization efforts intensify and energy security becomes a primary national concern for many economies. Analysts observe that the market size is being fundamentally reshaped by the "scaling effect," where individual turbine capacities are moving from 3-5 MW to 12-15 MW+, requiring exponentially larger and more robust cast components. This trend is driving a consolidation among specialized foundries that possess the technical capability to produce "mega-castings." The forecast period highlights a steady upward trajectory in market value, underpinned by significant investments in the North Sea, the Atlantic coast of the United States, and the expansive coastal regions of East Asia. Strategic focus is shifting toward supply chain resilience, with manufacturers seeking to mitigate the volatility of raw material prices, particularly scrap steel and pig iron, through long-term procurement contracts and recycled material integration.
- Leading Country: China is the primary driver of both demand and supply, accounting for nearly half of the global casting production capacity.
- Material Evolution: Spheroidal Graphite Iron (SGI) is becoming the industry standard for critical components due to its superior fatigue resistance and tensile strength.
- Market Growth Catalyst: The global push for Net Zero by 2050 is the primary long-term driver, ensuring a consistent pipeline of new wind farm projects globally.
- Offshore Complexity: Offshore wind projects require specialized corrosion-resistant coatings and higher metallurgical purity in castings, leading to higher profit margins for specialized manufacturers.
Wind Turbine Casting Market Drivers Analysis
The expansion of the wind turbine casting market is primarily fueled by the global imperative to replace fossil fuel-based power generation with sustainable alternatives. Government mandates and subsidies across the European Union, the United States (via the Inflation Reduction Act), and China are creating a highly favorable environment for utility-scale wind projects. This regulatory tailwind is complemented by the decreasing Levelized Cost of Energy (LCOE) for wind power, making it economically competitive with coal and natural gas in many jurisdictions. As turbine manufacturers strive for higher efficiency, the physical size of turbines continues to increase, which directly correlates to a greater volume and weight of cast components required per unit, thereby driving market revenue.
Furthermore, the trend toward technological modernization of aging wind farms, known as "repowering," is emerging as a significant market driver. Older turbines are being replaced with newer, more powerful models that utilize advanced casting designs for better load distribution and reduced maintenance. The integration of digital twin technology in the casting process is also allowing for the optimization of component weight without compromising structural safety, leading to more cost-effective logistics and installation. This synergy between regulatory support, economic viability, and technological advancement ensures a steady demand for high-quality wind turbine castings.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rapid Expansion of Offshore Wind Capacity | +2.8% | UK, Germany, China, USA | 2025 - 2034 |
| Government Subsidies and Green Energy Mandates | +2.1% | Global (EU/USA focus) | 2025 - 2030 |
| Increasing Turbine Capacity and Component Size | +1.5% | Global | 2026 - 2034 |
| Repowering Projects for Aging Wind Farms | +1.2% | USA, Germany, Denmark | 2027 - 2034 |
Wind Turbine Casting Market Restraints Analysis
Despite the positive outlook, the wind turbine casting market faces significant restraints, most notably the high volatility in raw material costs. The production of large-scale castings requires massive amounts of pig iron, scrap steel, and specialized alloys. Price fluctuations in the global commodities market, often driven by geopolitical tensions or shifts in industrial demand, can severely impact the profit margins of foundries. Additionally, the energy-intensive nature of the casting process makes manufacturers vulnerable to spikes in electricity and natural gas prices, which have been particularly volatile in the European market in recent years.
Logistical and infrastructural bottlenecks also serve as a major restraint. As wind turbine components grow in size, transporting these massive castings from the foundry to the assembly site or port becomes an immense challenge. Specialized heavy-lift vessels and transport vehicles are required, and many existing roads and bridges are not designed to handle such loads. This leads to increased project costs and potential delays. Furthermore, trade protectionism and the imposition of tariffs on imported steel and iron products can disrupt global supply chains, forcing manufacturers to source materials from higher-cost local suppliers, thereby hindering market growth in certain regions.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Raw Material Prices (Iron/Steel) | -1.4% | Global | 2025 - 2034 |
| Logistical Challenges for Oversized Components | -0.9% | USA, Europe | 2026 - 2034 |
| High Energy Costs in Casting Production | -0.7% | Europe, Japan | 2025 - 2030 |
Wind Turbine Casting Market Opportunities Analysis
The wind turbine casting market is ripe with opportunities, particularly in the realm of material science and additive manufacturing. There is a growing demand for advanced alloys that offer higher strength-to-weight ratios, which can significantly reduce the overall weight of the nacelle and tower, thereby lowering the cost of the supporting structure. Foundries that invest in R&D to develop these next-generation materials will find themselves at a competitive advantage. Additionally, the emergence of 3D printing for sand molds (additive manufacturing in casting) is revolutionizing the prototyping stage, allowing for more complex geometries and faster design iterations that were previously impossible with traditional methods.
Another significant opportunity lies in the nascent floating offshore wind market. Unlike fixed-bottom turbines, floating platforms require unique casting solutions to manage different load dynamics and motion. This segment is expected to explode toward the end of the decade as deep-water sites are developed. Furthermore, the push for "green casting"—utilizing renewable energy to power foundries and increasing the use of recycled scrap—aligns with the sustainability goals of major wind developers. Companies that can certify their castings as low-carbon will likely secure preferred supplier status in an increasingly ESG-conscious market.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Emergence of Floating Offshore Wind Technology | +3.2% | Norway, Japan, UK, USA | 2028 - 2034 |
| 3D Printing for Complex Mold Geometries | +1.8% | Germany, USA | 2026 - 2034 |
| Development of Low-Carbon "Green" Castings | +1.4% | Nordic Countries, EU | 2025 - 2034 |
Wind Turbine Casting Market Challenges Impact Analysis
One of the primary challenges facing the wind turbine casting industry is the capacity constraint of specialized foundries. The number of facilities worldwide capable of producing castings for 10MW+ turbines is relatively small. As demand surges, this creates a bottleneck that can delay large-scale wind farm deployments. Building new foundry capacity is a capital-intensive and time-consuming process, often taking several years to reach full production. This imbalance between supply and demand could lead to increased lead times and price inflation for critical components in the short to medium term.
Technical challenges also persist, particularly regarding the metallurgical integrity of massive castings. As components get larger, the risk of casting defects such as porosity, inclusions, or uneven cooling increases. Ensuring consistent quality across a production run of 50-ton hubs requires sophisticated cooling controls and non-destructive testing (NDT) techniques. Furthermore, there is a shortage of skilled labor, including foundry engineers and specialized technicians, which can hinder the adoption of new technologies and limit production throughput. Overcoming these technical and human resource barriers is essential for maintaining the momentum of the global wind energy transition.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Foundry Capacity Bottlenecks for Mega-Castings | -1.5% | Global | 2025 - 2029 |
| Maintaining Metallurgical Quality in Large Structures | -0.8% | Global | 2025 - 2034 |
| Shortage of Skilled Foundry Personnel | -0.6% | North America, Europe | 2025 - 2034 |
Wind Turbine Casting Market - Updated Report Scope
The scope of this report encompasses a detailed analysis of the global wind turbine casting market, focusing on the critical cast components that form the backbone of modern wind energy systems. It covers the entire value chain, from raw material procurement and foundry processes to final assembly and deployment in onshore and offshore environments. The analysis includes a granular breakdown of market trends by material type, component category, and turbine capacity, providing a holistic view of the industry's evolution over the forecast period. Special attention is given to the impact of technological innovations and regional regulatory frameworks on market dynamics.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.83 Billion |
| Market Forecast in 2034 | USD 5.92 Billion |
| Growth Rate | 7.6% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Vestas Wind Systems A/S, Siemens Gamesa Renewable Energy, GE Vernova, Goldwind Science & Technology, Envision Energy, Mingyang Smart Energy Group, Enercon GmbH, Suzlon Energy Ltd, SANY Renewable Energy, Nordex SE, CRRC Zhuzhou Electric, DHI DCW Group, Elyria Foundry Company, SHW Casting Technologies, Bradken, Kovosvit MAS, Riyue Heavy Industries, Zhejiang Jiali, Simplex Castings. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The wind turbine casting market is segmented based on material, component, turbine capacity, and application. This multi-dimensional approach allows for a precise understanding of which areas are driving growth and where technological shifts are most impactful. For instance, the material segment is increasingly dominated by ductile iron due to its superior mechanical properties, which are essential for the high-stress environments of offshore wind. The component segment highlights the vital role of rotor hubs and bedplates, which together account for a significant portion of the total casting weight in a turbine. Understanding these segments is crucial for suppliers to align their production capabilities with market demand.
- By Material Type:
- Ductile Iron (Nodular Cast Iron) - Leading material due to fatigue resistance.
- Gray Iron - Used for less critical, lower-stress components.
- Cast Steel - Utilized for specific heavy-duty structural parts.
- By Component:
- Rotor Hubs - The central connection point for blades.
- Nacelles/Bedplates - The primary structural support for the generator and gearbox.
- Gearbox Housings - Protective casing for high-torque transmission systems.
- Main Frames and Hollow Shafts.
- By Turbine Capacity:
- Up to 3 MW - Common in older onshore installations.
- 3 MW to 5 MW - The current standard for many global onshore projects.
- Above 5 MW - The rapidly growing segment for offshore and high-yield onshore sites.
- By Application:
- Onshore - High volume, established market.
- Offshore - High value, technically demanding, fastest growth.
Regional Highlights
- Asia-Pacific (APAC): China is the undisputed global leader in the wind turbine casting market, housing the world's largest foundry capacity. The region benefits from a highly integrated supply chain and massive domestic demand from state-led wind energy projects. India is also emerging as a significant hub for manufacturing and exports.
- Europe: This region is at the forefront of offshore technology. Countries like Germany, Denmark, and Spain host major turbine OEMs and specialized foundries. Europe leads in the development of "mega-turbines" and is the primary market for high-value offshore castings.
- North America: The market is driven by the United States, where the Inflation Reduction Act has spurred a wave of new onshore and offshore projects. There is a strong focus on building local supply chains to reduce dependence on overseas imports.
- Latin America: Brazil is the key player in this region, with a well-developed wind energy sector and growing casting manufacturing capabilities to support both domestic and regional markets.
- Middle East and Africa: Growth is emerging in countries like Morocco, Egypt, and South Africa as they diversify their energy mixes, though the casting supply chain remains largely reliant on imports from Europe and Asia.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Wind Turbine Casting Market.- Vestas Wind Systems A/S
- Siemens Gamesa Renewable Energy
- GE Vernova
- Goldwind Science & Technology
- Envision Energy
- Mingyang Smart Energy Group
- Enercon GmbH
- Suzlon Energy Ltd
- SANY Renewable Energy
- Nordex SE
- CRRC Zhuzhou Electric
- DHI DCW Group
- Elyria Foundry Company
- SHW Casting Technologies
- Bradken
- Kovosvit MAS
- Riyue Heavy Industries
- Zhejiang Jiali
- Simplex Castings
- Global Castings
Frequently Asked Questions
What is the current market size of the wind turbine casting industry?
The wind turbine casting market is estimated to be valued at approximately USD 3.05 Billion in 2026, with projections reaching USD 5.92 Billion by 2034, growing at a CAGR of 7.6%.
Which component holds the largest share in the wind turbine casting market?
The Rotor Hub is currently the largest component segment because it is a critical structural element required for every turbine, necessitating high-precision ductile iron casting.
Why is ductile iron preferred over other materials for turbine castings?
Ductile iron, or nodular cast iron, is preferred because it offers excellent fatigue resistance, high tensile strength, and superior vibration damping, which are essential for components subjected to the variable loads of wind energy.
How is the move toward offshore wind impacting the casting market?
Offshore wind requires much larger turbines (12MW+), which significantly increases the size and weight of individual castings. This drives higher market value and requires foundries to have advanced technical capabilities and specialized logistics.
Which region is expected to grow the fastest in the wind turbine casting market?
Europe is expected to be the fastest-growing region due to its aggressive offshore wind expansion targets, the development of floating wind technology, and the presence of leading turbine manufacturers.
Author
S
Seema Bhateja is a Manger Energy and Power Research Industry with 7+ years of experience in the Energy and Power Industry. She specializes in energy market intelligence, power generation analysis, renewable energy assessment, demand forecasting, competitive benchmarking, grid infrastructure evaluation, regulatory landscape analysis, market sizing, and investment trend analysis across conventional and clean energy sectors. Her research integrates industry expertise with data-driven methodologies to help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational efficiency, anticipate evolving market trends, and strengthen their competitive positioning in the global energy and power market.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
