Water Treatment Chemicals Market
Water Treatment Chemicals Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711782 | Published On : November 16, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Water Treatment Chemicals Market Size
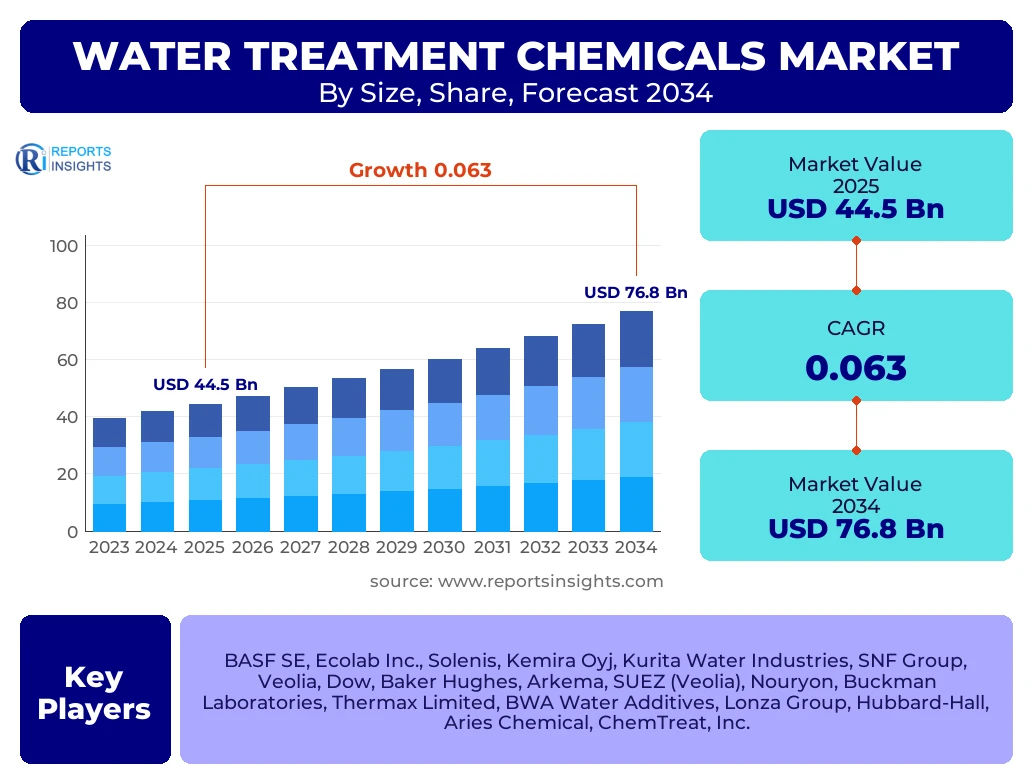
According to Reports Insights Consulting Pvt Ltd, The Water Treatment Chemicals Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.3% between 2025 and 2034. The market is estimated at USD 44.5 Billion in 2025 and is projected to reach USD 76.8 Billion by the end of the forecast period in 2034.
Key Water Treatment Chemicals Market Trends & Insights
The global landscape for water treatment chemicals is undergoing a significant transformation, driven by the dual pressures of increasing water scarcity and tightening environmental regulations. Current market intelligence indicates a massive shift toward specialized chemical formulations that offer higher efficiency with lower environmental footprints. Industrial operators are increasingly prioritizing closed-loop systems, where chemical additives facilitate the reuse of process water, thereby reducing the reliance on freshwater intake. This trend is particularly evident in water-stressed regions such as the Middle East and parts of Asia, where "Zero Liquid Discharge" (ZLD) mandates are becoming the standard rather than the exception.
Technological integration is another hallmark of the modern market. The emergence of smart water management systems has led to the development of "intelligent chemicals"—formulations designed to work in tandem with IoT sensors and real-time monitoring software. These systems allow for precise dosing, which minimizes chemical waste and optimizes the performance of cooling towers, boilers, and membrane systems. Furthermore, there is a burgeoning demand for bio-based and biodegradable coagulants and flocculants as municipal and industrial players seek to align with global ESG (Environmental, Social, and Governance) targets and reduce the toxicity of sludge produced during treatment.
- Largest Region: Asia Pacific remains the dominant market shareholder, accounting for over 35% of global revenue, fueled by rapid industrialization in China and India.
- Fastest Growing Region: Asia Pacific is also the fastest-growing region, with a projected CAGR exceeding the global average due to massive infrastructure investments in wastewater treatment plants.
- Largest Segment by Type: Coagulants and Flocculants hold the largest market share, essential for the primary treatment phase in both municipal and industrial sectors.
- Leading End-User: The Municipal segment currently leads the market, though the Industrial sector is catching up due to stringent effluent discharge standards.
- Emerging Trend: The adoption of green chemistry and non-phosphorus-based scale inhibitors is gaining rapid traction in North America and Europe.
Key Takeaways Water Treatment Chemicals Market Size & Forecast
The long-term outlook for the Water Treatment Chemicals Market remains robust, with consistent growth projected through 2034. Stakeholders are focusing on high-value specialty chemicals that address specific contaminants like PFAS, nitrates, and heavy metals, which are increasingly coming under regulatory scrutiny. The transition from commodity chemicals to value-added service models, where chemical providers also manage the treatment process, is expected to redefine competitive dynamics. Financial forecasts suggest that the intersection of population growth and industrial expansion will necessitate a continuous upgrade of chemical treatment capacities globally.
- The global market value is set to exceed USD 70 billion by 2033, reflecting the critical nature of clean water as a strategic resource.
- Sustainability is no longer optional; market leaders are aggressively investing in R&D for eco-friendly biocides and corrosion inhibitors.
- The Power Generation and Oil & Gas industries remain the most significant industrial consumers of cooling water and boiler water chemicals.
- China and India are identified as the primary engines of demand, representing the largest infrastructure development projects for water desalination and recycling.
- Supply chain resilience is becoming a key differentiator, as companies localize production to mitigate the risks associated with global logistics volatility.
Water Treatment Chemicals Market Drivers Analysis
The expansion of the Water Treatment Chemicals Market is primarily propelled by the heightening global awareness of water security and the implementation of rigorous environmental protection laws. As urbanization accelerates, the demand for potable water increases, forcing municipal bodies to expand their treatment capacities and adopt more sophisticated chemical solutions to ensure safety and hygiene. Simultaneously, industrial sectors are facing pressure to treat their wastewater to high standards before discharge, driving the consumption of specialized coagulants, biocides, and pH adjusters.
Another critical driver is the aging infrastructure in developed economies. In regions like North America and Europe, many water treatment systems require chemical interventions to maintain efficiency and prevent corrosion in older pipe networks. Additionally, the rise of the "circular economy" concept encourages industries to recycle water internally. This necessitates the use of high-performance scale and corrosion inhibitors to protect expensive machinery from the harsh conditions of recycled process water, which often contains higher concentrations of dissolved solids.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Environmental & Discharge Regulations | +1.8% | European Union, USA, China | 2025 - 2034 |
| Rapid Urbanization and Population Growth | +1.5% | India, Southeast Asia, Africa | 2025 - 2034 |
| Industrial Demand for Boiler & Cooling Water | +1.2% | Global | 2025 - 2030 |
| Rising Adoption of Desalination Technologies | +0.9% | Middle East, North Africa | 2026 - 2034 |
Water Treatment Chemicals Market Restraints Analysis
Despite the positive growth trajectory, the market faces several significant hurdles. One of the primary restraints is the high cost of advanced specialty chemicals. While commodity chemicals are relatively inexpensive, the specialized formulations required for complex industrial wastewater or highly contaminated sources can be prohibitively expensive for small and medium-sized enterprises (SMEs) and developing municipalities. This often leads to the continued use of outdated, less efficient chemical methods or the delay of necessary infrastructure upgrades.
Furthermore, the regulatory landscape regarding the chemicals themselves is becoming more complex. Legislative frameworks such as REACH in Europe impose strict testing and documentation requirements on chemical manufacturers. Some effective but environmentally persistent chemicals, such as certain types of phosphorus-based inhibitors or chlorine-based biocides, are being phased out or strictly limited. Finding cost-effective, high-performance alternatives that comply with these evolving safety standards remains a significant challenge for the industry’s R&D departments.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fluctuating Raw Material Prices | -0.7% | Global | 2025 - 2034 |
| Strict Environmental Regulations on Chemical Usage | -0.5% | Europe, North America | 2025 - 2034 |
| Competition from Alternative Physical Treatment | -0.4% | Global | 2027 - 2034 |
Water Treatment Chemicals Market Opportunities Analysis
The market is ripe with opportunities, particularly in the realm of technological innovation and geographical expansion. The growing interest in "Green Chemistry" provides a massive opening for manufacturers to develop non-toxic, bio-degradable chemical alternatives. These products appeal to environmentally conscious corporations and municipalities that are under pressure to reduce their chemical footprint. Companies that can successfully commercialize effective bio-coagulants or plant-derived biocides are expected to capture a significant premium in the market.
Digitalization and the "Water 4.0" initiative also present a lucrative opportunity. There is a rising demand for integrated chemical management services where the chemical supplier provides not just the product, but also the hardware and software to monitor and optimize its use. This "Chemicals-as-a-Service" model creates long-term, stable revenue streams and deeper customer relationships. Additionally, the expansion of the desalination market in water-scarce regions provides a steady demand for anti-scalants and membrane cleaners, which are essential for maintaining the efficiency of reverse osmosis systems.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-based Treatment Chemicals | +1.4% | Global | 2026 - 2034 |
| Emergence of "Chemicals-as-a-Service" Models | +1.1% | North America, Europe | 2025 - 2034 |
| Expansion in Municipal Infrastructure in APAC | +1.3% | China, India, Vietnam | 2025 - 2034 |
Water Treatment Chemicals Market Challenges Impact Analysis
One of the most persistent challenges is the volatility of the global supply chain for raw materials. Many water treatment chemicals rely on precursors derived from the petrochemical industry, making them sensitive to fluctuations in crude oil prices and geopolitical instability. Additionally, the logistics of transporting hazardous chemicals are becoming increasingly expensive and regulated, which adds to the final cost for the end-user. Ensuring a consistent and affordable supply of high-purity chemicals is a major operational hurdle for global manufacturers.
Another challenge is the increasing competition from physical water treatment technologies such as UV disinfection, ozone treatment, and advanced membrane filtration (Ultrafiltration and Nanofiltration). While these technologies often require chemical assistance, they can reduce the total volume of chemicals needed, potentially cannibalizing the market for traditional treatment agents. Manufacturers must therefore pivot their value proposition, focusing on how their chemicals enhance and protect these physical systems rather than just competing with them as standalone solutions.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Disruptions in Global Supply Chains | -0.6% | Global | 2025 - 2028 |
| Adoption of Advanced Membrane Technologies | -0.4% | Developed Markets | 2026 - 2034 |
| Shortage of Skilled Personnel for Chemical Dosing | -0.3% | Developing Regions | 2025 - 2030 |
Water Treatment Chemicals Market - Updated Report Scope
The updated report scope provides a comprehensive analysis of the global water treatment chemicals industry, covering a ten-year forecast period. It meticulously evaluates the market dynamics across major chemical types, diverse end-user industries, and critical geographic regions. The scope includes an in-depth assessment of the competitive landscape, featuring the top players and their strategic maneuvers. This report is designed to serve as a definitive guide for stakeholders, providing data-driven insights into market sizing, growth drivers, and future investment opportunities in the context of the global water crisis and industrial evolution.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 44.5 Billion |
| Market Forecast in 2034 | USD 76.8 Billion |
| Growth Rate | 6.3% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, Ecolab Inc., Solenis, Kemira Oyj, Kurita Water Industries, SNF Group, Veolia, Dow, Baker Hughes, Arkema, SUEZ (Veolia), Nouryon, Buckman Laboratories, Thermax Limited, BWA Water Additives, Lonza Group, Hubbard-Hall, Aries Chemical, ChemTreat, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Water Treatment Chemicals Market is segmented based on the specific chemical function and the target end-use industry. Coagulants and flocculants remain the largest segment by volume, as they are indispensable for removing suspended solids in the initial stages of water purification. The demand for corrosion and scale inhibitors is particularly high in industrial applications where they protect multi-million dollar assets like cooling towers and boilers from degradation. Biocides and disinfectants are seeing steady growth, driven by the need to eliminate harmful pathogens in municipal drinking water and prevent biofouling in industrial systems.
From an end-user perspective, the municipal sector accounts for a significant portion of the market, focused on providing safe drinking water and managing urban wastewater. However, the industrial sector is the fastest-growing segment. Industries such as Power Generation and Oil & Gas require massive volumes of water and must adhere to strict environmental discharge permits. Furthermore, the Food & Beverage and Pharmaceutical industries demand ultra-pure water, creating a specialized niche for high-purity chemical treatment solutions that ensure product safety and compliance with health regulations.
- By Type:
- Coagulants & Flocculants (Organic and Inorganic)
- Corrosion Inhibitors (Anodic, Cathodic, Mixed)
- Scale Inhibitors (Phosphonates, Polymers)
- Biocides & Disinfectants (Oxidizing and Non-oxidizing)
- pH Adjusters & Softeners
- Anti-foaming Agents
- Other Specialty Chemicals (Oxygen Scavengers, Chelating Agents)
- By End-User Industry:
- Municipal Water Treatment (Potable and Wastewater)
- Power Generation
- Oil & Gas (Upstream, Midstream, Downstream)
- Pulp & Paper Manufacturing
- Food & Beverage Processing
- Chemical and Petrochemical Processing
- Mining and Metal Industry
- Pharmaceuticals and Healthcare
Regional Highlights
The Asia Pacific region stands as the titan of the Water Treatment Chemicals Market. Driven by the twin forces of rapid industrialization and urban expansion in China, India, and Southeast Asian nations, the region commands the largest market share. Governments in these countries are investing heavily in water treatment infrastructure to support growing populations and to combat severe pollution levels in major river systems. China, in particular, has implemented "Water Ten Plan" and other stringent policies that mandate high-efficiency wastewater treatment, significantly boosting the demand for advanced chemical solutions.
North America and Europe represent mature markets where growth is primarily driven by the replacement of aging infrastructure and the adoption of high-performance specialty chemicals. In these regions, environmental regulations are among the strictest in the world, pushing industries toward sustainable and green chemistry. The Middle East and Africa (MEA) region is a critical area for the desalination sub-segment. With limited freshwater resources, countries like Saudi Arabia and the UAE rely heavily on seawater desalination, which requires substantial quantities of anti-scalants and biocides to maintain operational efficiency. Latin America is also showing promise, particularly in the mining and agricultural sectors where water management is becoming a critical operational priority.
- Asia Pacific: The largest and fastest-growing region, with China and India leading in infrastructure spending and industrial wastewater mandates.
- North America: A major hub for technological innovation in smart water systems and advanced PFAS removal chemicals.
- Europe: Leading the transition toward eco-friendly, biodegradable water treatment agents under the REACH regulatory framework.
- Middle East & Africa: Dominant in the desalination chemicals segment due to extreme water scarcity and high investment in RO plants.
- Latin America: Growth driven by the mining sector’s need for efficient water recycling and tailings management.

Top Key Players
The market research report includes a detailed profile of leading top-wise companies in the Water Treatment Chemicals Market. The competitive landscape is characterized by a mix of diversified chemical giants and specialized water technology firms. Leading companies are focusing on strategic acquisitions, R&D in green chemistry, and the expansion of their service-based business models to consolidate their market positions.
- BASF SE
- Ecolab Inc. (Nalco Water)
- Solenis (including Sigura)
- Kemira Oyj
- Kurita Water Industries Ltd.
- SNF Group
- Veolia Water Technologies (including SUEZ Water Technologies & Solutions)
- The Dow Chemical Company
- Baker Hughes Company
- Arkema S.A.
- Nouryon
- Buckman Laboratories International, Inc.
- Thermax Limited
- BWA Water Additives
- Lonza Group
- Hubbard-Hall Inc.
- Aries Chemical
- ChemTreat, Inc. (Danaher Corporation)
- Metito
- Somicon Middle East
Frequently Asked Questions
What is the projected market size of the Water Treatment Chemicals Market by 2034?
The global Water Treatment Chemicals Market is projected to reach approximately USD 76.8 Billion by 2034, growing at a steady CAGR of 6.3% from 2025.
Which chemical type holds the largest share in the market?
Coagulants and Flocculants currently hold the largest market share as they are fundamental to the primary treatment process in both municipal and industrial wastewater facilities.
Which region is expected to grow the fastest during the forecast period?
The Asia Pacific region is expected to be the fastest-growing market due to rapid industrialization, massive urban development, and increasing government focus on environmental regulations in China and India.
How is "Green Chemistry" impacting the Water Treatment Chemicals Market?
Green Chemistry is driving the development of non-toxic, bio-degradable chemical alternatives, helping companies meet ESG targets and comply with stricter environmental safety regulations like REACH.
What are the main challenges facing the Water Treatment Chemicals Market?
Key challenges include the volatility of raw material prices, high costs of advanced specialty chemicals, and increasing competition from physical water treatment technologies such as UV and advanced membrane systems.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
