Ventricular Assist Devices Market
Ventricular Assist Devices Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711115 | Published On : October 09, 2026 |
Format : 


 | Author : Erika Grotto
Ventricular Assist Devices Market Size
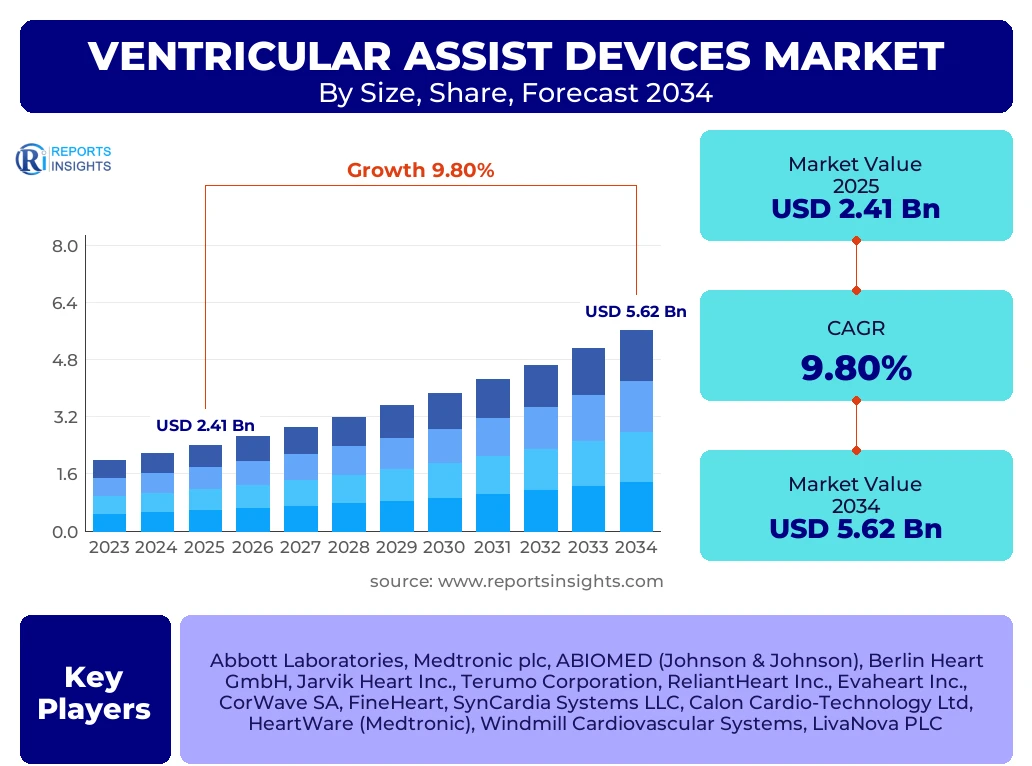
According to Reports Insights Consulting Pvt Ltd, The Ventricular Assist Devices Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 9.8% between 2025 and 2034. The market is estimated at USD 2.65 Billion in 2026 and is projected to reach USD 5.62 Billion by the end of the forecast period in 2034.
Key Ventricular Assist Devices Market Trends & Insights
The global Ventricular Assist Devices (VAD) market is undergoing a significant transformation driven by the miniaturization of device components and the integration of advanced biocompatible materials. Currently, the industry is shifting from pulsatile flow to continuous-flow technology, which offers improved durability and reduced surgical complexity. Key trends include the rising adoption of Destination Therapy (DT) as a long-term solution for patients ineligible for heart transplants, alongside the development of fully implantable systems that eliminate the need for external drivelines, thereby reducing infection risks. Regional analysis indicates that North America remains the primary revenue generator due to high healthcare expenditure, while the Asia-Pacific region is poised for the fastest growth owing to expanding medical infrastructure and a rising geriatric population susceptible to heart failure.
- North America is the largest regional market, accounting for over 45% of the global market share in 2025.
- The Asia-Pacific region is the fastest-growing market, projected to expand at a CAGR of 11.4% during the forecast period.
- Left Ventricular Assist Devices (LVADs) constitute the largest segment by product type, driven by the high prevalence of left-sided heart failure.
- Destination Therapy is the leading application segment, surpassing Bridge-to-Transplant (BTT) in terms of total market value.
- Technological advancements in magnetic levitation (MagLev) are significantly reducing complications such as pump thrombosis.
Key Takeaways Ventricular Assist Devices Market Size & Forecast
The global outlook for the Ventricular Assist Devices market remains highly positive, supported by a critical shortage of donor hearts and the increasing incidence of end-stage heart failure. Strategic analysis reveals that market players are focusing on enhancing patient quality of life through remote monitoring capabilities and reduced-size controllers. The forecast indicates a steady upward trajectory as healthcare systems in emerging economies increase reimbursement coverage for VAD procedures. Furthermore, the integration of Artificial Intelligence (AI) for predictive analytics in patient management is expected to redefine the competitive landscape, offering stakeholders new avenues for clinical optimization and market expansion.
- The global market value is expected to more than double between 2025 and 2034, reflecting robust demand for mechanical circulatory support.
- The United States is the leading country globally, supported by a sophisticated network of specialized cardiac centers and favorable Medicare/Medicaid policies.
- Germany and the United Kingdom are the primary drivers of growth in the European market, focusing on high-end implantable technologies.
- Pediatric VADs represent a niche but high-growth opportunity segment, with specific focus on small-scale device engineering.
- Implantable VADs hold a dominant share over transcutaneous devices due to their suitability for long-term home-based care.
Ventricular Assist Devices Market Drivers Analysis
The primary catalyst for the Ventricular Assist Devices market is the escalating global burden of Cardiovascular Diseases (CVDs), which remain the leading cause of mortality worldwide. As the prevalence of chronic conditions like hypertension and diabetes increases, the resulting incidences of heart failure are driving the demand for mechanical circulatory support systems. Additionally, the chronic shortage of organ donors creates a supply-demand gap that VADs effectively bridge, making them an essential therapeutic intervention.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Prevalence of Heart Failure Cases | +3.2% | Global / North America | 2025 - 2034 |
| Technological Advancements in MagLev and Wireless Charging | +2.5% | Europe / Japan | 2026 - 2030 |
| Expanding Geriatric Population | +1.8% | Asia-Pacific / China / India | 2025 - 2034 |
| Shortage of Heart Donors Globally | +2.3% | Global | 2025 - 2034 |
Ventricular Assist Devices Market Restraints Analysis
Despite strong growth prospects, the market faces constraints primarily related to the high cost of the devices and the associated surgical procedures. A typical VAD implantation, including post-operative care, can cost several hundred thousand dollars, limiting its accessibility in low-to-middle-income countries. Furthermore, the risk of post-surgical complications, such as stroke, internal bleeding, and driveline infections, continues to pose challenges for widespread clinical adoption.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Devices and Procedures | -2.1% | Latin America / Africa | 2025 - 2034 |
| Risk of Infections and Thrombosis | -1.5% | Global | 2025 - 2030 |
| Strict Regulatory Approval Processes | -1.2% | European Union / USA | 2025 - 2028 |
Ventricular Assist Devices Market Opportunities Analysis
The market is ripe with opportunities for innovation, particularly in the development of "smart" VADs equipped with sensors that allow real-time physiological monitoring. There is also a significant untapped potential in the emerging markets of Asia and Latin America, where healthcare infrastructure is rapidly modernizing. Collaborative ventures between medical device manufacturers and digital health companies are expected to create integrated patient care platforms that enhance long-term outcomes.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of AI and Remote Patient Monitoring | +2.8% | USA / Germany | 2027 - 2034 |
| Expansion in Emerging Economies | +2.4% | India / Brazil / Southeast Asia | 2026 - 2034 |
| Development of Pediatric-Specific Devices | +1.5% | Global | 2025 - 2034 |
Ventricular Assist Devices Market Challenges Impact Analysis
The VAD market faces significant challenges regarding long-term reliability and the psychological impact on patients living with external power components. Maintaining a consistent supply chain for specialized components during geopolitical instability is another concern. Additionally, the competition from alternative therapies, such as advanced pharmacological treatments and regenerative medicine (stem cell therapy), could potentially disrupt the growth of mechanical device adoption.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Alternative Non-Surgical Therapies | -1.4% | Global | 2028 - 2034 |
| Reimbursement Policy Fluctuations | -1.1% | USA / UK | 2025 - 2030 |
| Supply Chain Constraints for Specialized Materials | -0.8% | Global | 2025 - 2027 |
Ventricular Assist Devices Market - Updated Report Scope
This comprehensive report provides an in-depth analysis of the global Ventricular Assist Devices landscape, covering technological bifurcations, application spectrums, and regional dynamics. It evaluates the impact of macroeconomic factors and healthcare policy shifts on market growth. The scope extends from historical data analysis (2020-2024) to precise future projections through 2034, offering a granular view of the competitive hierarchy and emerging technological paradigms.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 2.41 Billion |
| Market Forecast in 2034 | USD 5.62 Billion |
| Growth Rate | 9.8% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Abbott Laboratories, Medtronic plc, ABIOMED (Johnson & Johnson), Berlin Heart GmbH, Jarvik Heart Inc., Terumo Corporation, ReliantHeart Inc., Evaheart Inc., CorWave SA, FineHeart, SynCardia Systems LLC, Calon Cardio-Technology Ltd, HeartWare (Medtronic), Windmill Cardiovascular Systems, LivaNova PLC |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Ventricular Assist Devices market is intricately segmented to provide clarity on the diverse technological and clinical pathways used in heart failure management. The segmentation reflects the market's transition from temporary solutions to permanent circulatory support. Product-wise, LVADs dominate the landscape due to the higher incidence of left heart failure, while destination therapy is becoming the primary clinical application as device longevity improves and donor heart availability remains stagnant.
- By Product Type:
- Left Ventricular Assist Devices (LVAD): The highest revenue-generating segment, essential for treating systemic heart failure.
- Right Ventricular Assist Devices (RVAD): Primarily used for acute right heart failure or post-cardiotomy support.
- Biventricular Assist Devices (BiVAD): Required for patients with advanced failure in both ventricles.
- Percutaneous VAD: Growing rapidly in the cath-lab setting for temporary support during high-risk interventions.
- By Design:
- Implantable VAD: Dominates the market for chronic management and destination therapy.
- Transcutaneous VAD: Mostly utilized for short-term and emergency circulatory support.
- By Application:
- Bridge-to-Transplant (BTT): Traditional use case where the device maintains life until a donor heart is found.
- Destination Therapy (DT): The most significant growth segment, where the VAD serves as a permanent solution for end-stage patients.
- Bridge-to-Recovery (BTR): Used when the patient's heart is expected to regain function after surgery or illness.
- Bridge-to-Candidacy (BTC): For patients who may become eligible for a transplant after physiological stabilization.
- By Age Group:
- Adult: The primary patient demographic, driven by age-related heart failure.
- Pediatric: A specialized segment focused on congenital heart defects and pediatric cardiomyopathy.
Regional Highlights
Regional dynamics are shaped by healthcare expenditure, the density of specialized heart centers, and the prevalence of cardiovascular diseases. North America and Europe are mature markets focusing on technological refinements, while the Asia-Pacific region represents the frontier for market expansion through increased healthcare access.
- North America: The largest market globally, characterized by high adoption rates of the latest continuous-flow pumps and extensive insurance coverage for destination therapy. The U.S. remains the central hub for innovation and clinical trials.
- Europe: A significant market with strong research foundations in Germany, France, and the UK. European markets are leaders in adopting specialized pediatric VADs and have robust public health reimbursement frameworks.
- Asia-Pacific: The fastest-growing region. Rapidly aging populations in Japan and China, along with rising disposable incomes and healthcare infrastructure investment in India, are driving demand. Japan is particularly advanced in the development of small-form-factor devices.
- Latin America: Growth is emerging in countries like Brazil and Mexico, though it is currently hindered by high device costs and limited specialized surgical expertise.
- Middle East & Africa: A niche market with growth potential in the Gulf Cooperation Council (GCC) countries, driven by high rates of metabolic disorders leading to premature heart failure.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Ventricular Assist Devices Market.- Abbott Laboratories
- Medtronic plc
- ABIOMED (Johnson & Johnson)
- Berlin Heart GmbH
- Jarvik Heart Inc.
- Terumo Corporation
- ReliantHeart Inc.
- Evaheart Inc.
- CorWave SA
- FineHeart
- SynCardia Systems LLC
- Calon Cardio-Technology Ltd
- LivaNova PLC
- Windmill Cardiovascular Systems
- Procyrion Inc.
- Orchestra BioMed
- Cirtec Medical
Frequently Asked Questions
What is the current market size of the Ventricular Assist Devices market?
The Ventricular Assist Devices market is estimated at USD 2.41 Billion in 2025 and is projected to reach USD 5.62 Billion by 2034, growing at a CAGR of 9.8% during the forecast period.
What is the primary difference between Bridge-to-Transplant and Destination Therapy?
Bridge-to-Transplant (BTT) is a temporary use of a VAD until a donor heart becomes available for transplant. Destination Therapy (DT) is the permanent implantation of a VAD for patients who are not eligible for a heart transplant due to age or other health factors.
Which product segment holds the largest share of the market?
Left Ventricular Assist Devices (LVAD) hold the largest market share, as left-sided heart failure is the most common form of heart failure requiring mechanical circulatory support.
How is the integration of Artificial Intelligence impacting the VAD market?
AI is being used to develop predictive algorithms that monitor pump parameters in real-time, allowing clinicians to foresee complications like pump thrombosis or suction events before they become critical, thereby improving patient safety.
What are the main barriers to market growth in emerging economies?
The primary barriers include the extremely high cost of the device and surgery, lack of specialized cardiac surgeons, and insufficient reimbursement coverage in many developing countries.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
