Alpha Emitter Market
Alpha Emitter Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711271 | Published On : October 24, 2026 |
Format : 


 | Author : Erika Grotto
Alpha Emitter Market Size
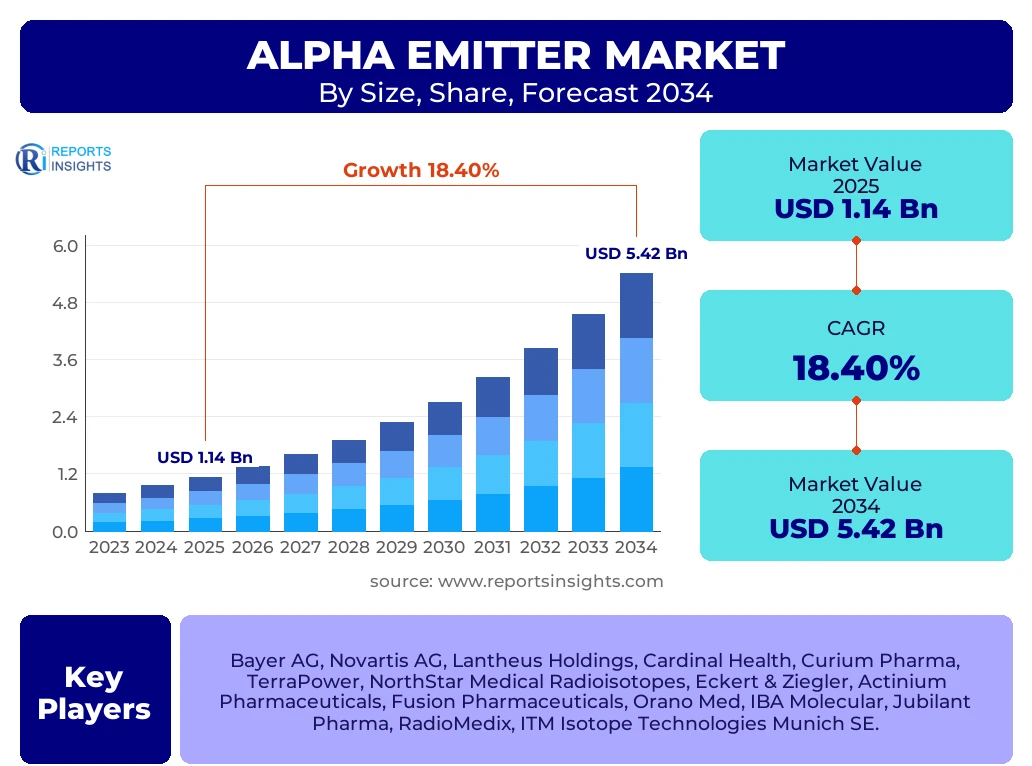
According to Reports Insights Consulting Pvt Ltd, The Alpha Emitter Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 18.4% between 2025 and 2034. The market is estimated at USD 1.14 Billion in 2026 and is projected to reach USD 5.42 Billion by the end of the forecast period in 2034.
Key Alpha Emitter Market Trends & Insights
The global Alpha Emitter market is undergoing a transformative shift characterized by the rapid transition from experimental clinical trials to large-scale commercialization of Targeted Alpha Therapy (TAT). Stakeholders are increasingly focusing on Actinium-225 and Radium-223 as the primary vehicles for delivering high-energy radiation directly to tumor cells while sparing surrounding healthy tissue. This high-precision oncology approach is driving significant investments in specialized nuclear reactor facilities and cyclotron networks to stabilize the supply chain. Market intelligence suggests a surge in strategic partnerships between pharmaceutical giants and isotope producers to secure long-term access to rare isotopes, which currently act as the primary bottleneck for market expansion. Furthermore, the integration of theranostics—pairing diagnostic imaging with alpha-emitting therapeutics—is becoming the gold standard for personalized cancer treatment protocols.
- Largest Region: North America remains the dominant region, accounting for over 42% of the total market share due to advanced healthcare infrastructure and high adoption of radiopharmaceuticals.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR during the forecast period, driven by expanding medical tourism and increased investments in nuclear medicine in China and India.
- Largest Segment by Share: The Oncology segment, specifically for Prostate Cancer treatment, holds the largest market share owing to the success of radium-based therapies.
- Emerging Trend: Development of Lead-212 and Astatine-211 as potential next-generation emitters for diverse solid tumor applications.
- Competitive Landscape: Shift towards decentralized production models to mitigate the challenges posed by the short half-lives of alpha-emitting isotopes.
Key Takeaways Alpha Emitter Market Size & Forecast
The Alpha Emitter market is poised for exponential growth as clinical evidence continues to support the superior efficacy of alpha particles over beta particles in treating micrometastatic disease. Investors and healthcare providers are prioritizing the scalability of Actinium-225, which is viewed as the "holy grail" of nuclear medicine. The forecast period will see a significant expansion in the number of approved indications for TAT, moving beyond bone metastases to include neuroendocrine tumors and various hematologic malignancies. The market’s trajectory is heavily influenced by regulatory support for fast-track approvals of life-saving radiopharmaceuticals and the modernization of nuclear pharmacies across developed economies.
- Leading Country: The United States leads the market value, supported by extensive R&D pipelines and a robust reimbursement framework for radio-immunotherapy.
- Technological Shift: Transition from reactor-based production to high-energy cyclotron and generator-based production systems for isotopes like Actinium-225.
- Market Driver: Rising global prevalence of late-stage cancers where conventional chemotherapy and external beam radiation have limited efficacy.
- Strategic Focus: Key players are concentrating on vertical integration, acquiring isotope production capacity to ensure uninterrupted clinical supply.
- Growth Milestone: The market is expected to cross the 3-billion-dollar threshold by 2030, marking a mature phase of commercial adoption for targeted alpha therapies.
Alpha Emitter Market Drivers Analysis
The primary catalyst for the Alpha Emitter market is the unparalleled High Linear Energy Transfer (LET) of alpha particles, which causes lethal double-strand DNA breaks in cancer cells with minimal range, significantly reducing collateral damage to adjacent healthy organs. This unique physical property makes alpha emitters the preferred choice for treating small clusters of cancer cells and micrometastases that are often missed by traditional therapies. Furthermore, the increasing global geriatric population, which is more susceptible to various forms of cancer, is creating a sustained demand for more effective and less toxic treatment modalities. The growth is further bolstered by the entry of major pharmaceutical companies into the radiopharmaceutical space, bringing the financial capital and logistical expertise required to scale these complex treatments.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in Targeted Alpha Therapy (TAT) | +6.2% | Global / North America | 2025 - 2034 |
| Rising Prevalence of Prostate and Neuroendocrine Cancers | +4.5% | Europe and APAC | 2025 - 2030 |
| Investment in Nuclear Isotope Production Infrastructure | +3.8% | United States / Canada | 2026 - 2034 |
| Shift Toward Personalized Theranostic Models | +3.9% | Germany / France | 2025 - 2034 |
Alpha Emitter Market Restraints Analysis
Despite the high therapeutic potential, the market faces significant hurdles related to the complex logistics and extremely short half-lives of many alpha-emitting isotopes. This necessitates a "just-in-time" manufacturing and delivery model that is susceptible to transportation delays and regulatory bottlenecks across international borders. Additionally, the high cost of production and the specialized requirements for handling radioactive materials limit the number of hospitals and clinics capable of administering these therapies, particularly in low-to-middle-income regions. The stringent regulatory environment surrounding nuclear waste management and radiation safety also adds a layer of operational complexity and cost for market participants.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain and Logistical Constraints | -2.8% | Global | 2025 - 2030 |
| High Cost of Radiopharmaceutical Development | -2.1% | Emerging Markets | 2025 - 2034 |
| Shortage of Specialized Nuclear Medicine Personnel | -1.5% | Global / APAC | 2026 - 2034 |
Alpha Emitter Market Opportunities Analysis
The Alpha Emitter market presents substantial opportunities in the development of novel ligand-isotope combinations that can target a wider array of solid tumors, such as glioblastoma and pancreatic cancer. There is a growing niche for the development of portable alpha-isotope generators that could be installed at the point of care, potentially revolutionizing the delivery of these therapies in remote locations. Furthermore, the collaboration between public health entities and private enterprises to establish national radiopharmaceutical hubs provides a framework for scaling production and reducing unit costs through economies of scale. The rise of Astatine-211 and Lead-212 as versatile emitters opens new pathways for immunotherapy combinations, where alpha emitters can enhance the immune response against tumors.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of New Radio-Ligands for Solid Tumors | +5.4% | United States / Japan | 2027 - 2034 |
| Expansion into Emerging Asian Healthcare Markets | +4.2% | China / India | 2026 - 2034 |
| Point-of-Care Isotope Generation Technology | +3.1% | Europe | 2028 - 2034 |
Alpha Emitter Market Challenges Impact Analysis
The primary challenge remains the global supply deficit of Actinium-225 and other critical isotopes, which often lags behind the growing demand from clinical trials and commercial applications. Ensuring a consistent, high-purity supply requires massive capital expenditure in nuclear facilities that have long lead times for construction and licensing. Moreover, the industry must navigate disparate regulatory frameworks across different jurisdictions, which can delay the global rollout of new therapies. Competing technologies, such as advanced immunotherapy and proton beam therapy, also pose a challenge for market share, necessitating clear clinical differentiation and cost-effectiveness data for alpha emitters.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Isotope Supply-Demand Imbalance | -3.5% | Global | 2025 - 2034 |
| Complex Regulatory Approval for Nuclear Facilities | -1.8% | North America / Europe | 2025 - 2030 |
| Competition from Non-Nuclear Cancer Therapies | -1.2% | Global | 2026 - 2034 |
Alpha Emitter Market - Updated Report Scope
This comprehensive report provides a deep-dive analysis of the global Alpha Emitter market, encompassing production technologies, clinical applications, and regional market dynamics. It offers a detailed assessment of the competitive landscape, identifying key players and their strategic initiatives. The scope extends to a granular segmentation of isotopes including Actinium-225, Radium-223, and others, while forecasting market performance across various therapeutic areas and end-user segments until 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.14 Billion |
| Market Forecast in 2034 | USD 5.42 Billion |
| Growth Rate | 18.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Bayer AG, Novartis AG, Lantheus Holdings, Cardinal Health, Curium Pharma, TerraPower, NorthStar Medical Radioisotopes, Eckert & Ziegler, Actinium Pharmaceuticals, Fusion Pharmaceuticals, Orano Med, IBA Molecular, Jubilant Pharma, RadioMedix, ITM Isotope Technologies Munich SE. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Alpha Emitter market is segmented based on the specific radionuclide type, therapeutic application, and end-user environment. This segmentation reflects the diverse clinical utility and the varied production methods required for different alpha-emitting isotopes. The oncology application remains the primary engine for market growth, with sub-segments focusing on specific cancer types such as metastatic castration-resistant prostate cancer (mCRPC). The end-user segment highlights the transition from academic research settings to widespread clinical hospital adoption.
- By Type:
- Radium-223: The most commercially mature isotope used primarily for bone metastases.
- Actinium-225: High-growth potential isotope for targeted therapy in multiple cancer types.
- Bismuth-213: Utilized for localized therapy and research.
- Astatine-211 & Lead-212: Emerging isotopes with promising results in clinical trials for solid tumors.
- By Application:
- Prostate Cancer: Largest market application due to high patient volume and successful TAT drugs.
- Neuroendocrine Tumors (NETs): Growing application area following the success of theranostic protocols.
- Hematologic Malignancies: Exploration of alpha emitters in leukemia and lymphoma treatments.
- By End-User:
- Hospitals & Oncology Centers: Primary centers for patient treatment and therapy administration.
- Nuclear Pharmacies: Critical hubs for the preparation and dispensing of short-lived alpha emitters.
- Research Institutes: Focused on the development of new radio-immunotherapies.
Regional Highlights
- North America: The largest market share holder, driven by the presence of major pharmaceutical companies, high healthcare spending, and a robust regulatory framework (FDA) that encourages radiopharmaceutical innovation. The United States is the primary contributor to regional growth.
- Europe: The second-largest market, characterized by extensive research in nuclear medicine, particularly in Germany, France, and the Netherlands. Europe has a long history of radionuclide production and is a leader in clinical trial density for alpha therapies.
- Asia-Pacific: The fastest-growing region, fueled by the modernization of healthcare infrastructure in China, Japan, and India. Increasing cancer awareness and government initiatives to improve nuclear medicine facilities are key growth drivers.
- Latin America & MEA: These regions represent emerging opportunities, with growth centered around major urban healthcare hubs that are increasingly adopting advanced cancer treatments as specialized training for medical physicists becomes more available.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Alpha Emitter Market.- Bayer AG
- Novartis AG (Advanced Accelerator Applications)
- Lantheus Holdings
- Cardinal Health
- Curium Pharma
- TerraPower, LLC
- NorthStar Medical Radioisotopes
- Eckert & Ziegler Strahlen- und Medizintechnik AG
- Actinium Pharmaceuticals, Inc.
- Fusion Pharmaceuticals (AstraZeneca)
- Orano Med
- IBA Molecular
- Jubilant Pharma Limited
- RadioMedix, Inc.
- ITM Isotope Technologies Munich SE
- Telix Pharmaceuticals
- Niowave, Inc.
- SHINE Technologies
- Perspective Therapeutics
Frequently Asked Questions
What is the current market size of the Alpha Emitter market?
The market is estimated at approximately USD 1.14 Billion in 2026 and is expected to reach USD 5.42 Billion by 2034, growing at a CAGR of 18.4%.
Which isotope is driving the most growth in the Alpha Emitter market?
Actinium-225 is currently the most significant driver of future growth due to its high potency and favorable half-life for targeted alpha therapy clinical applications.
What are the primary challenges in the Alpha Emitter market?
The main challenges include the scarcity of isotope supply, complex logistics due to short half-lives, and the high cost of specialized infrastructure required for production and administration.
Which region dominates the Alpha Emitter market?
North America currently dominates the market, holding the largest share due to advanced R&D activities and a well-established nuclear medicine infrastructure.
How does Targeted Alpha Therapy (TAT) differ from traditional radiation?
TAT uses alpha particles which have a high energy and short range (micrometers), allowing for the destruction of cancer cells while causing minimal damage to the surrounding healthy tissue, unlike traditional external beam radiation.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
