Thermoformed Plastics Market
Thermoformed Plastics Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711831 | Published On : November 18, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Thermoformed Plastics Market Size
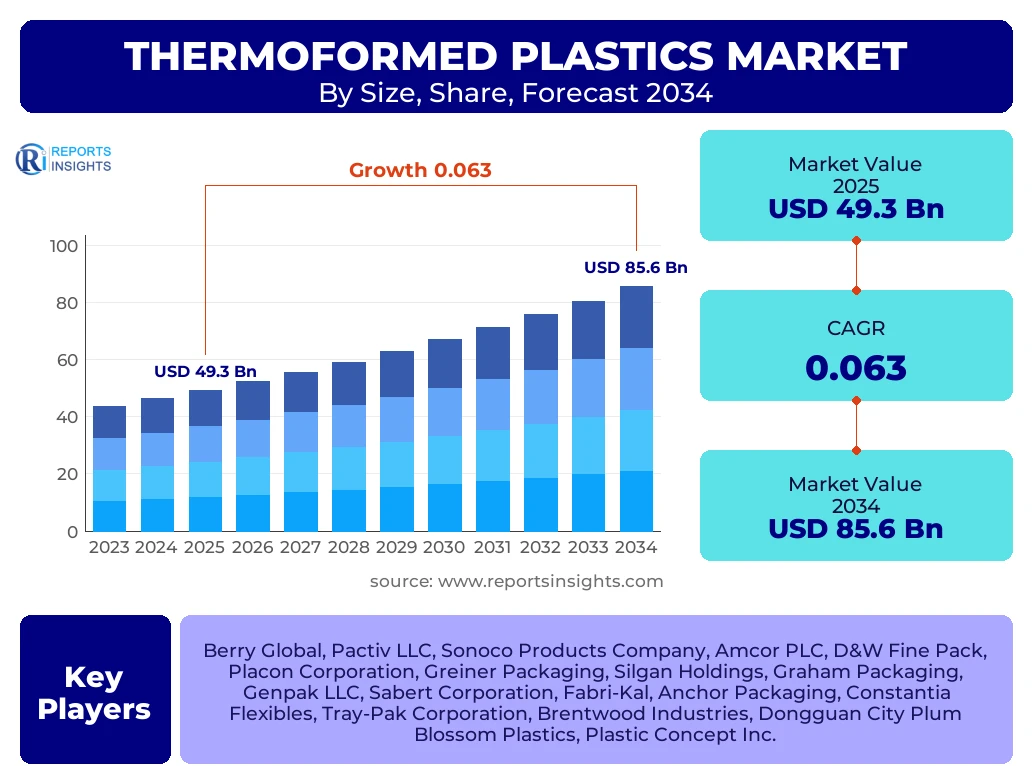
According to Reports Insights Consulting Pvt Ltd, The Thermoformed Plastics Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.3% between 2025 and 2034. The market is estimated at USD 52.4 Billion in 2026 and is projected to reach USD 85.6 Billion by the end of the forecast period in 2034.
The global thermoformed plastics market represents a critical segment of the broader polymer and packaging industries, characterized by its versatility, cost-efficiency, and adaptability across diverse industrial applications. Thermoforming, a manufacturing process where a plastic sheet is heated to a pliable forming temperature, formed to a specific shape in a mold, and trimmed to create a usable product, has seen significant technological advancements. These advancements have enabled the production of high-precision components used in everything from disposable food containers to complex automotive interiors and medical device housings. The market is currently undergoing a transformative phase driven by the integration of automation, the adoption of sustainable materials, and the increasing demand for lightweight alternatives to traditional materials like metal and glass.
In the contemporary economic landscape, the thermoformed plastics sector is bolstered by the rapid expansion of the food and beverage industry, particularly in emerging economies. The shift toward convenience-based lifestyles and the surge in online food delivery services have created a robust demand for durable, leak-proof, and aesthetic packaging solutions. Furthermore, the healthcare sector’s stringent requirements for sterile and customized packaging for surgical instruments and pharmaceuticals have positioned thermoforming as a preferred manufacturing route. As global supply chains stabilize and industrial activities intensify in the post-pandemic era, the market is poised for sustained growth, supported by a steady influx of investments in research and development aimed at improving material properties and reducing environmental footprints.
Key Thermoformed Plastics Market Trends & Insights
The Thermoformed Plastics market is increasingly defined by the transition toward a circular economy, where manufacturers are prioritizing the use of recycled resins and bio-based polymers to align with global sustainability mandates. Analysts observing the competitive landscape note that regional market dynamics are heavily influenced by regulatory shifts, particularly in Europe and North America, where single-use plastic bans are forcing a pivot toward high-performance, recyclable thermoformed solutions. Competitive benchmarking reveals that leading players are differentiating themselves through vertical integration and the adoption of twin-sheet thermoforming technologies to cater to the automotive and aerospace sectors. The convergence of digital manufacturing and smart packaging is also emerging as a pivotal trend, allowing for better traceability and consumer engagement.
- Largest Region: North America remains the dominant regional market, holding the largest value share due to an established food packaging industry and high healthcare expenditure.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR, fueled by rapid industrialization in China, India, and Southeast Asia.
- Largest Segment by Share: The Food and Beverage packaging segment continues to lead the market, accounting for over 40 percent of total revenue.
- Key Material Trend: Polyethylene Terephthalate (PET) is witnessing the highest adoption rate among materials due to its clarity and high recyclability.
- Technological Shift: Increased implementation of heavy-gauge thermoforming for industrial equipment and vehicle components is expanding the market beyond traditional packaging.
Key Takeaways Thermoformed Plastics Market Size & Forecast
The forecast for the Thermoformed Plastics market highlights a period of steady expansion driven by cross-industry demand and material innovation. Users and stakeholders frequently inquire about the long-term viability of plastic-based solutions amidst environmental concerns; the data suggests that the market’s resilience lies in the development of rPET (recycled PET) and biodegradable alternatives. The forecast indicates that while the packaging sector provides a stable foundation, the healthcare and automotive segments will act as high-growth engines. Strategic shifts toward localized manufacturing and optimized supply chains are expected to mitigate the impact of volatile raw material prices, ensuring a positive trajectory through 2034.
- Market Valuation: The total market value is set to exceed USD 85 billion by 2034, reflecting a stable upward trajectory.
- Regional Leadership: The United States and China are the primary engines of growth, collectively representing a significant portion of global demand.
- Sustainable Growth: Sustainable and compostable thermoformed plastics are expected to grow at double the rate of conventional plastics.
- Sector Performance: Medical-grade thermoforming is emerging as a high-margin niche, driven by the aging population and advancements in medical technology.
- Operational Efficiency: Advancements in thin-wall thermoforming are reducing material consumption while maintaining structural integrity, improving profit margins for manufacturers.
Thermoformed Plastics Market Drivers Analysis
The primary drivers of the Thermoformed Plastics market are rooted in the global demand for cost-effective packaging and the rising requirements for lightweight materials in transport sectors. As urbanization increases, the logistics and retail sectors are demanding packaging that offers superior protection and extended shelf life, which thermoforming provides through barrier properties and customized designs. Additionally, the shift toward electric vehicles (EVs) is pushing automotive OEMs to seek lightweight thermoformed plastic components to enhance battery efficiency and vehicle range. The expansion of the global middle class in the APAC region further accelerates the consumption of consumer goods packaged in thermoformed plastics.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Surge in Food Delivery & Takeout Services | +1.8% | Global (Strongest in APAC) | 2025 - 2034 |
| Lightweighting Trends in Automotive/EV | +1.4% | Europe & North America | 2026 - 2034 |
| Expansion of Medical Device Sector | +1.2% | USA, Germany, Japan | 2025 - 2034 |
| Growth in Organized Retail in Emerging Markets | +0.9% | India, Brazil, Indonesia | 2026 - 2030 |
Thermoformed Plastics Market Restraints Analysis
Despite strong growth prospects, the market faces significant headwinds from environmental regulations and the volatility of crude oil prices, which directly impact the cost of plastic resins. Many jurisdictions are implementing strict bans on specific single-use plastics, forcing manufacturers to overhaul their production lines or invest heavily in alternative materials. Additionally, the rising cost of energy in manufacturing hubs like Europe poses a challenge to maintain competitive pricing. The public perception of plastics as an environmental hazard also continues to pressure brands to seek non-plastic alternatives, which could potentially stifle growth in certain retail segments.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Single-Use Plastic Regulations | -1.5% | European Union, Canada | 2025 - 2034 |
| Raw Material Price Volatility (Resin Costs) | -0.8% | Global | Continuous |
| Increasing Energy Costs in Manufacturing | -0.5% | Western Europe | 2025 - 2028 |
Thermoformed Plastics Market Opportunities Analysis
The most promising opportunities in the Thermoformed Plastics market lie in the development of advanced material science, specifically regarding bioplastics and high-recycled-content resins. As consumer brands strive to meet ESG (Environmental, Social, and Governance) goals, the demand for thermoformed products that are both high-performing and eco-friendly is skyrocketing. There is also a significant opportunity in the aerospace and defense sectors for heavy-gauge, flame-retardant thermoformed panels. Furthermore, the rise of e-commerce requires specialized, durable thermoformed trays and inserts to prevent product damage during transit, creating a new and growing revenue stream for converters.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Bio-based & Compostable Polymers | +2.2% | Global (Led by Europe) | 2026 - 2034 |
| Advanced Heavy-Gauge Forming for Aerospace | +0.7% | North America, France | 2027 - 2034 |
| Smart Packaging Integration (RFID/Sensors) | +0.5% | USA, South Korea, China | 2028 - 2034 |
Thermoformed Plastics Market Challenges Impact Analysis
Manufacturers in the thermoformed plastics space must navigate complex challenges ranging from technological obsolescence to fragmented supply chains. Small and medium-sized enterprises (SMEs) often struggle with the high capital expenditure required for high-speed, automated thermoforming machinery. Additionally, the lack of standardized recycling infrastructure for complex multi-layer thermoformed films makes circularity difficult to achieve in practice. Global trade tensions and fluctuating logistics costs also complicate the sourcing of specialized resins and the export of finished goods, requiring firms to adopt more resilient and localized business models.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fragmented Global Recycling Infrastructure | -0.6% | Global | 2025 - 2030 |
| High Initial Capital Investment for Automation | -0.4% | SMEs Globally | Continuous |
| Substitution Risk from Fiber-based Packaging | -0.7% | Retail/FMCG Sector | 2025 - 2034 |
Thermoformed Plastics Market - Updated Report Scope
This report provides a comprehensive examination of the global thermoformed plastics landscape, covering material types, thermoforming processes, and end-use industries across five major geographical regions. The study integrates quantitative data with qualitative analysis to provide a holistic view of the market's evolution from 2020 through the forecast year of 2034. It highlights the impact of technological innovations, regulatory shifts, and changing consumer preferences on market dynamics, offering stakeholders actionable insights for strategic planning.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 49.3 Billion |
| Market Forecast in 2034 | USD 85.6 Billion |
| Growth Rate | 6.3% CAGR |
| Number of Pages | 248 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Berry Global, Pactiv LLC, Sonoco Products Company, Amcor PLC, D&W Fine Pack, Placon Corporation, Greiner Packaging, Silgan Holdings, Graham Packaging, Genpak LLC, Sabert Corporation, Fabri-Kal, Anchor Packaging, Constantia Flexibles, Tray-Pak Corporation, Brentwood Industries, Dongguan City Plum Blossom Plastics, Plastic Concept Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Thermoformed Plastics market is segmented based on material chemistry, the specific thermoforming process employed, and the end-use industry. This multifaceted segmentation allows for a granular understanding of where value is being created and which technologies are becoming obsolete. For instance, while thin-gauge vacuum forming remains the standard for disposable retail packaging, heavy-gauge pressure forming is gaining traction in the industrial sector for its ability to create robust, structural components with aesthetic finishes equivalent to injection molding but at lower tooling costs.
- By Material: Polyethylene Terephthalate (PET) is the leading material segment, prized for its transparency and recyclability in food applications. Polypropylene (PP) follows closely, dominated by its high heat resistance suitable for microwaveable containers.
- By Process: Vacuum forming is the most widely utilized process due to its simplicity and cost-effectiveness for large parts. Pressure forming is the fastest-growing sub-segment, offering higher detail and tighter tolerances for complex designs.
- By Application: Food and Beverage remains the primary application, though the Healthcare segment is expected to see the highest value-per-unit growth due to the stringent quality requirements for medical trays and blister packs.
- By Product Type: Trays and Lids constitute the largest volume share, while containers and clamshells are seeing increased adoption in the fresh produce and electronics sectors.
Regional Highlights
- North America: The largest market share holder, driven by the presence of major packaging conglomerates and a high consumption of processed and convenience foods. The United States is the primary contributor to this region’s dominance.
- Europe: The region is the leader in sustainable practices and regulatory frameworks. Countries like Germany and France are at the forefront of adopting bioplastics and advanced recycling technologies within the thermoforming industry.
- Asia-Pacific: The fastest-growing region, with China and India serving as major manufacturing hubs. Rapid urbanization, a growing middle class, and the expansion of the pharmaceutical industry are key growth catalysts here.
- Latin America: Expected to show moderate growth, with Brazil and Mexico seeing increased investments in the automotive and food packaging sectors.
- Middle East & Africa: A developing market where the focus is shifting toward diversifying industrial bases, leading to increased demand for thermoformed plastics in construction and consumer goods.

Top Key Players
The market research report includes a detailed profile of leading top-wise companies in the Thermoformed Plastics Market. These organizations are categorized by their market reach, product innovation, and strategic mergers and acquisitions.
- Berry Global
- Pactiv LLC
- Sonoco Products Company
- Amcor PLC
- D&W Fine Pack
- Placon Corporation
- Greiner Packaging
- Silgan Holdings
- Graham Packaging
- Genpak LLC
- Sabert Corporation
- Fabri-Kal
- Anchor Packaging
- Constantia Flexibles
- Tray-Pak Corporation
- Brentwood Industries
- Dongguan City Plum Blossom Plastics
- Plastic Concept Inc.
- Tegrant Corporation
- Clear Lam Packaging
Frequently Asked Questions
What are the main advantages of thermoformed plastics over injection molding?
Thermoforming offers significantly lower tooling costs and faster lead times compared to injection molding, making it ideal for large-part production, prototyping, and small to medium production runs. It also allows for thinner walls and lightweighting, which is critical for packaging and automotive applications.
Which materials are most commonly used in the thermoforming process?
The most common materials include Polyethylene Terephthalate (PET), Polypropylene (PP), High-Impact Polystyrene (HIPS), and Acrylonitrile Butadiene Styrene (ABS). The choice depends on the application, with PET leading in food packaging and ABS favored for industrial and automotive parts.
How is the thermoformed plastics market addressing environmental sustainability?
The market is shifting toward a circular economy by increasing the use of Post-Consumer Recycled (PCR) resins, developing biodegradable and compostable bioplastics, and improving the design of packaging to ensure it is 100 percent recyclable. Companies are also investing in carbon-neutral manufacturing processes.
What is the impact of COVID-19 and subsequent supply chain shifts on this market?
Initially, the pandemic surged demand for medical packaging and food delivery containers. Subsequently, it led to a shift toward localized supply chains and increased investment in automation to mitigate labor shortages and transport disruptions, trends that continue to influence the market today.
Which end-use industry is expected to drive the most growth through 2034?
While food packaging remains the largest volume driver, the healthcare and medical device sectors are expected to drive the highest value growth due to the increasing demand for customized, sterile packaging and the global expansion of healthcare infrastructure.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
