Therapeutic Respiratory Devices Market
Therapeutic Respiratory Devices Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711149 | Published On : October 12, 2026 |
Format : 


 | Author : Erika Grotto
Therapeutic Respiratory Devices Market Size
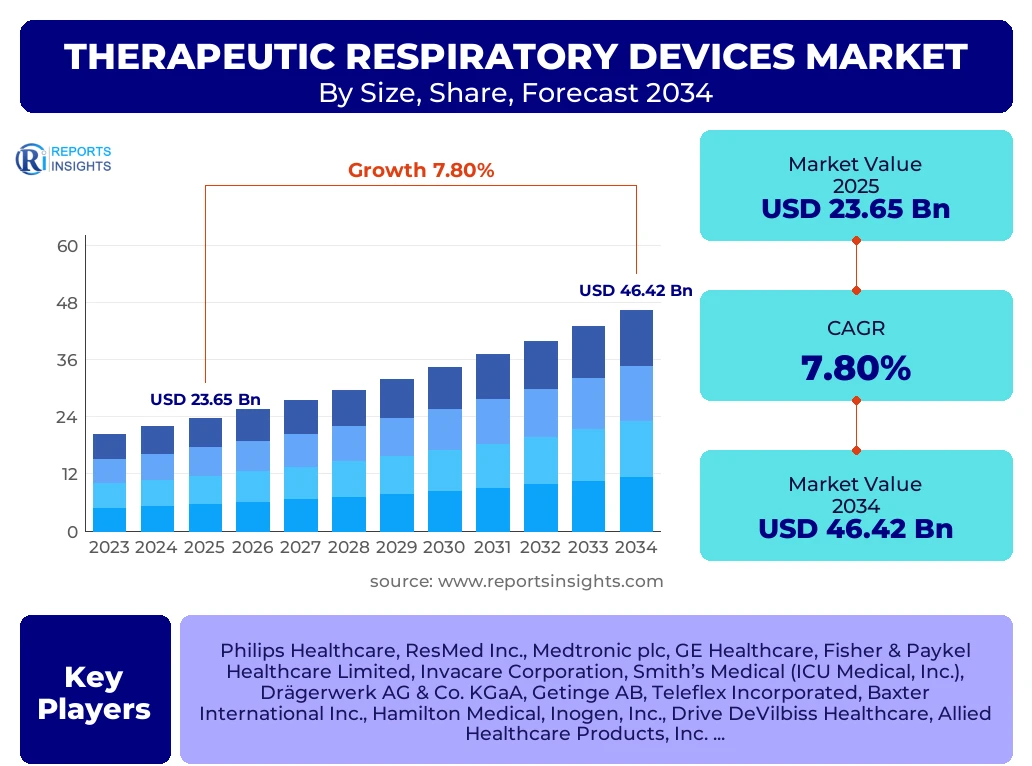
According to Reports Insights Consulting Pvt Ltd, The Therapeutic Respiratory Devices Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.8% between 2025 and 2034. The market is estimated at USD 25.50 Billion in 2026 and is projected to reach USD 46.42 Billion by the end of the forecast period in 2034.
The global therapeutic respiratory devices market represents a critical segment of the healthcare technology sector, driven by the increasing prevalence of chronic respiratory diseases such as Chronic Obstructive Pulmonary Disease (COPD), asthma, and obstructive sleep apnea (OSA). As the global population ages and environmental factors like air pollution continue to degrade lung health, the demand for sophisticated respiratory intervention tools has surged. These devices, ranging from advanced mechanical ventilators to portable oxygen concentrators and smart inhalers, are becoming more integrated with digital health platforms, allowing for real-time monitoring and improved patient compliance in both clinical and homecare settings.
Market dynamics are currently shaped by a significant shift toward decentralized care. There is a growing preference for portable and user-friendly devices that allow patients to manage chronic conditions outside of high-cost hospital environments. This transition is supported by favorable reimbursement policies in developed economies and the rapid expansion of healthcare infrastructure in emerging markets. Technological advancements, such as the development of ultra-quiet motors for PAP devices and high-frequency oscillatory ventilators, are further propelling market growth by enhancing patient comfort and clinical outcomes.
Key Therapeutic Respiratory Devices Market Trends & Insights
The therapeutic respiratory devices market is undergoing a transformative phase characterized by the convergence of medical hardware and data analytics. A primary trend is the adoption of the Internet of Medical Things (IoMT), where respiratory devices are equipped with sensors to track usage patterns and physiological data. This connectivity facilitates predictive maintenance for healthcare providers and personalized therapy adjustments for patients. Furthermore, there is a notable trend toward the miniaturization of oxygen therapy equipment, enabling greater mobility for patients with chronic respiratory failure. Competitive benchmarking reveals that leading companies are increasingly focusing on strategic partnerships with telehealth providers to create end-to-end respiratory management ecosystems.
- Largest Region: North America remains the dominant market due to high healthcare expenditure and a large patient pool suffering from sleep apnea and COPD.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR, fueled by rising pollution levels, increasing tobacco consumption, and rapid modernization of healthcare facilities in China and India.
- Largest Product Segment: Positive Airway Pressure (PAP) devices currently hold the largest market share, driven by the massive undiagnosed population of sleep apnea patients globally.
- Leading End-User: Hospitals and clinics remain the primary revenue generators, though the homecare segment is the fastest-growing category.
Key Takeaways Therapeutic Respiratory Devices Market Size & Forecast
The long-term outlook for the therapeutic respiratory devices market is exceptionally positive, underpinned by a structural shift in global demographics and the lingering long-term respiratory effects observed in post-pandemic populations. Investors and stakeholders are increasingly focusing on value-based care models where device efficacy is measured by a reduction in hospital readmission rates. The forecast period between 2025 and 2034 will likely see a surge in the adoption of non-invasive ventilation (NIV) as a primary treatment modality for acute respiratory failure, reducing the risks associated with invasive procedures.
- Global Prevalence: The rising global incidence of asthma, currently affecting over 300 million people, serves as a fundamental floor for market demand.
- Technological Integration: Smart inhalers and digital nebulizers are expected to witness a double-digit growth rate within the sub-segments as medication adherence becomes a clinical priority.
- Emerging Markets: Brazil, Mexico, and Southeast Asian nations are emerging as high-potential hubs for low-cost respiratory device manufacturing and distribution.
- Homecare Transition: The shift from acute care to chronic home management is the single most significant driver for the portable oxygen concentrator market.
Therapeutic Respiratory Devices Market Drivers Analysis
The primary catalysts for market expansion include the global increase in geriatric populations who are more susceptible to respiratory distress and the deteriorating air quality in urban centers. Additionally, the increasing awareness of sleep disorders and the availability of home-based diagnostic kits are funneling more patients into the therapeutic pipeline for PAP devices and oxygen therapy.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Prevalence of COPD and Asthma | +2.1% | Global | 2025 - 2034 |
| Expansion of Home Healthcare Settings | +1.8% | North America & Europe | 2025 - 2030 |
| Advancements in Portable Oxygen Technology | +1.5% | United States & Japan | 2026 - 2034 |
| Government Initiatives for Respiratory Care | +1.2% | China & India | 2025 - 2032 |
Therapeutic Respiratory Devices Market Restraints Analysis
Growth is partially tempered by the high cost of advanced therapeutic equipment, which remains prohibitive for large segments of the population in low-income countries. Furthermore, the complex regulatory landscape and the requirement for clinical evidence for new device approvals can delay the time-to-market for innovative respiratory solutions.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Advanced Ventilators | -1.1% | LAMEA & Africa | 2025 - 2034 |
| Strict Regulatory Approval Processes | -0.8% | European Union (MDR) | 2025 - 2028 |
| Limited Reimbursement in Emerging Markets | -0.6% | South East Asia | 2026 - 2031 |
Therapeutic Respiratory Devices Market Opportunities Analysis
Significant opportunities lie in the integration of Artificial Intelligence for personalized ventilation settings and the development of eco-friendly, recyclable respiratory consumables. The expansion of e-commerce platforms for medical device distribution also presents a massive opportunity to reach underserved rural populations in developing economies.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI-Driven Respiratory Monitoring | +1.9% | Global | 2027 - 2034 |
| Growth in Tele-Respiratory Services | +1.4% | United States & UK | 2025 - 2034 |
| Miniaturized Wearable Nebulizers | +1.2% | Germany & South Korea | 2028 - 2034 |
Therapeutic Respiratory Devices Market Challenges Impact Analysis
Key challenges include maintaining supply chain resilience for critical electronic components used in ventilators and PAP machines. Additionally, the threat of cybersecurity breaches in connected respiratory devices poses a significant risk to patient safety and data privacy, requiring robust defensive investments from manufacturers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Risks in Connected Devices | -0.7% | North America & Europe | 2025 - 2034 |
| Shortage of Skilled Respiratory Therapists | -0.5% | Global | 2025 - 2030 |
| Supply Chain Volatility for Semiconductors | -0.4% | Global | 2025 - 2027 |
Therapeutic Respiratory Devices Market - Updated Report Scope
This report provides a comprehensive analysis of the therapeutic respiratory devices market, covering technological iterations, clinical applications, and competitive landscapes. The scope includes a detailed breakdown of capital equipment and associated consumables, providing a 360-degree view of the revenue streams within the industry from 2020 through the forecast end-point of 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 23.65 Billion |
| Market Forecast in 2034 | USD 46.42 Billion |
| Growth Rate | 7.8% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Philips Healthcare, ResMed Inc., Medtronic plc, GE Healthcare, Fisher & Paykel Healthcare Limited, Invacare Corporation, Smith’s Medical (ICU Medical, Inc.), Drägerwerk AG & Co. KGaA, Getinge AB, Teleflex Incorporated, Baxter International Inc., Hamilton Medical, Inogen, Inc., Drive DeVilbiss Healthcare, Allied Healthcare Products, Inc., Precision Medical, Inc., Masimo Corporation, Viemed Healthcare, Inc., Breas Medical, Vyaire Medical. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The therapeutic respiratory devices market is segmented into several critical categories that define its clinical utility. The Product segment is the most diverse, with PAP devices leading in volume due to the high prevalence of obstructive sleep apnea. Oxygen concentrators are witnessing a shift from stationary units to portable models, catering to the active lifestyles of elderly patients. Ventilators are bifurcated into invasive and non-invasive categories, with non-invasive models gaining traction for early-stage respiratory intervention. Inhalers and nebulizers remain the standard of care for asthma and COPD, with increasing focus on mesh technology for higher drug delivery efficiency.
- Positive Airway Pressure (PAP) Devices: Includes CPAP, BiPAP, and APAP units primarily used for sleep-disordered breathing.
- Oxygen Concentrators: Covers both fixed hospital-grade units and lightweight portable oxygen concentrators (POCs).
- Ventilators: Critical care ventilators, transport ventilators, and neonatal ventilators for both invasive and non-invasive use.
- Nebulizers: Comprising jet, ultrasonic, and vibrating mesh nebulizers for aerosol therapy.
- Inhalers: Divided into Metered Dose Inhalers (MDIs) and Dry Powder Inhalers (DPIs).
- Humidifiers: Essential for maintaining airway moisture during oxygen therapy and mechanical ventilation.
- End-Use Hospitals: High-volume procurement of ventilators and oxygen delivery systems.
- End-Use Homecare: Rapidly growing segment for CPAP machines and portable oxygen therapy.
Regional Highlights
North America currently holds the largest market share, estimated at approximately 38% of the global market. This dominance is attributed to a sophisticated healthcare infrastructure, high awareness regarding respiratory health, and a robust reimbursement framework. The United States is the primary contributor, where the high incidence of obesity correlates with rising sleep apnea cases, driving the PAP device market.
The Asia-Pacific region is the most dynamic, expected to grow at the fastest CAGR during the forecast period. Rapid industrialization and subsequent air pollution in China and India have led to a surge in chronic respiratory conditions. Furthermore, the expansion of private healthcare and government insurance schemes in these nations is making therapeutic respiratory devices more accessible to the middle-class population. Europe maintains a steady market presence, with Germany and the UK leading in the adoption of homecare respiratory technologies and smart monitoring systems.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Therapeutic Respiratory Devices Market.- Philips Healthcare
- ResMed Inc.
- Medtronic plc
- GE Healthcare
- Fisher & Paykel Healthcare Limited
- Invacare Corporation
- Smith’s Medical (ICU Medical, Inc.)
- Drägerwerk AG & Co. KGaA
- Getinge AB
- Teleflex Incorporated
- Baxter International Inc.
- Hamilton Medical
- Inogen, Inc.
- Drive DeVilbiss Healthcare
- Allied Healthcare Products, Inc.
- Precision Medical, Inc.
- Masimo Corporation
- Viemed Healthcare, Inc.
- Breas Medical
- Vyaire Medical
Frequently Asked Questions
What is the current market size and forecast for the therapeutic respiratory devices market?
The market is estimated at USD 25.50 Billion in 2026 and is projected to reach USD 46.42 Billion by 2034, growing at a CAGR of 7.8%.
Which segment is expected to lead the therapeutic respiratory devices market growth?
The Positive Airway Pressure (PAP) devices segment leads in market share, while the homecare end-use segment is expected to show the fastest growth due to the shift toward outpatient chronic disease management.
What are the primary drivers for the Asia-Pacific respiratory devices market?
Growth in the APAC region is primarily driven by rising pollution levels, high smoking prevalence, increasing geriatric populations, and significant government investment in healthcare infrastructure.
How is technology influencing the therapeutic respiratory devices industry?
Technological advancements such as IoMT connectivity, AI-driven diagnostics, and the miniaturization of portable oxygen concentrators are enhancing patient compliance and clinical outcomes.
What are the main challenges facing manufacturers in this market?
Key challenges include navigating stringent regulatory approval pathways, ensuring data security for connected devices, and managing supply chain risks for specialized electronic components.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
