Intracranial Aneurysm Market
Intracranial Aneurysm Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710977 | Published On : September 24, 2026 |
Format : 


 | Author : Erika Grotto
Intracranial Aneurysm Market Size
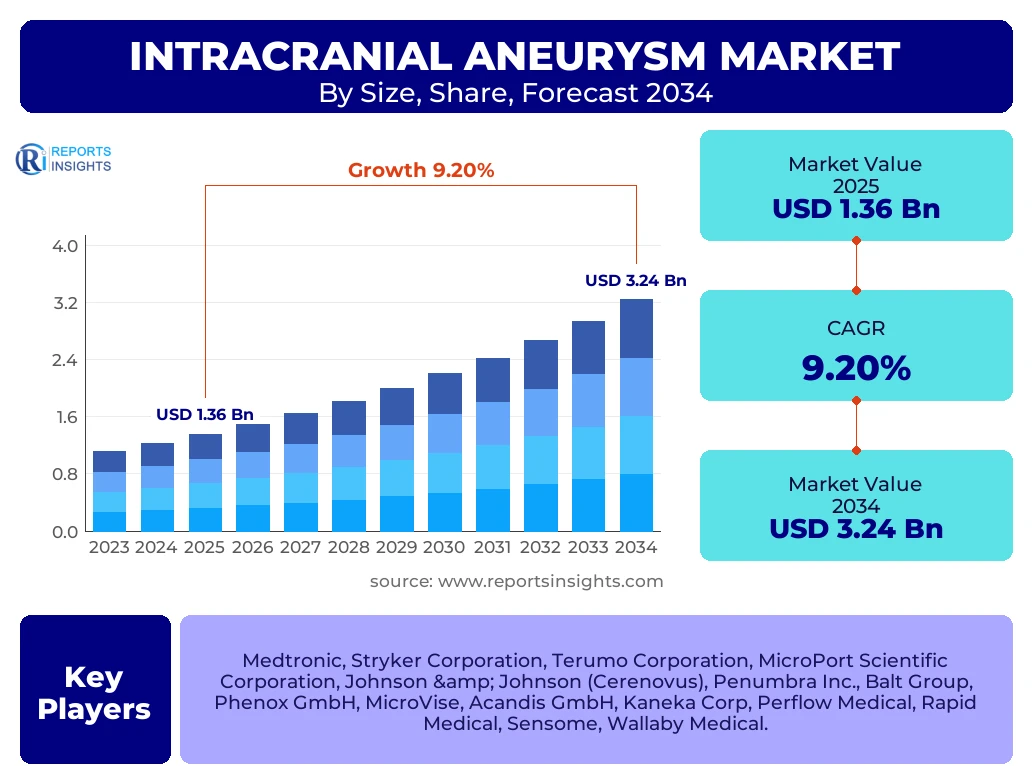
According to Reports Insights Consulting Pvt Ltd, The Intracranial Aneurysm Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 9.2% between 2026 and 2034. The market is estimated at USD 1.48 Billion in 2026 and is projected to reach USD 3.24 Billion by the end of the forecast period in 2034.
The global intracranial aneurysm market is witnessing a transformative phase, driven by a confluence of demographic shifts and technological breakthroughs in neurovascular interventions. As the global population ages, the prevalence of cerebrovascular conditions, including saccular and fusiform aneurysms, has seen a steady incline. This growth is further bolstered by the rapid transition from traditional open-skull surgical clipping to minimally invasive endovascular procedures. These modern techniques, which utilize catheters to deliver coils, stents, or flow diverters, offer significantly reduced recovery times, lower risk of perioperative complications, and higher patient throughput for healthcare facilities. Furthermore, the integration of high-resolution diagnostic imaging, such as Computed Tomography Angiography (CTA) and Magnetic Resonance Angiography (MRA), allows for the early detection of asymptomatic aneurysms, expanding the pool of treatable patients.
Market dynamics are also heavily influenced by the increasing healthcare expenditure in emerging economies and the favorable reimbursement landscape in developed regions like North America and Western Europe. Innovation in device design, such as the development of bioresorbable polymers and surface-modified embolic coils, is enhancing long-term occlusion rates and reducing the incidence of aneurysm recurrence. Stakeholders in the market are increasingly focusing on strategic collaborations and regulatory approvals for next-generation intrasaccular flow disruption devices, which represent a significant leap in the treatment of wide-neck complex aneurysms. Consequently, the market is poised for robust expansion as these advanced therapies become the standard of care globally.
Key Intracranial Aneurysm Market Trends & Insights
The market is currently shaped by the aggressive adoption of Artificial Intelligence (AI) in neuro-imaging for rapid aneurysm screening and the miniaturization of neurovascular devices to access distal cerebral vessels. Analysis of regional data indicates that while North America remains the dominant revenue contributor, the Asia-Pacific region is emerging as a high-growth hub due to improving medical infrastructure and a rising incidence of lifestyle-induced hypertension. Competitive benchmarking reveals that leading players are prioritizing the expansion of their flow diverter portfolios to address the unmet needs of patients with giant or non-clippable aneurysms.
- Largest Region: North America continues to hold the largest market share, driven by advanced neurosurgical facilities and high awareness regarding stroke prevention.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR due to increasing geriatric populations in China and Japan and expanding access to neuro-interventional procedures.
- Dominant Segment by Type: Saccular aneurysms represent the largest segment in terms of market share, accounting for over 80% of diagnosed cases.
- Leading Procedure Segment: Endovascular coiling remains the dominant treatment modality, though flow diversion is seeing the fastest adoption rate.
- Technological Integration: The use of 3D printing for patient-specific pre-surgical planning is a rising trend among top-tier neurological centers.
Key Takeaways Intracranial Aneurysm Market Size & Forecast
The global outlook for the intracranial aneurysm market reflects a clear trajectory toward minimally invasive excellence and precision medicine. Investors and healthcare providers are focusing on the shift from reactive treatment of ruptured aneurysms to the proactive management of unruptured cases, facilitated by AI-driven risk assessment tools. The market forecast is underpinned by the increasing volume of neuro-interventional procedures and the continuous refinement of embolic device safety profiles, ensuring long-term market sustainability through 2034.
- Primary Growth Engine: The transition from surgical clipping to endovascular therapies is the primary driver of market value, with endovascular devices commanding higher price points and repeat usage.
- Strategic Market Focus: Leading companies are targeting the wide-neck aneurysm segment, which was historically difficult to treat, using novel intrasaccular flow disruptors.
- Regional Market Anchor: The United States remains the critical market anchor, characterized by high reimbursement rates for neurovascular implants.
- Regulatory Impact: Expedited FDA and CE Mark approvals for neuro-thrombectomy and aneurysm repair devices are accelerating the time-to-market for innovative startups.
- Future Market Catalyst: The development of robotic-assisted neurovascular surgery is expected to emerge as a major market catalyst toward the end of the forecast period.
Intracranial Aneurysm Market Drivers Analysis
The sustained expansion of the intracranial aneurysm market is fueled by a combination of clinical advancements and macro-environmental factors. Central to this growth is the rising global incidence of hypertension and smoking-related vascular diseases, which are primary risk factors for aneurysm formation and rupture. Additionally, the increasing availability of specialized neuro-interventional suites (Cath Labs) in mid-sized hospitals is democratizing access to advanced treatments.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Technological Shift to Endovascular Procedures | +3.2% | Global (High in North America) | 2025 - 2034 |
| Rising Geriatric Population and Vascular Diseases | +2.5% | Japan, Western Europe, China | 2025 - 2034 |
| Improved Diagnostic Imaging Capabilities | +1.8% | Germany, US, South Korea | 2026 - 2030 |
| Increasing Healthcare Spending in Emerging Markets | +1.7% | India, Brazil, Southeast Asia | 2027 - 2034 |
Intracranial Aneurysm Market Restraints Analysis
Despite the positive growth outlook, several bottlenecks hinder the full realization of market potential. High costs associated with endovascular implants and the specialized equipment required for these procedures remain a significant barrier in low-income regions. Furthermore, the rigorous clinical trial requirements and long gestation periods for regulatory approval can slow down the introduction of disruptive technologies.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Specialized Neuro-implants | -1.5% | Latin America, Africa, SE Asia | 2025 - 2034 |
| Shortage of Skilled Interventional Neuro-surgeons | -1.2% | Global (Rural Regions) | 2025 - 2030 |
| Stringent Regulatory Pathways for Class III Devices | -0.8% | European Union (MDR), USA | 2025 - 2028 |
Intracranial Aneurysm Market Opportunities Analysis
The evolution of the neurovascular landscape presents numerous untapped opportunities for manufacturers and service providers. The integration of AI for predictive modeling of aneurysm rupture risk is a burgeoning field that could lead to higher intervention rates for unruptured cases. Moreover, the development of cost-effective embolic devices tailored for emerging markets offers a significant pathway for volume-based growth.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| AI-Driven Rupture Risk Assessment Tools | +2.1% | USA, UK, Israel | 2026 - 2034 |
| Expansion into Tier-2 and Tier-3 Cities | +1.9% | China, India | 2027 - 2034 |
| Development of Bio-absorbable Flow Diverters | +1.4% | Germany, Switzerland, Japan | 2028 - 2034 |
Intracranial Aneurysm Market Challenges Impact Analysis
Manufacturers face significant challenges in maintaining profit margins amidst increasing pricing pressure from group purchasing organizations (GPOs) and public health insurance systems. Additionally, the technical complexity of treating distal and small-vessel aneurysms requires continuous R&D investment to ensure device deliverability without causing vessel trauma.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Pricing Pressure and Healthcare Cost Containment | -1.1% | European Union, Canada | 2025 - 2034 |
| Device-related Complications (Thrombosis) | -0.9% | Global Clinical Setting | 2025 - 2030 |
| Supply Chain Disruptions for Rare Earth Metals | -0.5% | Global Manufacturing Hubs | 2025 - 2027 |
Intracranial Aneurysm Market - Updated Report Scope
This comprehensive market report provides a deep-dive analysis into the global intracranial aneurysm ecosystem, covering hardware, software, and procedural trends. It encompasses a multi-dimensional view of the market, including granular segmentation by product type, end-user settings, and geographic performance. The scope is designed to provide actionable intelligence for medical device manufacturers, clinical researchers, and institutional investors seeking to capitalize on neurovascular innovations.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.36 Billion |
| Market Forecast in 2034 | USD 3.24 Billion |
| Growth Rate | 9.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Medtronic, Stryker Corporation, Terumo Corporation, MicroPort Scientific Corporation, Johnson & Johnson (Cerenovus), Penumbra Inc., Balt Group, Phenox GmbH, MicroVise, Acandis GmbH, Kaneka Corp, Perflow Medical, Rapid Medical, Sensome, Wallaby Medical. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the intracranial aneurysm market reflects the diverse clinical approaches required to manage various types of vascular lesions. The primary division is by product category, where embolic coils continue to hold the largest volume share, although flow diverters are rapidly gaining ground due to their efficacy in treating wide-neck and giant aneurysms. Secondary segmentation by end-user highlights the dominance of large-scale hospitals, which possess the requisite infrastructure and multidisciplinary teams (neurologists, radiologists, and surgeons) to perform complex neuro-interventions. However, specialized neurological institutes are seeing an increase in patient preference due to higher success rates and specialized post-operative care.
- By Type:
- Saccular Aneurysm (Berry Aneurysm)
- Fusiform Aneurysm
- Mycotic Aneurysm
- By Product:
- Embolic Coils (Platinum and Hydrogel)
- Flow Diverters
- Neurovascular Stents
- Intrasaccular Devices
- Liquid Embolic Agents
- Catheters and Guidewires
- By Procedure:
- Endovascular Coiling
- Surgical Clipping
- Flow Diversion
- Parent Vessel Occlusion
- By End-User:
- Hospitals and Trauma Centers
- Ambulatory Surgical Centers (ASCs)
- Specialized Neurological Clinics
Regional Highlights
North America currently serves as the epicenter of the intracranial aneurysm market, accounting for approximately 42% of the global revenue. This dominance is attributed to a highly sophisticated healthcare system, early adoption of flow-diverter technology, and a high volume of unruptured aneurysm screenings. Within the region, the United States is the primary contributor, supported by strong reimbursement policies for Class III medical devices and a dense network of certified stroke centers. Europe follows closely, with Germany, France, and the UK leading the market through significant investments in neurovascular research and clinical trials.
- North America: Largest market share; leader in R&D and new product launches; high prevalence of stroke risk factors.
- Europe: Mature market with steady growth; strong focus on long-term clinical data and patient safety; Germany is the regional hub for neurovascular manufacturing.
- Asia-Pacific: Fastest-growing region; CAGR exceeding 10.5%; massive potential in China and India; rising medical tourism in Thailand and South Korea for neurological procedures.
- Latin America: Developing market; growth driven by Brazil and Mexico; increasing government initiatives to modernize neuro-trauma centers.
- Middle East & Africa: Emerging market; growth concentrated in UAE, Saudi Arabia, and South Africa; focus on establishing specialized neuro-centers of excellence.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Intracranial Aneurysm Market.- Medtronic (Ireland)
- Stryker Corporation (USA)
- Terumo Corporation (Japan)
- MicroPort Scientific Corporation (China)
- Johnson & Johnson / Cerenovus (USA)
- Penumbra, Inc. (USA)
- Balt Group (France)
- Phenox GmbH (Germany)
- Acandis GmbH (Germany)
- Kaneka Corporation (Japan)
- MicroVise (USA)
- Rapid Medical (Israel)
- Perflow Medical (Israel)
- Sensome (France)
- Wallaby Medical (China)
- InspireMD (Israel)
- Integra LifeSciences (USA)
Frequently Asked Questions
Analyze common user questions about the Intracranial Aneurysm market and generate a concise list of summarized FAQs reflecting key topics and concerns.
What is driving the shift from surgical clipping to endovascular coiling?
The shift is primarily driven by the minimally invasive nature of endovascular coiling, which results in shorter hospital stays, less post-operative pain, and reduced risk of infections compared to open-skull surgery. Advancements in catheter technology and embolic materials have also made endovascular techniques safer and more effective for a wider variety of aneurysm types.
How is AI impacting the intracranial aneurysm market?
AI is significantly enhancing the market by improving the speed and accuracy of aneurysm detection on radiological scans. AI algorithms can identify small aneurysms that might be missed by the human eye and can provide predictive analytics regarding the probability of a rupture, helping surgeons prioritize high-risk patients for intervention.
Which region offers the most growth potential for neurovascular device manufacturers?
The Asia-Pacific region offers the highest growth potential. This is due to a combination of a massive, aging population base, increasing healthcare spending, and a growing number of trained neuro-interventionalists in countries like China, India, and Japan. Governments in these regions are also investing heavily in stroke-ready hospital infrastructure.
What are the key technical challenges in treating wide-neck aneurysms?
Wide-neck aneurysms are challenging because standard coils can easily herniate into the parent vessel, potentially causing a stroke. This has led to the development of flow diverters and intrasaccular devices like the WEB (Woven EndoBridge), which provide a scaffold to keep the treatment inside the aneurysm sac and promote healing of the vessel wall.
What is the outlook for the intracranial aneurysm market through 2034?
The outlook is highly positive, with a projected market value exceeding USD 3.2 Billion by 2034. Growth will be sustained by continuous technological innovations, such as bioresorbable implants and robotic-assisted delivery systems, alongside a global increase in screening programs for cerebrovascular diseases.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted