Hospital Emergency Department Market
Hospital Emergency Department Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711477 | Published On : November 03, 2026 |
Format : 


 | Author : Erika Grotto
Hospital Emergency Department Market Size
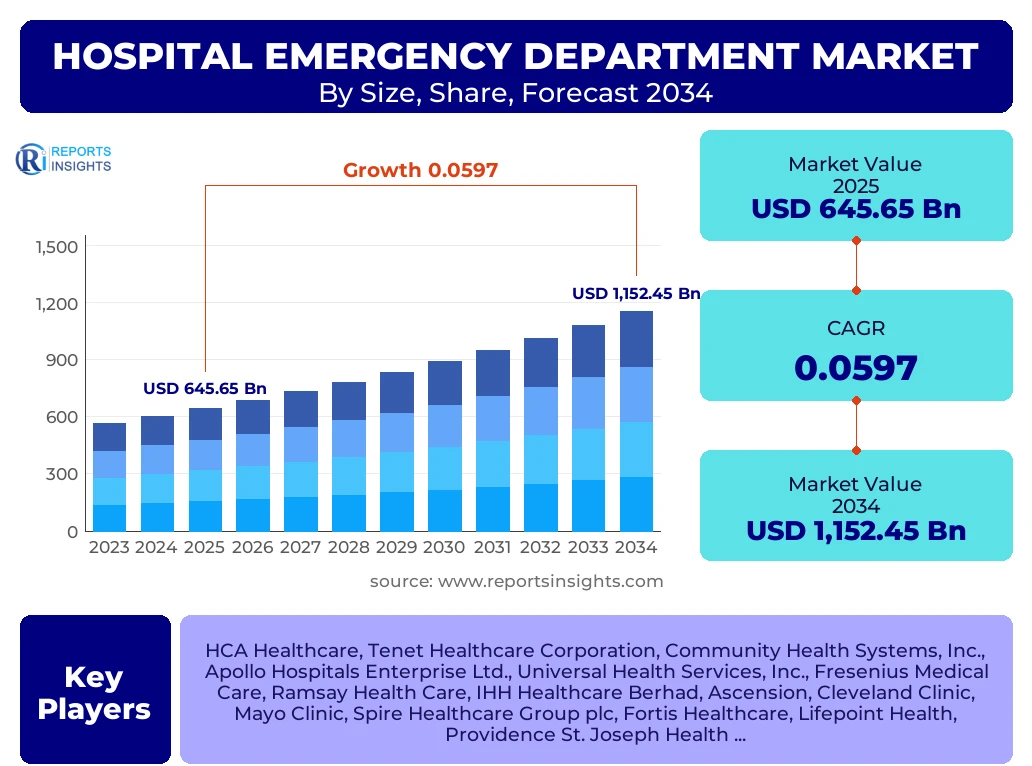
According to Reports Insights Consulting Pvt Ltd, The Hospital Emergency Department Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.97% between 2025 and 2034. The market is estimated at USD 684.20 Billion in 2026 and is projected to reach USD 1,152.45 Billion by the end of the forecast period in 2034.
Key Hospital Emergency Department Market Trends & Insights
The global landscape for hospital emergency departments (EDs) is undergoing a significant paradigm shift, transitioning from traditional reactive care models to data-driven, proactive intervention frameworks. Analysts observe that the integration of Artificial Intelligence (AI) and Machine Learning (ML) is no longer a futuristic concept but a functional reality in high-acuity settings. These technologies are being deployed for predictive triaging, allowing clinicians to identify deteriorating patients before clinical symptoms become overt. Furthermore, the rise of "Hospital at Home" models and the expansion of urgent care centers are redefining the ED's role, forcing departments to focus on higher acuity cases while offloading low-severity visits to secondary facilities. This structural change is optimizing resource allocation and reducing the chronic issue of "ED boarding," which has historically impacted patient outcomes and operational efficiency.
Regional dynamics play a crucial role in shaping market evolution, with North America currently maintaining a dominant position due to high healthcare expenditure and early adoption of advanced medical informatics. However, the Asia-Pacific region is emerging as the fastest-growing corridor, driven by massive infrastructure investments in China and India and an escalating burden of chronic respiratory and cardiovascular conditions. Competitive benchmarking reveals that leading hospital networks are increasingly prioritizing the digitization of patient workflows. By implementing sophisticated Electronic Health Record (EHR) integrations and real-time location systems (RTLS), facilities are achieving notable reductions in "door-to-balloon" and "door-to-needle" times, which are critical metrics for cardiac and stroke care. This trend toward hyper-efficiency is a primary differentiator for market leaders seeking to capture greater market share in an increasingly value-based reimbursement environment.
- Largest Region: North America remains the primary revenue contributor, supported by a robust private healthcare ecosystem and advanced trauma care infrastructure.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR, fueled by rapid urbanization, rising middle-class healthcare demand, and government-led hospital expansion projects.
- Largest Segment by Type: The Adult/Geriatric patient segment holds the majority share, directly correlating with the global demographic shift toward an aging population with multiple comorbidities.
- Dominant Service Category: Diagnostic and Imaging services represent the largest value-based segment within the ED, as comprehensive workups become standard protocol for complex admissions.
Key Takeaways Hospital Emergency Department Market Size & Forecast
The trajectory of the Hospital Emergency Department market through 2034 reflects a steady upward momentum, underpinned by the unavoidable reality of aging global demographics and the increasing frequency of lifestyle-induced acute medical emergencies. Financial forecasts indicate that while volume growth in patient visits may stabilize in developed nations due to the rise of alternative care sites, the "value per visit" is expected to climb. This is attributed to the higher complexity of cases reaching the ED and the intensive use of advanced diagnostics and specialized interventions. Stakeholders are shifting their focus toward operational resilience, investing heavily in scalable modular ED designs and interoperable software solutions that can handle surge capacity during public health crises or mass casualty events.
- Leading Country: The United States continues to lead in per-capita ED spending and technological implementation, particularly in the adoption of AI-driven clinical decision support tools.
- Market Stability: The essential nature of emergency services provides a recession-proof quality to this market, ensuring consistent capital flow despite broader economic volatility.
- Infrastructure Evolution: There is a marked trend toward the development of standalone emergency departments (SEDs) which offer high-level care in suburban areas, expanding the geographic footprint of major hospital brands.
- Technological Integration: Interoperability between pre-hospital EMS data and hospital ED systems is identified as a critical growth lever for improving survival rates in "golden hour" trauma cases.
Hospital Emergency Department Market Drivers Analysis
The primary catalysts for growth in the hospital emergency department sector include a multi-faceted combination of demographic shifts, technological leaps, and evolving patient expectations. As the global population over 65 expands, the incidence of acute exacerbations of chronic illnesses like COPD, heart failure, and diabetes increases, naturally funneling more high-acuity patients into emergency systems. Simultaneously, the rapid advancement of point-of-care testing (POCT) allows for near-instantaneous laboratory results, shortening the decision-making cycle and increasing the volume of patients a department can treat within a 24-hour cycle. Furthermore, the rising global incidence of road traffic accidents and workplace injuries in developing economies continues to necessitate the expansion of specialized trauma units within emergency departments.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Aging Global Demographics | +1.8% | Global (High in Europe/Japan) | 2025 - 2034 |
| AI & Predictive Analytics Adoption | +1.4% | North America & Western Europe | 2026 - 2034 |
| Expansion of Trauma Care in EM | +1.2% | Asia-Pacific & Latin America | 2025 - 2030 |
| Point-of-Care Diagnostic Advancements | +0.9% | Global | 2025 - 2034 |
Hospital Emergency Department Market Restraints Analysis
Despite strong growth drivers, the market faces significant headwinds, primarily centered around workforce shortages and the economic burden of "uncompensated care." The global shortage of specialized emergency physicians and nursing staff is driving up labor costs and limiting the operational capacity of many departments. Additionally, overcrowding remains a systemic challenge; when EDs operate at or above capacity, the resulting "boarding" of admitted patients leads to decreased throughput and potential revenue loss. Regulatory pressures regarding wait-time transparency and patient satisfaction scores also place a heavy administrative burden on hospital management, occasionally diverting funds away from clinical upgrades to administrative compliance tools.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Critical Staffing Shortages | -1.1% | North America & Europe | Ongoing |
| High Operational Costs & Overcrowding | -0.8% | Global | 2025 - 2029 |
| Stringent Regulatory Compliance | -0.5% | United States & UK | 2026 - 2034 |
Hospital Emergency Department Market Opportunities Analysis
The evolution of the emergency care model presents lucrative opportunities for stakeholders who can bridge the gap between hospital-based care and digital health. The integration of Tele-ER services allows rural hospitals to access board-certified emergency specialists remotely, creating a market for high-bandwidth communication platforms and remote diagnostic tools. There is also a burgeoning opportunity in the development of specialized "Geri-EDs" (Geriatric Emergency Departments) that are physically and operationally designed to meet the unique needs of elderly patients, reducing subsequent readmission rates. Furthermore, the adoption of blockchain for secure, instant sharing of patient medical histories during emergencies represents a significant niche for tech-forward healthcare providers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Tele-Emergency & Remote Triage | +1.5% | Middle East & Rural APAC | 2026 - 2034 |
| Specialized Geriatric Care Units | +1.1% | Developed Economies | 2027 - 2034 |
| Public-Private Partnership (PPP) Models | +0.7% | India, Brazil, Southeast Asia | 2025 - 2034 |
Hospital Emergency Department Market Challenges Impact Analysis
The most pressing challenges in the Hospital Emergency Department market involve balancing clinical quality with economic sustainability. The "boarding crisis," where patients wait in the ED for days because inpatient beds are unavailable, creates a bottleneck that diminishes the quality of care and increases medical errors. Furthermore, the threat of cyberattacks on hospital infrastructures has become a critical concern, as any downtime in an ED environment can literally be a matter of life and death. Ensuring data integrity while maintaining rapid access to patient records in a high-stress environment remains a complex technical and administrative challenge for modern medical facilities.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Inpatient Bed Shortages (Boarding) | -0.9% | United Kingdom & USA | 2025 - 2030 |
| Cybersecurity & Data Vulnerability | -0.6% | Global | 2025 - 2034 |
| Fluctuating Reimbursement Policies | -0.4% | United States (Medicare/Medicaid) | 2026 - 2034 |
Hospital Emergency Department Market - Updated Report Scope
This report provides a granular analysis of the global hospital emergency department ecosystem, encompassing clinical workflows, technological infrastructure, and financial performance metrics. The scope covers various facility types ranging from level-1 trauma centers to standalone emergency units, analyzing how each segment adapts to changing patient volumes and acuity levels. By integrating statistical data with qualitative insights from healthcare administrators and clinical directors, the report offers a comprehensive view of the strategic investments driving the market forward through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 645.65 Billion |
| Market Forecast in 2034 | USD 1,152.45 Billion |
| Growth Rate | 5.97% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | HCA Healthcare, Tenet Healthcare Corporation, Community Health Systems, Inc., Apollo Hospitals Enterprise Ltd., Universal Health Services, Inc., Fresenius Medical Care, Ramsay Health Care, IHH Healthcare Berhad, Ascension, Cleveland Clinic, Mayo Clinic, Spire Healthcare Group plc, Fortis Healthcare, Lifepoint Health, Providence St. Joseph Health, Encompass Health Corporation. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Hospital Emergency Department market is segmented into several critical categories that define operational priorities and capital expenditure. The "By System Type" segment highlights the distinction between public facilities, which often manage higher volumes and uncompensated care, and private facilities, which typically lead in the adoption of premium technologies and amenities. The "By Condition" segment is particularly vital for medical device and pharmaceutical manufacturers, as it dictates the demand for specific diagnostic tools, such as cardiac biomarkers for chest pain patients or rapid imaging for trauma victims. Furthermore, the segmentation by "Acuity Level" allows for a deep dive into resource intensity, showing how "High Acuity" cases, while lower in volume, account for a disproportionately large share of revenue and resource utilization.
- By System Type:
- Public/Government-funded (Highest patient volume)
- Private (Highest technological investment)
- Voluntary/Non-profit
- By Patient Type:
- Geriatric (Fastest growing due to aging population)
- Adult
- Pediatric (Specialized equipment and environmental needs)
- By Condition:
- Trauma and Injuries
- Cardiovascular Emergencies (High-value segment)
- Infectious Diseases (Critical for public health surveillance)
- Respiratory Conditions
- Neurological/Stroke Care
- By Service:
- Diagnostic Imaging (CT, MRI, X-ray, Ultrasound)
- Clinical Lab Testing (POCT, Hematology, Blood Gas)
- Therapeutic Services (Surgery, Resuscitation, Wound Care)
Regional Highlights
- North America: Dominates the market value with the highest concentration of private healthcare networks and advanced Level-1 trauma centers. The U.S. is the primary driver, focusing on reducing ED wait times through software-driven logistics.
- Asia-Pacific: Forecasted as the fastest-growing region. Massive government investments in China’s tiered healthcare system and India’s burgeoning private hospital sector are creating a huge demand for emergency medical infrastructure.
- Europe: Characterized by highly efficient public healthcare systems (like the NHS and German social health insurance models) focusing on integrated care pathways to reduce the load on emergency departments.
- Middle East & Africa: Significant growth in the GCC countries due to "Medical City" projects and a push for advanced trauma care to support rapid urban development and industrial growth.
- Latin America: Developing trauma care networks in Brazil and Mexico represent significant opportunities for medical device exports and hospital management consulting.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Hospital Emergency Department Market.- HCA Healthcare
- Tenet Healthcare Corporation
- Community Health Systems, Inc.
- Universal Health Services, Inc.
- Apollo Hospitals Enterprise Ltd.
- Fresenius Medical Care
- IHH Healthcare Berhad
- Ramsay Health Care
- Ascension
- Cleveland Clinic
- Mayo Clinic
- Providence St. Joseph Health
- Spire Healthcare Group plc
- Fortis Healthcare
- Encompass Health Corporation
- Lifepoint Health
- Select Medical Holdings Corporation
- Ardent Health Services
- Kindred Healthcare
- Prime Healthcare Services
Frequently Asked Questions
What is the projected growth rate of the Hospital Emergency Department market?
The global Hospital Emergency Department market is expected to grow at a CAGR of 5.97% from 2025 to 2034, driven by an aging population and technological advancements in diagnostics.
Which region currently leads the market and why?
North America currently leads the market due to its advanced medical infrastructure, high healthcare spending per capita, and early adoption of AI-integrated emergency care solutions.
What are the biggest challenges facing emergency departments today?
The primary challenges include chronic overcrowding, the "boarding" of admitted patients in the ED, and a significant shortage of specialized emergency medical personnel.
How is AI impacting the Hospital Emergency Department market?
AI is improving the market by enabling faster triage, predicting patient deterioration, optimizing staff scheduling, and reducing diagnostic errors in high-stress environments.
What segment by patient type is expected to see the most growth?
The geriatric patient segment is expected to see the most significant growth as the global population ages, leading to a higher frequency of complex, high-acuity emergency visits.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
