Tableware Market
Tableware Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711418 | Published On : October 31, 2026 |
Format : 


 | Author : Ridam Bhatt
Tableware Market Size
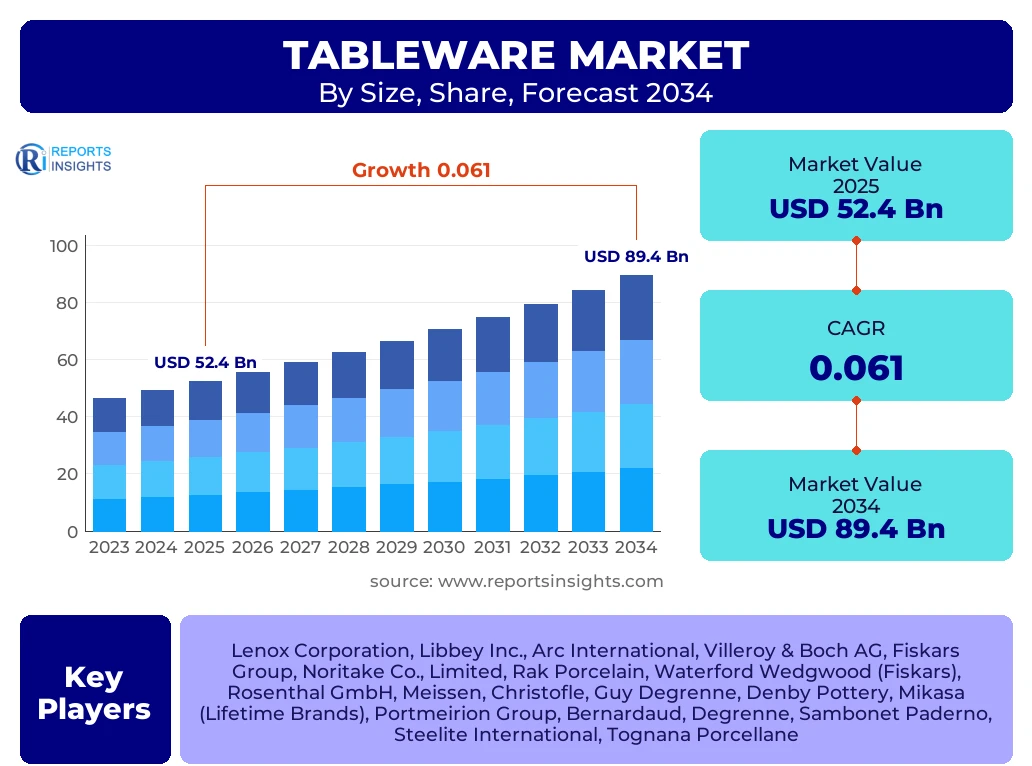
According to Reports Insights Consulting Pvt Ltd, The Tableware Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.1% between 2025 and 2034. The market is estimated at USD 55.6 Billion in 2026 and is projected to reach USD 89.4 Billion by the end of the forecast period in 2034.
The global tableware industry is currently navigating a transformative era characterized by a shift from purely functional utility to aesthetic and lifestyle expression. This market encompasses a broad range of products used for setting a table, serving food, and dining, including dinnerware, flatware, and glassware. Historically, growth was driven by basic household formation and population increases. However, the contemporary landscape is increasingly influenced by the expansion of the hospitality sector (HoReCa), rising disposable incomes in emerging economies, and a heightened consumer focus on home decor and "tablescaping" trends popularized through digital media platforms.
Technological advancements in manufacturing processes, such as 3D printing for intricate ceramic designs and the development of more durable, dishwasher-safe materials, have further catalyzed market expansion. As consumers prioritize sustainability, manufacturers are pivoting toward eco-friendly materials like bamboo, recycled glass, and biodegradable polymers. The convergence of these factors, alongside the rapid expansion of e-commerce channels which provide global reach for boutique and artisanal brands, ensures a robust growth trajectory for the tableware market over the next decade.
Key Tableware Market Trends & Insights
The global tableware market is witnessing a significant pivot toward premiumization and sustainability. Consumers are moving away from mass-produced, generic items in favor of artisanal, handcrafted products that tell a story or reflect personal values. This trend is particularly evident in the "casual-premium" segment, where high-quality materials like bone china and porcelain are being designed for daily use rather than being reserved for special occasions. Regional insights suggest that while North America and Europe remain high-value markets for luxury and designer tableware, the Asia-Pacific region is experiencing the fastest growth due to rapid urbanization and a burgeoning middle class in China and India. Competitive benchmarking reveals that leading players are increasingly investing in direct-to-consumer (DTC) models to capture higher margins and better understand consumer preferences.
- Largest Region: Asia-Pacific currently holds the largest market share, driven by a massive population base and high consumption rates in China and India.
- Fastest Growing Region: Southeast Asia and parts of Africa are emerging as high-growth zones due to expanding tourism and hospitality infrastructure.
- Leading Segment by Material: Ceramic remains the dominant material segment, valued for its durability, versatility, and aesthetic appeal.
- Fastest Growing Segment by Channel: Online retail and specialized e-commerce platforms are seeing the highest growth rates as consumers seek convenience and variety.
- Emerging Aesthetic Trend: "Organic Minimalism" featuring earthy tones, matte finishes, and irregular shapes is dominating both residential and commercial sectors.
Key Takeaways Tableware Market Size & Forecast
The Tableware market is poised for steady expansion as the boundaries between home dining and professional hospitality continue to blur. Key insights indicate that the demand for multifunctional and space-saving tableware is rising, particularly in urban environments where living spaces are becoming smaller. Furthermore, the resilience of the global luxury sector has shielded high-end tableware brands from broader economic fluctuations, as affluent consumers view premium dinnerware as a long-term investment. The integration of "Smart Tableware" featuring temperature-controlled plates or nutritional tracking sensors is an emerging niche that indicates the market's long-term technological evolution.
- Market Maturity: While developed markets in Western Europe are reaching maturity, replacement demand for eco-friendly alternatives is driving new sales cycles.
- Leading Country: China stands as the primary hub for both production and consumption, significantly influencing global price points and design trends.
- Hospitality Impact: The resurgence of global tourism and the opening of new boutique hotels and fine-dining establishments are providing a critical volume boost for the flatware and glassware segments.
- Material Innovation: There is a notable shift toward bone ash-free vegan china to cater to the growing demographic of ethical consumers.
- Supply Chain Resilience: Companies are increasingly regionalizing their supply chains to mitigate the risks of global logistics disruptions and reduce their carbon footprint.
Tableware Market Drivers Analysis
The primary driver of the tableware market is the rapid expansion of the global hospitality and food service industry. As international travel returns to pre-pandemic levels and beyond, the demand for high-quality, durable, and aesthetically pleasing tableware in hotels and restaurants has surged. Additionally, the rise of the "Experience Economy" has led consumers to invest more in home entertaining, where the table setting serves as a centerpiece of the social experience. Increased urbanization and the subsequent growth in residential construction, particularly in developing nations, provide a continuous stream of new consumers entering the market.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of HoReCa Sector | +1.8% | Global (Strongest in APAC and MEA) | 2025 - 2034 |
| Rising Disposable Income & Urbanization | +1.5% | India, China, Brazil | 2025 - 2030 |
| Preference for Eco-friendly/Sustainable Products | +1.2% | Europe and North America | 2026 - 2034 |
| Growth of E-commerce and Social Media Influence | +0.9% | Global | 2025 - 2034 |
Tableware Market Restraints Analysis
One of the most significant restraints in the tableware market is the volatility of raw material prices, particularly for metals used in flatware and minerals used in ceramic production. Energy-intensive manufacturing processes, especially for kiln-fired ceramics and glass, make the industry vulnerable to fluctuations in energy costs. Furthermore, the market is highly fragmented, with intense competition from low-cost manufacturers in emerging markets often leading to price wars that squeeze the profit margins of established premium brands.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fluctuating Raw Material & Energy Costs | -0.7% | Europe and China | 2025 - 2028 |
| High Competition from Unorganized Local Players | -0.5% | India and Southeast Asia | 2025 - 2034 |
| Logistical Challenges for Fragile Goods | -0.3% | Global Export Markets | 2025 - 2030 |
Tableware Market Opportunities Analysis
The rise of personalized and bespoke tableware offers a lucrative opportunity for manufacturers to differentiate their offerings. By leveraging digital printing and small-batch production, brands can offer custom designs for both individual consumers and commercial clients. Another significant opportunity lies in the development of "Hybrid Materials" that combine the aesthetics of ceramic with the durability of melamine, targeting the outdoor dining and casual family segments. Furthermore, penetration into the under-served rural markets of emerging economies presents a long-term growth frontier.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Demand for Personalized/Customized Tableware | +1.4% | North America and Western Europe | 2026 - 2034 |
| Expansion into Smart/Tech-integrated Tableware | +0.8% | Japan, South Korea, USA | 2028 - 2034 |
| Focus on Anti-bacterial & Hygienic Coatings | +1.1% | Global (Healthcare and Residential) | 2025 - 2030 |
Tableware Market Challenges Impact Analysis
Sustainability regulations present a dual-edged sword; while they offer opportunities, the immediate challenge lies in the high cost of transitioning to carbon-neutral manufacturing and plastic-free packaging. Additionally, the prevalence of counterfeit products in the luxury tableware segment poses a threat to brand equity and revenue. The fragility of products also remains a logistical hurdle, leading to high return rates in the e-commerce sector which can erode profitability if not managed through advanced packaging solutions.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adherence to Stringent Environmental Regulations | -0.6% | European Union | 2025 - 2034 |
| Counterfeit Products & Intellectual Property Issues | -0.4% | Global (Online Marketplaces) | 2025 - 2034 |
| High Breakage Rates in Last-Mile Delivery | -0.5% | Global (E-commerce) | 2025 - 2030 |
Tableware Market - Updated Report Scope
The scope of this report provides a granular analysis of the global tableware industry, covering various product types, materials, and end-user segments. It evaluates the impact of macroeconomic factors such as inflation and global trade policies on market dynamics. The report also investigates the shift in consumer behavior toward sustainable living and how it influences material selection and brand loyalty. By analyzing the competitive landscape, the research identifies the strategies employed by market leaders to maintain their dominance while highlighting the emergence of niche players focusing on artisanal and technological innovations.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 52.4 Billion |
| Market Forecast in 2034 | USD 89.4 Billion |
| Growth Rate | 6.1% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Lenox Corporation, Libbey Inc., Arc International, Villeroy & Boch AG, Fiskars Group, Noritake Co., Limited, Rak Porcelain, Waterford Wedgwood (Fiskars), Rosenthal GmbH, Meissen, Christofle, Guy Degrenne, Denby Pottery, Mikasa (Lifetime Brands), Portmeirion Group, Bernardaud, Degrenne, Sambonet Paderno, Steelite International, Tognana Porcellane |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The tableware market is segmented based on product type, material, application, and distribution channel. Dinnerware remains the largest product category, driven by the essential nature of plates and bowls in every household and dining establishment. Within the material segment, ceramics continue to lead due to their versatility and the ability to be produced at various price points, from budget-friendly stoneware to luxury fine bone china. The commercial segment is expected to witness the highest growth rate as the global hospitality industry expands and requires frequent replacements of high-durability tableware.
- By Product Type:
- Dinnerware: Comprising the largest share, including plates, bowls, and serving platters.
- Flatware: Consisting of spoons, forks, knives, and specialized serving utensils.
- Glassware: Including drinking glasses, stemware for wine, and decorative carafes.
- Serveware: Specialized items like tazzas, gravy boats, and tiered stands.
- By Material:
- Ceramic: Segmented into Porcelain, Bone China, and Stoneware.
- Glass: Valued for transparency and elegance in beverage service.
- Metal: Dominated by stainless steel for everyday flatware and silver for luxury segments.
- Sustainable/Eco-friendly: Rapidly growing segment including Bamboo, Cork, and Recycled Glass.
- By Application:
- Residential: Focused on aesthetics, durability, and ease of maintenance for daily use.
- Commercial: Focused on high-volume durability, stackability, and industrial dishwasher safety (HoReCa).
- By Distribution Channel:
- Offline: Traditional retail including departmental stores and specialty boutiques.
- Online: Fast-growing channel encompassing brand websites and third-party marketplaces.
Regional Highlights
The regional landscape of the tableware market is diverse, with varying consumer preferences and economic drivers across different geographies. The Asia-Pacific region is the powerhouse of the industry, both as a manufacturing hub and a consumption giant. China, Japan, and India are the key contributors, where traditional ceramic heritage meets modern lifestyle demands. In North America and Europe, the market is driven by the premium and luxury segments, with a strong emphasis on brand heritage and design innovation. The Middle East is emerging as a high-growth market for luxury tableware, fueled by the development of ultra-luxury hotel projects and a culture of lavish social gatherings.
- Asia-Pacific: The largest market globally, characterized by high production volumes in China and a rapidly growing middle class in India. It is the fastest-growing region for both mid-range and luxury segments.
- North America: A mature market where growth is driven by the replacement cycle, e-commerce adoption, and a trend toward high-end outdoor dining sets in the United States and Canada.
- Europe: The heart of artisanal and heritage brands. Countries like Germany, France, and Italy are leaders in design and high-quality ceramic and glassware production.
- Middle East & Africa: Significant growth in the commercial sector due to massive investments in tourism (e.g., Saudi Arabia’s Vision 2030) and the expansion of the luxury hospitality industry in Dubai and Qatar.
- Latin America: Steady growth driven by urban development in Brazil and Mexico, with an increasing preference for modern, minimalist designs among younger demographics.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Tableware Market.- Lenox Corporation
- Libbey Inc.
- Arc International
- Villeroy & Boch AG
- Fiskars Group
- Noritake Co., Limited
- Rak Porcelain
- Waterford Wedgwood
- Rosenthal GmbH
- Meissen
- Christofle
- Guy Degrenne
- Denby Pottery
- Mikasa (Lifetime Brands)
- Portmeirion Group
- Bernardaud
- Sambonet Paderno
- Steelite International
- Tognana Porcellane
- Zwiesel Kristallglas AG
Frequently Asked Questions
What is the current market size of the global tableware industry?
The global tableware market is estimated to be valued at approximately USD 52.4 Billion in 2025 and is projected to reach USD 89.4 Billion by 2034, growing at a CAGR of 6.1% during the forecast period.
Which material is most preferred by consumers in the tableware market?
Ceramic, including porcelain and bone china, remains the most preferred material due to its durability, heat resistance, and vast range of design possibilities, accounting for the largest market share.
What are the primary drivers for the growth of the tableware market?
The key drivers include the rapid expansion of the global hospitality sector (HoReCa), rising disposable incomes in emerging economies, and the growing consumer trend of "home entertaining" and aesthetic table settings.
How is sustainability impacting the tableware industry?
Sustainability is driving a shift toward eco-friendly materials like bamboo, wood, and recycled glass. Additionally, brands are focusing on plastic-free packaging and energy-efficient manufacturing processes to appeal to eco-conscious consumers.
Which region is expected to witness the fastest growth in the next decade?
The Asia-Pacific region is expected to witness the fastest growth due to rapid urbanization, a burgeoning middle class, and significant investments in the tourism and food service industries in countries like India and China.
Author
R
Ridam Bhatt is a Manger Consumer Goods Research with over 6+ years of experience in the Consumer Goods Industry. He specializes in consumer market intelligence, demand forecasting, category performance analysis, competitive benchmarking, pricing strategy, retail and distribution assessment, consumer purchasing behavior, product portfolio evaluation, and market trend analysis across fast-moving and durable consumer goods segments. His research delivers actionable, data-driven insights that help organizations make strategic business decisions, identify growth opportunities, optimize operational performance, understand evolving consumer trends, and strengthen their competitive positioning in global consumer goods markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
