Smart Kitchen Appliance Market
Smart Kitchen Appliance Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_704561 | Published On : October 11, 2026 |
Format : 


 | Author : Ridam Bhatt
Smart Kitchen Appliance Market Size
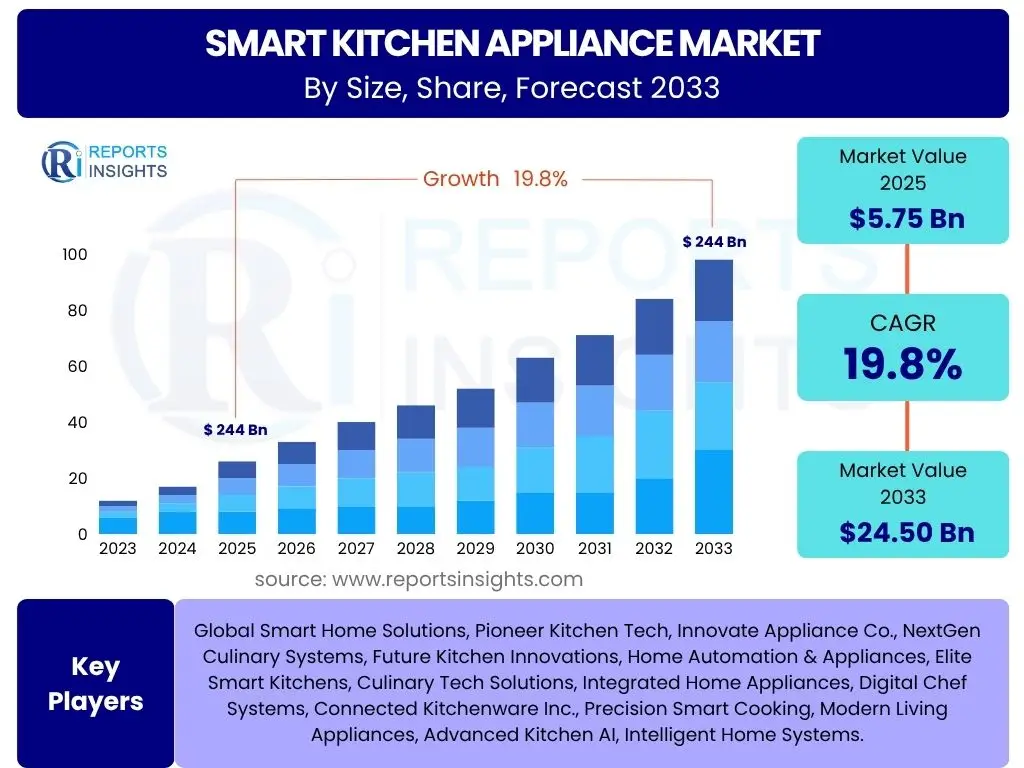
According to Reports Insights Consulting Pvt Ltd, The Smart Kitchen Appliance Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 16.4% between 2025 and 2034. The market is estimated at USD 26.24 Billion in 2026 and is projected to reach USD 88.43 Billion by the end of the forecast period in 2034.
Key Smart Kitchen Appliance Market Trends & Insights
The global landscape for Smart Kitchen Appliance is undergoing a radical transformation driven by the convergence of Artificial Intelligence (AI), the Internet of Things (IoT), and a heightened consumer focus on sustainable living. Current market intelligence suggests that the primary driver of adoption is no longer just "remote control" functionality but rather "autonomous operation." Modern consumers are increasingly seeking kitchen ecosystems that can manage food inventory, suggest recipes based on available ingredients, and optimize energy consumption in real-time. The integration of generative AI within kitchen interfaces is allowing for more natural voice interactions and personalized cooking experiences that adapt to dietary restrictions and cultural preferences. Furthermore, the industry is witnessing a significant shift toward the "Matter" connectivity standard, which aims to resolve historical interoperability issues between different brand ecosystems, thereby lowering the barrier to entry for many households.
Competitive benchmarking reveals that leading manufacturers are pivoting from hardware-centric models to software-as-a-service (SaaS) and subscription-based revenue streams. This includes automated grocery replenishment services and premium guided cooking content. From a regional perspective, while North America remains the high-value hub due to high disposable income and advanced home automation infrastructure, the Asia-Pacific region is emerging as the fastest-growing market. This growth is fueled by rapid urbanization in China and India, alongside a burgeoning middle class that views smart appliances as status symbols and essential tools for modern, time-constrained lifestyles. Segment-wise, smart refrigerators continue to dominate the market share, acting as the central hub or "brain" of the connected kitchen.
- Largest Region: North America remains the dominant market in terms of revenue share, supported by early adoption and a robust smart home ecosystem.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR during the forecast period due to large-scale urban development and increasing manufacturing capabilities.
- Largest Segment: Smart Refrigerators hold the largest market share owing to their role as a centralized control hub for other kitchen devices.
- Key Technology Trend: The adoption of the Matter protocol is standardizing connectivity, significantly improving user experience across heterogeneous device environments.
- Consumer Shift: A marked increase in demand for energy-efficient, "A-rated" smart appliances as energy costs rise globally and ESG awareness grows.
Key Takeaways Smart Kitchen Appliance Market Size & Forecast
The trajectory of the Smart Kitchen Appliance market indicates a robust double-digit growth phase over the next decade. Analysts highlight that the transition from traditional to smart appliances is being accelerated by the replacement cycle of existing household goods. As consumers replace aging refrigerators and ovens, they are increasingly opting for "future-proof" smart alternatives that offer long-term value through energy savings and software updates. The forecast suggests that by 2030, smart connectivity will become a standard feature in mid-range appliances, moving away from its current status as a premium-only offering. This democratization of technology is expected to drive massive volume growth across global markets.
- Dominant Market Position: The United States and China are the primary engines of growth, together accounting for nearly 45% of the global market value.
- Energy Management: Smart appliances are being integrated into broader Home Energy Management Systems (HEMS), allowing them to operate during off-peak hours to reduce electricity bills.
- AI-Driven Personalization: Machine learning algorithms are now standard in high-end ovens and ranges, enabling precision cooking that ensures consistent results for non-professional cooks.
- E-commerce Proliferation: Online retail channels are becoming the preferred medium for purchasing small smart appliances, while omnichannel strategies remain vital for large appliances.
- Data Monetization: Manufacturers are increasingly leveraging anonymized user data to refine product design and offer targeted consumer services, creating new value chains beyond the initial sale.
Smart Kitchen Appliance Market Drivers Analysis
The primary catalysts for the Smart Kitchen Appliance market include the rapid expansion of the smart home ecosystem and the increasing penetration of high-speed internet. Consumers are prioritizing convenience and efficiency to manage busy professional lives, leading to high demand for appliances that can be monitored and controlled remotely. Additionally, the global push for decarbonization is driving the adoption of energy-efficient smart appliances that help households monitor and reduce their carbon footprint.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration with Smart Home Ecosystems (IoT) | +5.2% | Global / North America | 2025-2034 |
| Demand for Energy Efficiency and Sustainability | +3.8% | Europe / Germany / UK | 2025-2030 |
| Advancements in AI and Voice Assistant Integration | +3.1% | US / China / Japan | 2026-2034 |
| Changing Lifestyle and Urbanization | +2.5% | Asia-Pacific / India | 2025-2034 |
Smart Kitchen Appliance Market Restraints Analysis
Despite strong growth prospects, the market faces significant hurdles related to the high initial cost of smart units compared to traditional counterparts. Furthermore, persistent concerns regarding data privacy and the potential for cybersecurity breaches in connected home devices act as a deterrent for a significant segment of the population. Interoperability issues between different brands also remain a point of friction for consumers who do not wish to be locked into a single manufacturer's ecosystem.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Acquisition and Maintenance Costs | -2.8% | Developing Markets / LATAM | 2025-2034 |
| Data Privacy and Cybersecurity Concerns | -2.1% | Europe / North America | 2025-2030 |
| Complexity of User Interface for Elderly Populations | -1.2% | Japan / Western Europe | 2026-2034 |
Smart Kitchen Appliance Market Opportunities Analysis
The integration of smart appliances with renewable energy sources and smart grids presents a massive opportunity for manufacturers to position their products as essential tools for the green transition. Additionally, the "Silver Economy"—targeting the aging population with appliances that feature safety sensors (e.g., automatic stove shut-off, health monitoring integration)—is a largely untapped segment. There is also a burgeoning opportunity in the "Commercial Kitchen" sector, where smart tech can optimize inventory management and reduce food waste in restaurants.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Partnerships with Grocery and Meal-Kit Services | +4.5% | USA / Western Europe | 2026-2034 |
| Development of Affordable Smart Small Appliances | +3.9% | India / Southeast Asia | 2025-2034 |
| Smart Grid Integration and Demand Response | +2.7% | California (US) / Germany | 2027-2034 |
Smart Kitchen Appliance Market Challenges Impact Analysis
One of the most pressing challenges is the rapid obsolescence of technology; hardware often outlives the software support provided by manufacturers, leading to "bricked" devices or security vulnerabilities. Additionally, the global supply chain for specialized semiconductors and sensors remains sensitive to geopolitical tensions, which can lead to price volatility and production delays. Maintaining a balance between advanced features and intuitive user design remains a constant struggle for R&D teams.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Standardization and Interoperability Hurdles | -1.9% | Global | 2025-2028 |
| Semiconductor Supply Chain Volatility | -1.5% | Global / Manufacturing Hubs | 2025-2034 |
| Short Product Lifecycle and Electronic Waste | -1.1% | Developed Economies | 2026-2034 |
Smart Kitchen Appliance Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the global Smart Kitchen Appliance industry, covering both large and small appliances equipped with advanced connectivity. The research evaluates the market based on product innovation, connectivity protocols, end-user demographics, and distribution strategies. It provides a granular look at the competitive landscape, highlighting how legacy appliance manufacturers are reinventing themselves as tech-forward entities while competing with native technology firms entering the kitchen space.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 22.54 Billion |
| Market Forecast in 2034 | USD 88.43 Billion |
| Growth Rate | 16.4% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Samsung Electronics, LG Electronics, Whirlpool Corporation, Robert Bosch GmbH, GE Appliances (a Haier company), Electrolux AB, Panasonic Corporation, Miele & Cie. KG, Breville Group, SharkNinja Operating LLC, Philips Domestic Appliances, Groupe SEB, Sub-Zero Group Inc., Arçelik A.S., Hisense Group, Viomi Technology, Xiaomi Corporation, BSH Hausgeräte GmbH, Fisher & Paykel Appliances, Smeg S.p.A. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Smart Kitchen Appliance market reflects a diverse range of consumer needs, from fundamental food preservation to intricate culinary execution. Large appliances currently hold the lion's share of the market value, as these are high-ticket items with longer replacement cycles. However, the "Small Appliances" segment is witnessing the most rapid innovation, with smart air fryers and multi-cookers becoming entry-level "gateway" products for consumers new to the smart home concept. Connectivity technology is also segmenting, with Wi-Fi being the standard for high-bandwidth tasks like video streaming from inside a fridge, while Bluetooth and Zigbee are preferred for lower-power peripheral sensors.
- By Product Category:
- Smart Refrigerators (Inventory management, interactive displays)
- Smart Cooking Appliances (Ovens, ranges, cooktops with precision heating)
- Smart Dishwashers (Auto-dosing, remote cycle monitoring)
- Small Appliances (Connected coffee machines, smart scales, blenders)
- By Connectivity Type:
- Wi-Fi Enabled (Most common for hub-based devices)
- Bluetooth/Bluetooth Low Energy (BLE)
- Zigbee and Z-Wave (Home automation mesh networks)
- Matter-compatible devices (The emerging industry standard)
- By Application/End-User:
- Residential (The largest segment by volume)
- Commercial (Focused on efficiency and compliance in professional kitchens)
- By Sales Channel:
- Offline (Hypermarkets, specialty appliance stores, showrooms)
- Online (Direct-to-consumer websites, third-party e-commerce platforms)
Regional Highlights
The regional distribution of the Smart Kitchen Appliance market is characterized by varying levels of infrastructure readiness and consumer purchasing power. North America, specifically the United States, leads in terms of per-household spending on smart technology. The presence of major tech ecosystems like Amazon Alexa, Google Home, and Apple HomeKit has facilitated a seamless integration of appliances into the broader smart home environment. In Europe, the focus is heavily skewed toward energy efficiency and data privacy, with Germany and the UK being the primary markets. The European Union's strict "Right to Repair" laws and energy labeling are forcing manufacturers to innovate in ways that prioritize longevity and low power consumption.
- North America: Largest market share (approx. 34%). Growth is driven by the rapid adoption of "connected living" and a high concentration of tech-savvy homeowners.
- Asia-Pacific: Fastest-growing region (CAGR ~18.5%). China is a global hub for both manufacturing and domestic consumption, with brands like Xiaomi and Haier leading the charge in affordable smart tech.
- Europe: Leading region for energy-efficient smart appliances. Germany and France are seeing high adoption rates for smart dishwashers and ovens that integrate with green energy grids.
- Latin America: Emerging market with high potential in Brazil and Mexico, though growth is currently tempered by economic volatility and higher import duties.
- Middle East & Africa: Significant growth in the luxury segment within the GCC countries, where smart "built-in" kitchen solutions are in high demand for new real estate developments.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Smart Kitchen Appliance Market.- Samsung Electronics
- LG Electronics
- Whirlpool Corporation
- Robert Bosch GmbH (BSH Hausgeräte)
- GE Appliances (Haier)
- Electrolux AB
- Panasonic Corporation
- Miele & Cie. KG
- Breville Group
- SharkNinja Operating LLC
- Philips Domestic Appliances
- Groupe SEB
- Sub-Zero Group Inc.
- Arçelik A.S.
- Hisense Group
- Viomi Technology
- Xiaomi Corporation
- Fisher & Paykel Appliances
- Smeg S.p.A.
- Kenmore (Transformco)
Frequently Asked Questions
What is the current market size of the global Smart Kitchen Appliance industry?
As of 2025, the market is valued at approximately USD 22.54 Billion. It is expected to reach USD 88.43 Billion by 2034, growing at a CAGR of 16.4%.
Which segment is expected to lead the Smart Kitchen Appliance market?
The Smart Refrigerator segment currently leads the market share because it serves as the central interface for the entire kitchen ecosystem, facilitating food management and household communication.
How does the Matter protocol affect the Smart Kitchen Appliance market?
The Matter protocol is a game-changer for the industry as it allows devices from different manufacturers (e.g., Apple, Google, Amazon, Samsung) to work together seamlessly, reducing consumer frustration and driving wider adoption.
What are the main barriers to the adoption of smart kitchen technology?
The primary barriers include the high cost of acquisition, concerns regarding data privacy and cybersecurity, and the potential for software to become obsolete before the hardware wears out.
Which region offers the most significant growth opportunities?
While North America is the largest in value, the Asia-Pacific region offers the most significant growth opportunities due to rapid urbanization, a rising middle class, and increasing internet penetration in China and India.
Author
R
Ridam Bhatt is a Manger Consumer Goods Research with over 6+ years of experience in the Consumer Goods Industry. He specializes in consumer market intelligence, demand forecasting, category performance analysis, competitive benchmarking, pricing strategy, retail and distribution assessment, consumer purchasing behavior, product portfolio evaluation, and market trend analysis across fast-moving and durable consumer goods segments. His research delivers actionable, data-driven insights that help organizations make strategic business decisions, identify growth opportunities, optimize operational performance, understand evolving consumer trends, and strengthen their competitive positioning in global consumer goods markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
