Structural Insulated Panel Market
Structural Insulated Panel Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711862 | Published On : November 19, 2026 |
Format : 


 | Author : Jonathan Sikka
Structural Insulated Panel Market Size
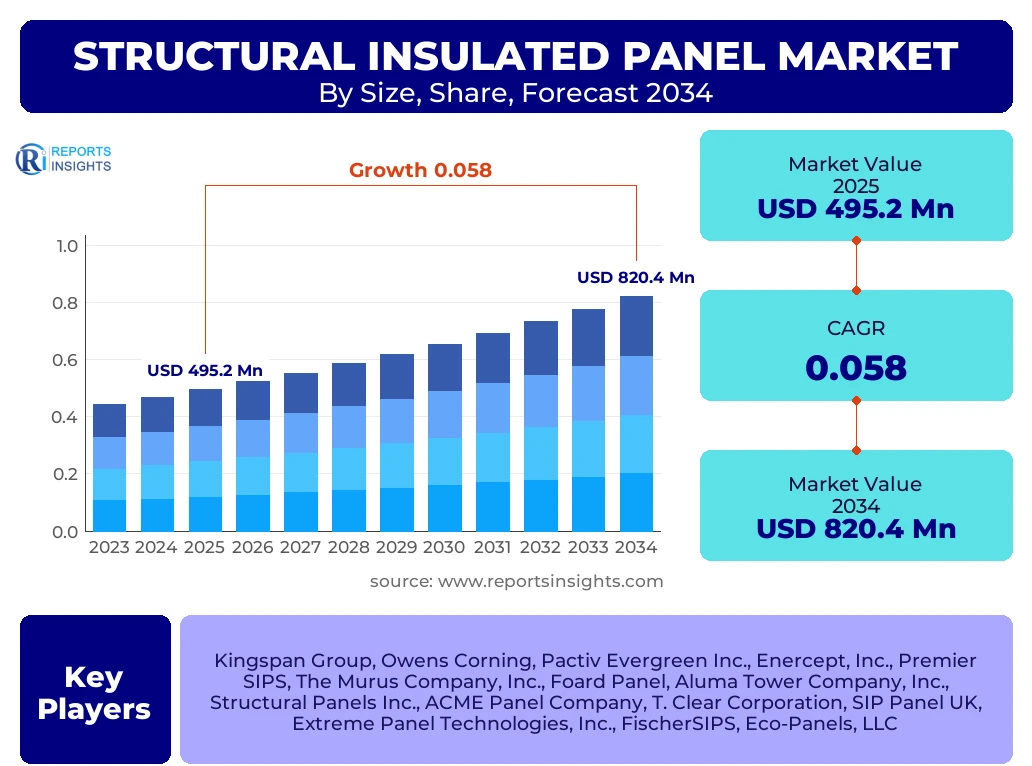
According to Reports Insights Consulting Pvt Ltd, The Structural Insulated Panel Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.8% between 2025 and 2034. The market is estimated at USD 523.9 Million in 2026 and is projected to reach USD 820.4 Million by the end of the forecast period in 2034.
Key Structural Insulated Panel Market Trends & Insights
The global construction landscape is undergoing a radical shift toward off-site manufacturing and high-performance building envelopes. Structural Insulated Panels (SIPs) are at the forefront of this transition, driven by the urgent need for energy-efficient residential and commercial structures that meet stringent net-zero emission targets. Market participants are increasingly focusing on the integration of advanced core materials, such as graphite-enhanced expanded polystyrene (GPS) and polyisocyanurate (PIR), which offer superior thermal resistance compared to traditional insulation. Furthermore, the rise of modular and prefabricated construction techniques has positioned SIPs as a preferred structural component due to their ability to reduce on-site labor requirements and significantly shorten project timelines.
- North America remains the largest regional market, bolstered by established building codes and a strong preference for wood-framed residential structures.
- Asia-Pacific is identified as the fastest-growing region, fueled by rapid urbanization and government-led initiatives for sustainable infrastructure in China and India.
- The Residential segment holds the largest market share, driven by a growing demand for eco-friendly housing and energy-conscious homeowners.
- Technological advancements in Magnesium Oxide (MgO) facings are gaining traction as fire-resistant alternatives to traditional Oriented Strand Board (OSB).
Key Takeaways Structural Insulated Panel Market Size & Forecast
The trajectory of the Structural Insulated Panel market is defined by a convergence of sustainability mandates and economic efficiency. As global building codes become more rigorous regarding R-values and air leakage, the inherent airtightness of SIP systems provides a competitive advantage over conventional stick-framing. Strategic investments are shifting toward automated production lines that enhance precision and reduce waste, further aligning the industry with circular economy principles. The forecast period is expected to witness a surge in light commercial applications, particularly in educational and healthcare facilities where rapid deployment is critical.
- The United States and Canada represent the leading countries in terms of adoption rates and technological innovation in panel manufacturing.
- EPS (Expanded Polystyrene) remains the dominant core material due to its cost-effectiveness and versatile thermal performance.
- Walls constitute the largest application segment, accounting for over 50 percent of the total market value throughout the forecast period.
- Increasing carbon tax implementations in Europe are accelerating the adoption of SIPs in large-scale renovation and retrofit projects.
Structural Insulated Panel Market Drivers Analysis
The primary catalysts for market expansion revolve around the global imperative for energy conservation and the structural transformation of the construction labor force. As the gap between available skilled labor and housing demand widens, SIPs provide a viable solution by shifting the complexity of framing from the job site to a controlled factory environment.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shift toward Modular and Prefabricated Construction | +1.5% | Global / North America | 2025 - 2034 |
| Stringent Building Energy Efficiency Codes (e.g., Title 24, Part L) | +1.2% | Europe and United States | 2026 - 2032 |
| Acute Shortage of Skilled On-site Framing Labor | +0.9% | United Kingdom, USA, Australia | 2025 - 2030 |
| Rising Demand for Net-Zero Energy Buildings (NZEB) | +1.1% | European Union / APAC | 2027 - 2034 |
Structural Insulated Panel Market Restraints Analysis
Despite strong growth prospects, the market faces hurdles related to initial capital expenditure and entrenched traditional building practices. Overcoming the skepticism of contractors accustomed to traditional stick-framing and managing the volatility of raw material costs remain central challenges for the industry.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Material Costs vs. Traditional Lumber | -0.7% | Emerging Markets | 2025 - 2034 |
| Resistance to Change in Traditional Construction Workflows | -0.5% | Global | 2025 - 2029 |
Structural Insulated Panel Market Opportunities Analysis
The evolution of material science presents significant opportunities for the integration of bio-based resins and recycled foam cores, appealing to the growing demographic of environmentally conscious consumers. Additionally, the expansion of SIPs into disaster-resilient housing projects offers a high-growth vertical in regions prone to extreme weather events.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Bio-based Core Materials | +0.8% | Europe / Scandinavia | 2028 - 2034 |
| Application in Disaster-Resilient and Rapid Housing | +1.0% | Southeast Asia / Coastal USA | 2026 - 2034 |
Structural Insulated Panel Market Challenges Impact Analysis
The primary challenges involve the logistical complexities of transporting large pre-fabricated panels and the need for specialized design software integration among architectural firms. Ensuring consistent quality across diverse regional manufacturing facilities also remains a point of focus for maintaining industry standards.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Logistical Constraints and Transportation Costs | -0.4% | Geographically Large Regions (e.g., Canada, Russia) | 2025 - 2034 |
| Lack of Specialized SIP Training for Architects/Engineers | -0.3% | Developing Economies | 2025 - 2030 |
Structural Insulated Panel Market - Updated Report Scope
This report provides a granular analysis of the global Structural Insulated Panel landscape, encompassing technological advancements in core chemistry, facing materials, and diverse application verticals. It offers a detailed assessment of the competitive environment, regulatory shifts, and regional growth engines through 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 495.2 Million |
| Market Forecast in 2034 | USD 820.4 Million |
| Growth Rate | 5.8% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Kingspan Group, Owens Corning, Pactiv Evergreen Inc., Enercept, Inc., Premier SIPS, The Murus Company, Inc., Foard Panel, Aluma Tower Company, Inc., Structural Panels Inc., ACME Panel Company, T. Clear Corporation, SIP Panel UK, Extreme Panel Technologies, Inc., FischerSIPS, Eco-Panels, LLC |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Structural Insulated Panel market reflects the diverse engineering requirements of modern construction. The core material choice is predominantly dictated by the required thermal resistance (R-value) and budget, while the choice of facing material is increasingly influenced by regional fire safety regulations and environmental durability needs. The residential sector remains the anchor for the industry, but there is a notable rise in institutional applications where the speed of assembly is a critical project requirement.
- By Facing Material: OSB is the industry standard due to its structural properties and cost, while MgO is gaining share in high-density urban areas for its non-combustible properties.
- By Insulation Core: EPS dominates the volume share; however, PIR and PUR are preferred for cold storage and high-performance commercial roofs due to higher R-values per inch.
- By Application: Wall panels lead the market as they provide the structural frame, insulation, and air barrier in a single step. Roof panels are the second largest segment, offering superior vaulted ceiling insulation.
- By End-Use: Single-family residential remains the primary driver, though multi-family and light commercial sectors are expanding rapidly due to building code updates.
Regional Highlights
- North America: The largest market share holder, with the United States leading in SIP manufacturing capacity and architectural adoption, particularly in the Pacific Northwest and Northeast regions.
- Europe: A mature market characterized by high innovation in sustainable materials. Countries like Germany, the UK, and Sweden are early adopters of SIPs for Passive House standards.
- Asia-Pacific: The fastest-growing region, where massive urbanization in China and Vietnam is driving interest in prefabricated structural systems to meet housing targets quickly.
- Latin America & MEA: Emerging markets where SIPs are increasingly used for remote mining housing, luxury eco-resorts, and rapid-response social housing projects.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Structural Insulated Panel Market. These organizations are focusing on horizontal integration and expanding their manufacturing footprints to minimize shipping costs and lead times.
- Kingspan Group
- Owens Corning
- Pactiv Evergreen Inc.
- Enercept, Inc.
- Premier SIPS
- The Murus Company, Inc.
- Foard Panel
- Aluma Tower Company, Inc.
- Structural Panels Inc.
- ACME Panel Company
- T. Clear Corporation
- SIP Panel UK
- Extreme Panel Technologies, Inc.
- FischerSIPS
- Eco-Panels, LLC
- MagBoard LLC
- SIPS Eco Panels
- Innova Eco Building System
Frequently Asked Questions
What are the primary advantages of using Structural Insulated Panels over traditional framing?
SIPs offer significantly higher energy efficiency through continuous insulation and reduced air infiltration. They also accelerate construction timelines by up to 50 percent, reduce job site waste, and provide superior structural strength against wind and seismic loads compared to traditional stick-framing.
How do Structural Insulated Panels perform in terms of fire resistance?
Standard OSB-faced SIPs meet fire code requirements when covered with 15-minute thermal barriers like gypsum wallboard. Advanced panels using Magnesium Oxide (MgO) facings offer inherent non-combustible properties, providing enhanced safety and meeting more stringent commercial fire ratings.
Which core material is best for high-performance buildings?
While EPS is the most common and cost-effective, Polyisocyanurate (PIR) or Polyurethane (PUR) cores are often preferred for high-performance or space-constrained projects because they offer a higher R-value per inch, allowing for thinner walls with equivalent thermal performance.
Are SIPs more expensive than traditional building materials?
On a raw material basis, SIPs are generally more expensive than lumber. However, when considering the "total installed cost"—which includes reduced labor hours, smaller HVAC equipment requirements, and lower long-term energy bills—SIPs are often more cost-competitive over the building's lifecycle.
Which region is expected to see the highest growth in SIP adoption by 2034?
The Asia-Pacific region is projected to experience the highest growth rate due to its massive construction volume and increasing governmental focus on green building standards to combat carbon emissions in rapidly developing urban centers.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
