Pipe Insulation Market
Pipe Insulation Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711848 | Published On : November 19, 2026 |
Format : 


 | Author : Jonathan Sikka
Pipe Insulation Market Size
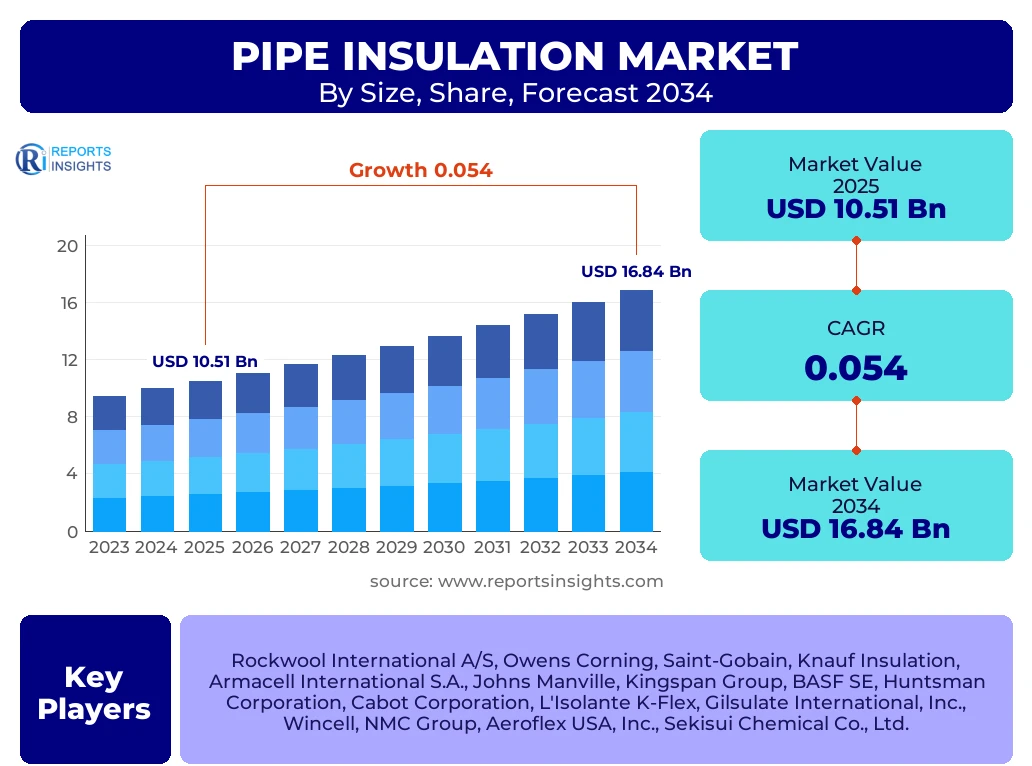
According to Reports Insights Consulting Pvt Ltd, The Pipe Insulation Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.4% between 2025 and 2034. The market is estimated at USD 11.08 Billion in 2026 and is projected to reach USD 16.84 Billion by the end of the forecast period in 2034.
Key Pipe Insulation Market Trends & Insights
The global pipe insulation landscape is currently undergoing a transformative phase driven by the dual imperatives of industrial decarbonization and stringent energy conservation mandates. Stakeholders are increasingly prioritizing materials that offer not only superior thermal resistance but also fire safety and moisture control. Competitive benchmarking reveals a strategic pivot toward high-performance materials like aerogels and advanced elastomeric foams, which cater to the burgeoning demand in the LNG and cryogenic sectors. Furthermore, the integration of digital tools for thermal loss auditing is becoming a standard practice among leading industrial operators to justify the ROI of premium insulation systems.
- Largest Region: North America remains the largest market by value, attributed to a massive base of existing industrial infrastructure and rigorous building codes.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR due to rapid urbanization, massive investments in district heating systems in China, and expanding chemical processing hubs in India and Southeast Asia.
- Leading Material Segment: Rockwool (Mineral Wool) currently holds the largest market share owing to its excellent fire-resistant properties and cost-effectiveness in high-temperature industrial applications.
- Primary End-Use Driver: The Industrial segment, particularly Oil & Gas and Chemical processing, continues to dominate the market share, necessitated by the need for process stability and personnel protection.
Key Takeaways Pipe Insulation Market Size & Forecast
The trajectory of the pipe insulation market is intrinsically linked to global energy prices and environmental legislation. As governments worldwide commit to Net Zero targets, the retrofitting of aged piping networks in commercial buildings and industrial plants has emerged as a primary growth lever. The forecast indicates a steady shift from traditional fiberglass toward closed-cell structures that prevent corrosion under insulation (CUI), a major maintenance concern for asset owners. Market dynamics suggest that while initial capital expenditure remains a hurdle, the long-term operational savings and reduction in carbon footprints are compelling drivers for large-scale adoption.
- Dominant Material: Rockwool leads the market due to its versatility across both residential and heavy industrial sectors.
- Infrastructure Expansion: Massive district energy projects in Northern Europe and China are creating a sustained demand for pre-insulated piping systems.
- Sustainability Focus: There is a notable rise in the procurement of bio-based and recyclable insulation materials to meet LEED and BREEAM certifications in the construction sector.
- Technological Integration: The emergence of "smart insulation" equipped with sensors to detect moisture and heat leaks is gaining traction in the high-value pharmaceutical and food processing industries.
Pipe Insulation Market Drivers Analysis
The primary catalysts for the pipe insulation market include the escalating need for energy efficiency in thermal management systems and the rigorous enforcement of safety regulations across the industrial spectrum. As energy costs fluctuate, the economic viability of minimizing heat gain or loss through piping becomes more pronounced, driving both new installations and retrofits.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Energy Efficiency Regulations | +1.8% | European Union & North America | 2025–2034 |
| Growth in District Heating & Cooling | +1.2% | China, Russia, Germany | 2026–2032 |
| Expansion of the Oil & Gas Midstream Sector | +0.9% | Middle East & USA | 2025–2030 |
Pipe Insulation Market Restraints Analysis
Despite growth, the market faces headwinds from volatile raw material prices, particularly for petroleum-based polymers used in plastic foams. Additionally, the labor-intensive nature of complex insulation installations in confined industrial spaces can deter immediate upgrades in budget-sensitive regions.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatile Raw Material Costs | -0.7% | Global | 2025–2034 |
| Complex Installation & Maintenance | -0.4% | Developing Nations (APAC, Africa) | 2026–2030 |
Pipe Insulation Market Opportunities Analysis
The transition toward renewable energy and the development of hydrogen infrastructure present significant white-space opportunities. Insulation systems capable of handling the extreme temperatures required for liquid hydrogen transport are becoming a critical area for research and development and future market capture.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Hydrogen Economy Infrastructure | +1.5% | EU, Japan, South Korea | 2028–2034 |
| Development of Bio-based Insulation | +0.8% | North America & Europe | 2026–2034 |
Pipe Insulation Market Challenges Impact Analysis
Corrosion Under Insulation (CUI) remains the most significant technical challenge, often leading to catastrophic pipe failures. Developing insulation materials that can mitigate moisture ingress while maintaining thermal properties is a persistent hurdle for the industry's material scientists.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Mitigating Corrosion Under Insulation (CUI) | -0.6% | Global Industrial Sector | 2025–2034 |
| Health Concerns Over Fibrous Materials | -0.3% | Europe & North America | 2025–2029 |
Pipe Insulation Market - Updated Report Scope
This report provides a comprehensive examination of the pipe insulation sector, encompassing a detailed analysis of material science advancements, end-user demand patterns, and regional regulatory landscapes. The scope includes a deep dive into the competitive environment, identifying the strategic maneuvers of key market participants across different geographic tiers.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 10.51 Billion |
| Market Forecast in 2034 | USD 16.84 Billion |
| Growth Rate | 5.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Rockwool International A/S, Owens Corning, Saint-Gobain, Knauf Insulation, Armacell International S.A., Johns Manville, Kingspan Group, BASF SE, Huntsman Corporation, Cabot Corporation, L'Isolante K-Flex, Gilsulate International, Inc., Wincell, NMC Group, Aeroflex USA, Inc., Sekisui Chemical Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The pipe insulation market is segmented based on material composition, thermal application, and end-user requirements. Each segment is influenced by specific technical parameters such as K-value (thermal conductivity), water vapor permeability, and service temperature range, which determine the suitability of the insulation for specific environments.
- By Material:
- Rockwool: Preferred for high-temperature industrial steam pipes and fire protection.
- Fiberglass: Common in commercial HVAC systems due to its lightweight and cost-effective nature.
- Elastomeric Foam: Dominant in refrigeration and cold-water systems to prevent condensation.
- Polyurethane Foam (PUF): Extensively used in pre-insulated pipes for district heating.
- Cellular Glass: Utilized in extreme industrial conditions where moisture resistance is critical.
- By Application:
- Hot Insulation: Aimed at energy conservation and heat retention in power plants and refineries.
- Cold Insulation: Essential for LNG transport, cryogenics, and cooling systems to prevent icing and energy loss.
- By End-Use Industry:
- Industrial: The largest consumer, spanning petrochemicals, power generation, and manufacturing.
- Commercial & Residential: Driven by building codes and the expansion of plumbing and HVAC networks.
- District Heating & Cooling: A growing segment in urban centers focused on centralized thermal energy efficiency.
Regional Highlights
The global distribution of the pipe insulation market is characterized by regional specialization in terms of material demand and application focus. Regulatory frameworks, such as the Energy Performance of Buildings Directive (EPBD) in Europe and ASHRAE standards in North America, play a pivotal role in shaping local market dynamics.
- North America: Holds the largest market share value, driven by a mature industrial sector and extensive renovation of commercial buildings to meet updated energy standards. The US is a major hub for high-performance insulation in the shale gas industry.
- Europe: A leader in sustainable insulation practices and district heating. Countries like Germany and the Nordic nations are at the forefront of adopting high-efficiency pre-insulated pipes for urban energy networks.
- Asia-Pacific: The fastest-growing region, powered by massive industrialization and infrastructure development in China and India. The region's growing chemical and pharmaceutical industries are creating significant demand for specialized pipe insulation.
- Middle East & Africa: Demand is primarily centered around the Oil & Gas sector, with a focus on high-temperature insulation for refineries and petrochemical plants.
- Latin America: Expected to show steady growth as industrial activities in Brazil and Mexico expand, particularly in the food processing and beverage sectors.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Pipe Insulation Market.- Rockwool International A/S
- Owens Corning
- Saint-Gobain
- Knauf Insulation
- Armacell International S.A.
- Johns Manville (A Berkshire Hathaway Company)
- Kingspan Group
- BASF SE
- Huntsman Corporation
- Cabot Corporation
- L'Isolante K-Flex
- Gilsulate International, Inc.
- Wincell
- NMC Group
- Aeroflex USA, Inc.
- Sekisui Chemical Co., Ltd.
- Paroc Group (Part of Owens Corning)
- Zhejiang Meitong Geothermal Technology Co., Ltd.
- 3M Company
- Aspen Aerogels, Inc.
Frequently Asked Questions
What is the current size and projected growth of the Pipe Insulation market?
The market is estimated at USD 11.08 Billion in 2026 and is projected to reach USD 16.84 Billion by 2034, growing at a CAGR of 5.4%. This growth is driven by rising energy costs and stringent environmental regulations globally.
Which material is most commonly used for pipe insulation?
Rockwool (Mineral Wool) is the leading material due to its exceptional fire resistance, acoustic properties, and wide service temperature range, making it suitable for diverse industrial and building applications.
What are the key drivers for the Asia-Pacific pipe insulation market?
The primary drivers in APAC include rapid industrialization, the expansion of district heating systems in colder climates like Northern China, and the growth of the chemical and pharmaceutical manufacturing sectors in India and Southeast Asia.
What is Corrosion Under Insulation (CUI) and how does it affect the market?
CUI is a form of corrosion that occurs when moisture is trapped between the pipe surface and the insulation. It is a major challenge, driving the development of closed-cell insulation materials and water-repellent coatings to enhance pipe longevity.
How is the focus on sustainability impacting the pipe insulation industry?
Sustainability is leading to a surge in demand for materials with low Global Warming Potential (GWP) and bio-based contents. Companies are also focusing on the circular economy by developing recyclable insulation products and reducing VOC emissions.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
