Industrial Duct Dust Collection Market
Industrial Duct Dust Collection Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711554 | Published On : November 06, 2026 |
Format : 


 | Author : Jonathan Sikka
Industrial Duct Dust Collection Market Size
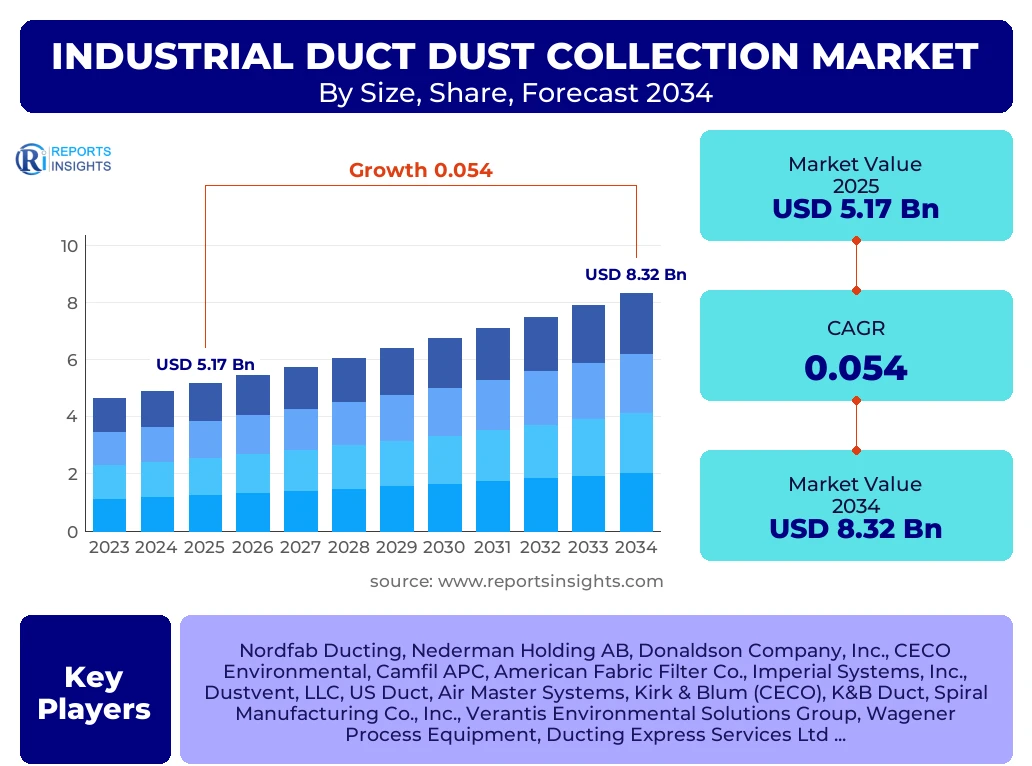
According to Reports Insights Consulting Pvt Ltd, The Industrial Duct Dust Collection Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.4% between 2025 and 2034. The market is estimated at USD 5.45 Billion in 2026 and is projected to reach USD 8.32 Billion by the end of the forecast period in 2034.
Key Industrial Duct Dust Collection Market Trends & Insights
The industrial ducting landscape is undergoing a significant transformation as manufacturing facilities prioritize modularity and energy efficiency. Market participants are increasingly shifting toward clamp-together ducting systems which reduce installation downtime and allow for rapid reconfiguration of production lines. Furthermore, the integration of smart sensors within duct networks to monitor airflow velocity and pressure drops in real-time is becoming a standard practice for Tier-1 industrial operators. This trend is driven by the need to minimize energy consumption and prevent the accumulation of combustible dust, which poses severe safety risks. Regional demand is pivoting toward the Asia-Pacific region, where rapid industrialization in the pharmaceutical and electronics sectors necessitates high-precision air filtration and containment systems.
- Asia-Pacific is the fastest-growing region due to massive investments in heavy manufacturing and chemical processing hubs in India and Southeast Asia.
- North America remains the largest region by value, sustained by stringent OSHA and NFPA compliance requirements regarding indoor air quality.
- The galvanized steel segment holds the largest market share owing to its cost-effectiveness and durability in general manufacturing environments.
- The pharmaceutical and food processing end-user segments are the fastest-growing niches due to heightening hygiene standards and the transition toward stainless steel ducting.
Key Takeaways Industrial Duct Dust Collection Market Size & Forecast
The forecast period from 2025 to 2034 reflects a steady upward trajectory fueled by the global replacement cycle of aging ventilation infrastructure and the expansion of the renewable energy manufacturing sector. Stakeholders are focusing on specialized ducting solutions that can handle abrasive materials and high-temperature exhausts without compromising structural integrity. The market is also seeing a consolidation phase where larger air filtration companies are acquiring specialized ducting manufacturers to provide end-to-end air management solutions. This strategic integration is expected to streamline supply chains and offer more competitive turnkey pricing for large-scale industrial projects.
- The global market will see a valuation increase of nearly USD 3 billion over the next decade.
- Stainless steel 316-grade ducting is emerging as a critical sub-segment for corrosive environments in chemical and offshore industries.
- Adoption of Computational Fluid Dynamics (CFD) in the design phase is reducing material waste and optimizing system performance.
- Germany and Japan are the leading countries in terms of technical innovation, specifically in aerodynamic efficiency and leak-proof jointing technologies.
Industrial Duct Dust Collection Market Drivers Analysis
The primary catalyst for market expansion is the global tightening of workplace safety and environmental regulations. Industrial facilities are under increasing pressure to mitigate the risks of respiratory illnesses and dust-related explosions. Additionally, the drive for operational efficiency is pushing companies to adopt high-performance ducting that minimizes friction loss, thereby reducing the workload on dust collector fans and lowering overall electricity costs. The rise of "Green Manufacturing" initiatives is further accelerating the demand for sustainable and recyclable ducting materials.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory Compliance (OSHA/NFPA) | +1.8% | North America & Europe | 2025 - 2034 |
| Rapid Industrialization and Infrastructure Growth | +1.5% | India, Vietnam, Indonesia | 2026 - 2030 |
| Focus on Energy Efficiency and LEED Certification | +1.1% | Global | 2025 - 2034 |
Industrial Duct Dust Collection Market Restraints Analysis
Despite robust growth, the market faces hurdles such as high initial capital expenditure and the volatility of raw material prices, particularly steel and aluminum. Small and medium-sized enterprises (SMEs) often struggle with the cost of retrofitting existing facilities with advanced, leak-proof ducting systems. Furthermore, the complexity of custom-designed duct layouts can lead to long project lead times, which may deter quick adoption in fast-paced manufacturing sectors.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fluctuating Raw Material (Steel) Costs | -0.7% | Global | Short to Medium Term |
| High Installation and Maintenance Complexity | -0.5% | SME Sector (Global) | 2025 - 2034 |
Industrial Duct Dust Collection Market Opportunities Analysis
The integration of Industrial Internet of Things (IIoT) presents a significant growth avenue, allowing for predictive maintenance and automated airflow balancing. Companies that offer modular, "click-and-seal" ducting designs are well-positioned to capture the market segment looking for DIY installation options. Additionally, the burgeoning lithium-ion battery manufacturing industry requires specialized, ultra-clean ducting environments, representing a high-margin opportunity for specialized players.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| IIoT and Smart Monitoring Integration | +1.2% | Developed Economies | 2027 - 2034 |
| Emergence of EV Battery Gigafactories | +0.9% | China, USA, Germany | 2025 - 2032 |
Industrial Duct Dust Collection Market Challenges Impact Analysis
The presence of a fragmented secondary market with low-cost, uncertified ducting components poses a challenge to established brands that adhere to high safety standards. Maintaining airtight seals over long-term operation in high-vibration environments also remains a technical challenge that requires constant R&D investment. Furthermore, navigating the differing international standards for ducting thickness and flange specifications complicates global supply chain management.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Market Fragmentation and Low-Quality Counterfeits | -0.4% | APAC & MEA | 2025 - 2034 |
| Cross-Border Regulatory Divergence | -0.3% | International Trade | Long Term |
Industrial Duct Dust Collection Market - Updated Report Scope
This report provides a granular analysis of the industrial ducting ecosystem, covering materials, design types, and various end-user applications across six major geographical regions. It evaluates the impact of macroeconomic factors and technical innovations on market dynamics from 2020 through the forecast end-point of 2034, ensuring a comprehensive view of historical performance and future potential.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 5.17 Billion |
| Market Forecast in 2034 | USD 8.32 Billion |
| Growth Rate | 5.4% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Nordfab Ducting, Nederman Holding AB, Donaldson Company, Inc., CECO Environmental, Camfil APC, American Fabric Filter Co., Imperial Systems, Inc., Dustvent, LLC, US Duct, Air Master Systems, Kirk & Blum (CECO), K&B Duct, Spiral Manufacturing Co., Inc., Verantis Environmental Solutions Group, Wagener Process Equipment, Ducting Express Services Ltd, Flexaust Inc., Masterduct, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The industrial ducting market is segmented based on material composition, construction type, and the specific pollutants they are designed to transport. The material choice is largely governed by the chemical properties of the dust and the environmental conditions of the factory floor. For instance, carbon steel is preferred for heavy-duty abrasive mining applications, while stainless steel is non-negotiable in environments requiring frequent sanitization or handling of corrosive vapors. The design of the ducting—whether spiral or longitudinal—significantly impacts the static pressure and the efficiency of the collection system.
- By Material:
- Galvanized Steel: Preferred for general industrial use due to rust resistance and affordability.
- Stainless Steel (304/316): Essential for food processing and pharmaceutical industries to meet FDA standards.
- Carbon Steel: Used in high-abrasion environments such as mining and heavy metal fabrication.
- Fiberglass/FRP: Utilized for highly corrosive chemical fumes where metal would degrade.
- By Duct Design Type:
- Spiral Ducting: Known for high strength and low weight, ideal for long runs.
- Clamp-Together: Rapidly gaining share due to ease of cleaning and installation.
- Flanged Ducting: Used for heavy-gauge applications and high-pressure systems.
- By End-User Industry:
- Woodworking: Large volume requirements for sawdust and wood chip transport.
- Metalworking: Focus on capturing fine metallic dust and weld fumes.
- Pharmaceutical: Cleanroom compatible ducting with smooth interior finishes.
Regional Highlights
- North America: Currently leads the market in terms of value. The presence of strict environmental standards (EPA) and safety regulations (OSHA) ensures a steady demand for high-quality ducting systems and regular upgrades.
- Asia-Pacific: Expected to witness the highest CAGR. China’s "Blue Sky" initiative and India’s burgeoning pharmaceutical sector are massive drivers for industrial air filtration infrastructure.
- Europe: A mature market focused on innovation. Germany and Italy are key hubs for manufacturing advanced ducting components that prioritize noise reduction and thermal insulation.
- Middle East & Africa: Growth is concentrated in the mining and cement industries, where heavy-duty ducting is required to handle high volumes of abrasive particulate matter.
- Latin America: Brazil and Mexico are emerging as significant players due to the expansion of their automotive and food processing industries.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Industrial Duct Dust Collection Market.- Nordfab Ducting
- Nederman Holding AB
- Donaldson Company, Inc.
- CECO Environmental
- Camfil APC
- American Fabric Filter Co.
- Imperial Systems, Inc.
- Dustvent, LLC
- US Duct
- Air Master Systems
- Kirk & Blum
- K&B Duct
- Spiral Manufacturing Co., Inc.
- Verantis Environmental Solutions Group
- Wagener Process Equipment
- Ducting Express Services Ltd
- Flexaust Inc.
- Masterduct, Inc.
Frequently Asked Questions
What is the main advantage of clamp-together ducting over traditional flanged ducting?
Clamp-together ducting allows for significantly faster installation and disassembly without the need for specialized tools or welding. This modularity is ideal for facilities that frequently change production layouts or require regular internal cleaning to prevent dust buildup.
How does ducting material choice affect the safety of an industrial facility?
Material choice is critical for managing risks like static electricity and corrosion. For example, in environments with combustible dust, ducting must be properly grounded to prevent sparks. Using the wrong material, such as galvanized steel for corrosive chemical fumes, can lead to leaks and structural failure, compromising the entire dust collection system.
What role does duct diameter play in dust collection efficiency?
Duct diameter determines the air velocity. If the diameter is too large, the velocity drops, causing dust to settle and clog the pipes. If it is too small, the static pressure increases, requiring more energy and potentially straining the collector's fan. Proper sizing is essential for maintaining transport velocity.
Which industry is currently the fastest adopter of advanced ducting systems?
The pharmaceutical industry is currently the fastest adopter. The shift toward more stringent global hygiene standards requires specialized stainless steel ducting with smooth interior welds to prevent bacterial growth and cross-contamination between product batches.
How is the move toward "Industry 4.0" impacting the industrial ducting market?
Industry 4.0 is introducing "Smart Ducting" where sensors monitor pressure, temperature, and dust accumulation. This data allows for predictive maintenance, meaning components are replaced only when necessary, and system performance is automatically adjusted to optimize energy use based on the number of active machines.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
