Solid Tumor Testing Market
Solid Tumor Testing Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711671 | Published On : November 11, 2026 |
Format : 


 | Author : Erika Grotto
Solid Tumor Testing Market Size
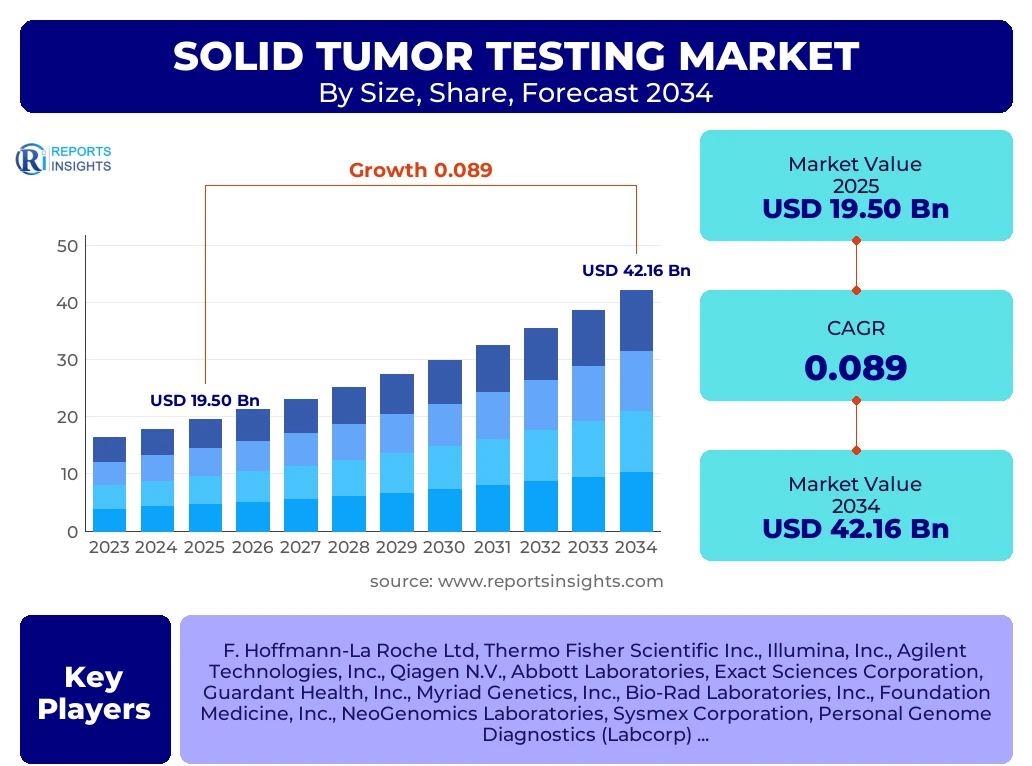
According to Reports Insights Consulting Pvt Ltd, The Solid Tumor Testing Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.9% between 2025 and 2034. The market is estimated at USD 21.24 Billion in 2026 and is projected to reach USD 42.16 Billion by the end of the forecast period in 2034.
Key Solid Tumor Testing Market Trends & Insights
The global landscape for solid tumor testing is undergoing a paradigm shift, driven by the integration of high-throughput technologies and the burgeoning field of personalized oncology. Stakeholders are increasingly focusing on the clinical utility of multi-gene panels and liquid biopsy techniques, which offer non-invasive alternatives to traditional tissue biopsies. The market is characterized by a transition from qualitative assessment to quantitative molecular profiling, enabling clinicians to identify actionable mutations with higher precision. Regional analysis suggests that while established markets maintain leadership through advanced infrastructure, emerging economies are witnessing rapid adoption due to improving healthcare expenditure and a rising burden of oncological disorders. Competitive benchmarking reveals a trend of strategic collaborations between diagnostic developers and pharmaceutical companies to create companion diagnostics, effectively bridging the gap between testing and targeted therapy.
- North America remains the largest region in terms of market share, supported by robust reimbursement frameworks and early adoption of Next-Generation Sequencing (NGS).
- The Asia-Pacific region is identified as the fastest-growing market, propelled by expanding diagnostic networks in China and India and increasing investments in genomic research.
- The Breast Cancer segment holds the largest share among applications, attributed to the high global prevalence of the disease and the standardized use of HER2 and BRCA testing.
- Next-Generation Sequencing (NGS) has emerged as the leading technology segment, surpassing traditional PCR due to its ability to detect multiple variants simultaneously.
Key Takeaways Solid Tumor Testing Market Size & Forecast
The forecast for the solid tumor testing market reflects a robust upward trajectory, underpinned by the increasing incidence of cancer and the global push for precision medicine. As healthcare systems move toward value-based care, the demand for accurate diagnostic tools that predict patient response to specific therapies is intensifying. The convergence of bioinformatics and molecular diagnostics is expected to further streamline data interpretation, making complex genomic information more accessible to oncologists. Furthermore, the expansion of testing services into decentralized settings, such as community hospitals and specialized diagnostic centers, is broadening the patient reach and driving volume growth across diverse geographical locations.
- The United States continues to lead the market, driven by a concentration of key industry players and favorable FDA approvals for novel diagnostic assays.
- Precision oncology is the primary catalyst for market expansion, with targeted therapies requiring mandatory companion diagnostic testing before administration.
- Growth in the geriatric population globally is a significant contributor to the rising volume of tumor testing procedures, as age remains a primary risk factor for solid malignancies.
- Digital pathology and artificial intelligence integration are becoming vital for enhancing the accuracy of histological assessments and reducing turnaround times.
Solid Tumor Testing Market Drivers Analysis
The primary driver for the solid tumor testing market is the escalating global prevalence of various cancer types, including lung, breast, and colorectal cancers. As the disease burden rises, there is a heightened demand for early-stage detection and frequent monitoring of tumor progression. This is complemented by the rapid technological evolution in molecular biology, where the cost of genomic sequencing has significantly decreased, making advanced testing more viable for a larger patient population. The shift from one-size-fits-all treatments to individualized therapeutic strategies necessitates comprehensive molecular profiling to identify specific genetic alterations that can be targeted by modern pharmacotherapy.
Furthermore, government initiatives and funding for large-scale genomic projects are providing the necessary impetus for market development. Programs aimed at mapping the cancer genome have yielded critical data that facilitate the development of new diagnostic markers. Additionally, the increasing awareness among patients and healthcare providers regarding the benefits of early diagnosis is leading to a higher rate of screening and diagnostic testing. The expansion of private health insurance coverage for genetic testing in several developed nations is also playing a crucial role in reducing the financial burden on patients, thereby increasing the adoption rates of high-end diagnostic tests.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in Next-Generation Sequencing (NGS) | +3.2% | Global (Primary: US, Germany, Japan) | 2025 - 2034 |
| Rising Incidence of Solid Malignancies | +2.5% | High Impact in APAC and Latin America | 2025 - 2034 |
| Expansion of Personalized Medicine and Targeted Therapies | +2.1% | North America and Europe | 2026 - 2032 |
Solid Tumor Testing Market Restraints Analysis
Despite the positive growth outlook, the solid tumor testing market faces significant hurdles, most notably the high cost associated with advanced molecular diagnostics. While the cost of sequencing has dropped, the overall expenditure including specialized equipment, high-purity reagents, and skilled personnel remains prohibitive for many healthcare facilities in developing regions. Furthermore, the complexity of data interpretation requires sophisticated bioinformatics tools and highly trained professionals, the shortage of which can lead to delays in clinical decision-making. These economic and technical barriers often limit the penetration of advanced testing to Tier-1 hospitals and academic research centers.
Another major restraint is the lack of standardized regulatory guidelines and reimbursement policies across different jurisdictions. In many countries, the process for obtaining approval for novel diagnostic assays is lengthy and stringent, which can stifle innovation and delay the market entry of breakthrough products. Additionally, reimbursement for multi-gene panels is often inconsistent, with some insurance providers only covering a limited number of biomarkers. This creates a disparity in access to care and poses a challenge for diagnostic companies trying to achieve widespread commercial success for their testing portfolios.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Equipment and Specialized Reagents | -1.8% | Developing Economies (Africa, SE Asia) | 2025 - 2030 |
| Stringent Regulatory and Reimbursement Hurdles | -1.4% | European Union and North America | 2025 - 2034 |
Solid Tumor Testing Market Opportunities Analysis
The emergence of liquid biopsy presents a monumental opportunity for the solid tumor testing market. By analyzing circulating tumor DNA (ctDNA) or circulating tumor cells (CTCs) from a simple blood draw, liquid biopsy offers a minimally invasive method for early detection, treatment monitoring, and the identification of minimal residual disease (MRD). This technology is particularly beneficial for patients with tumors that are difficult to access via traditional biopsy methods. As the clinical evidence for liquid biopsy continues to mount, its integration into routine clinical practice is expected to open new revenue streams for diagnostic companies and improve patient outcomes through real-time therapy adjustment.
Additionally, the integration of Artificial Intelligence (AI) and Machine Learning (ML) in oncology diagnostics is creating new avenues for growth. AI algorithms can process vast amounts of genomic and proteomic data far more rapidly and accurately than human analysts, identifying subtle patterns that may indicate drug resistance or potential therapeutic targets. The development of AI-driven diagnostic platforms can enhance the predictive power of tumor testing, providing clinicians with actionable insights that are both comprehensive and easy to interpret. Expansion into emerging markets, where healthcare infrastructure is being modernized, also offers a significant long-term growth opportunity for established market players.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Non-Invasive Liquid Biopsy Assays | +4.1% | Global | 2026 - 2034 |
| Integration of AI for Genomic Data Interpretation | +2.8% | US, China, South Korea | 2027 - 2034 |
Solid Tumor Testing Market Challenges Impact Analysis
One of the most persistent challenges in the solid tumor testing market is the high degree of intratumoral heterogeneity. Solid tumors are often composed of diverse cell populations with different genetic signatures, which can lead to sampling bias during tissue biopsies. This heterogeneity makes it difficult for a single test to accurately reflect the entire genetic landscape of the malignancy, potentially leading to incomplete treatment plans or the oversight of resistant sub-clones. Addressing this challenge requires more sophisticated sampling techniques and the use of longitudinal testing to track clonal evolution over time.
Ethical and privacy concerns regarding genomic data also pose a significant challenge. As tumor testing involves the analysis of sensitive genetic information, ensuring the security of patient data and maintaining patient confidentiality is paramount. Concerns over the potential misuse of genetic information by employers or insurance companies can lead to patient hesitation in undergoing comprehensive testing. Furthermore, the rapid pace of technological change requires continuous education for oncologists and pathologists, creating a gap between technological capability and clinical implementation that must be bridged through concerted professional development efforts.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period | |
|---|---|---|---|---|
| Intratumoral Heterogeneity and Sampling Bias | -1.2% | Global | Ongoing | |
| Data Privacy and Ethical Constraints in Genomics | -0.9% | Europe (GDPR impact) | 2025 - 2034 |
Solid Tumor Testing Market - Updated Report Scope
This comprehensive report provides a detailed analysis of the global solid tumor testing market, covering a wide array of tumor types, diagnostic technologies, and end-user segments. It examines the market dynamics through 2034, offering insights into the regulatory environment, competitive strategies, and the technological innovations driving the industry. The scope encompasses detailed regional analysis, providing a granular view of market trends across North America, Europe, Asia-Pacific, Latin America, and the Middle East and Africa.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 19.50 Billion |
| Market Forecast in 2034 | USD 42.16 Billion |
| Growth Rate | 8.9% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | F. Hoffmann-La Roche Ltd, Thermo Fisher Scientific Inc., Illumina, Inc., Agilent Technologies, Inc., Qiagen N.V., Abbott Laboratories, Exact Sciences Corporation, Guardant Health, Inc., Myriad Genetics, Inc., Bio-Rad Laboratories, Inc., Foundation Medicine, Inc., NeoGenomics Laboratories, Sysmex Corporation, Personal Genome Diagnostics (Labcorp), Invitae Corporation, Merck KGaA, PerkinElmer Inc., Promega Corporation |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market for solid tumor testing is segmented based on the methodology of analysis, the specific type of cancer being targeted, and the underlying technology utilized. This segmentation allows for a deeper understanding of where the highest growth potential lies and which technologies are becoming the standard of care. The genetic testing segment is currently witnessing the fastest growth as it provides the molecular basis for targeted therapy, whereas conventional histopathology remains the gold standard for initial diagnosis and staging.
- By Type:
- Genetic Testing (Molecular profiling, mutation analysis)
- Conventional Testing (Histopathology, Cytology)
- By Application:
- Breast Cancer (HER2, BRCA1/2, PIK3CA testing)
- Lung Cancer (EGFR, ALK, ROS1, KRAS, PD-L1 testing)
- Colorectal Cancer (KRAS, NRAS, BRAF, MSI/dMMR testing)
- Prostate Cancer
- Ovarian Cancer
- Other Solid Tumors (Pancreatic, Bladder, Melanoma)
- By Technology:
- Next-Generation Sequencing (NGS)
- Polymerase Chain Reaction (PCR)
- Immunohistochemistry (IHC)
- In Situ Hybridization (ISH - FISH/CISH)
- Mass Spectrometry
- By End-User:
- Hospitals & Clinics
- Reference Diagnostic Laboratories
- Academic & Research Institutes
Regional Highlights
- North America: The United States represents the largest market globally due to the high adoption of NGS, favorable reimbursement for multi-gene panels through CMS and private insurers, and the presence of world-leading oncology centers.
- Europe: Germany, the UK, and France are leading contributors, characterized by strong government support for genomic medicine and integrated cancer networks that facilitate standardized tumor testing protocols.
- Asia-Pacific: This is the fastest-growing region. China and India are experiencing a surge in demand driven by improving healthcare access, a massive patient pool, and increasing local manufacturing of diagnostic kits.
- Latin America: Countries like Brazil and Mexico are witnessing gradual growth as they modernize their diagnostic infrastructure and increase public-private partnerships in the healthcare sector.
- Middle East and Africa: Growth is primarily driven by the GCC countries, which are investing heavily in personalized medicine initiatives and advanced diagnostic laboratories to reduce the burden of chronic diseases.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Solid Tumor Testing Market.
- F. Hoffmann-La Roche Ltd
- Thermo Fisher Scientific Inc.
- Illumina, Inc.
- Agilent Technologies, Inc.
- Qiagen N.V.
- Abbott Laboratories
- Exact Sciences Corporation
- Guardant Health, Inc.
- Myriad Genetics, Inc.
- Bio-Rad Laboratories, Inc.
- Foundation Medicine, Inc.
- NeoGenomics Laboratories
- Sysmex Corporation
- Personal Genome Diagnostics (Labcorp)
- Invitae Corporation
- Merck KGaA
- PerkinElmer Inc.
- Promega Corporation
- QIAGEN
- Dako (Agilent)
Frequently Asked Questions
What is the projected growth rate of the Solid Tumor Testing Market?
The market is expected to grow at a Compound Annual Growth Rate (CAGR) of 8.9% from 2025 to 2034, driven by advancements in genomic sequencing and the rise in precision oncology.
Which technology is dominating the solid tumor testing landscape?
Next-Generation Sequencing (NGS) is the dominant technology because it allows for the simultaneous analysis of multiple gene variants, providing a comprehensive molecular profile of the tumor.
Which region currently leads the global market for tumor testing?
North America currently holds the largest market share, owing to its advanced healthcare infrastructure, high research and development spending, and widespread use of targeted therapies.
What are the key applications of solid tumor testing?
Major applications include testing for breast cancer, lung cancer, colorectal cancer, and prostate cancer, where molecular markers are used to guide therapy and monitor resistance.
How is liquid biopsy impacting the solid tumor testing market?
Liquid biopsy is acting as a significant growth catalyst by providing a non-invasive method to monitor tumor mutations and treatment efficacy via blood samples, overcoming the limitations of traditional tissue biopsies.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
