Service Provider Network Infrastructure Market
Service Provider Network Infrastructure Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711923 | Published On : November 21, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Service Provider Network Infrastructure Market Size
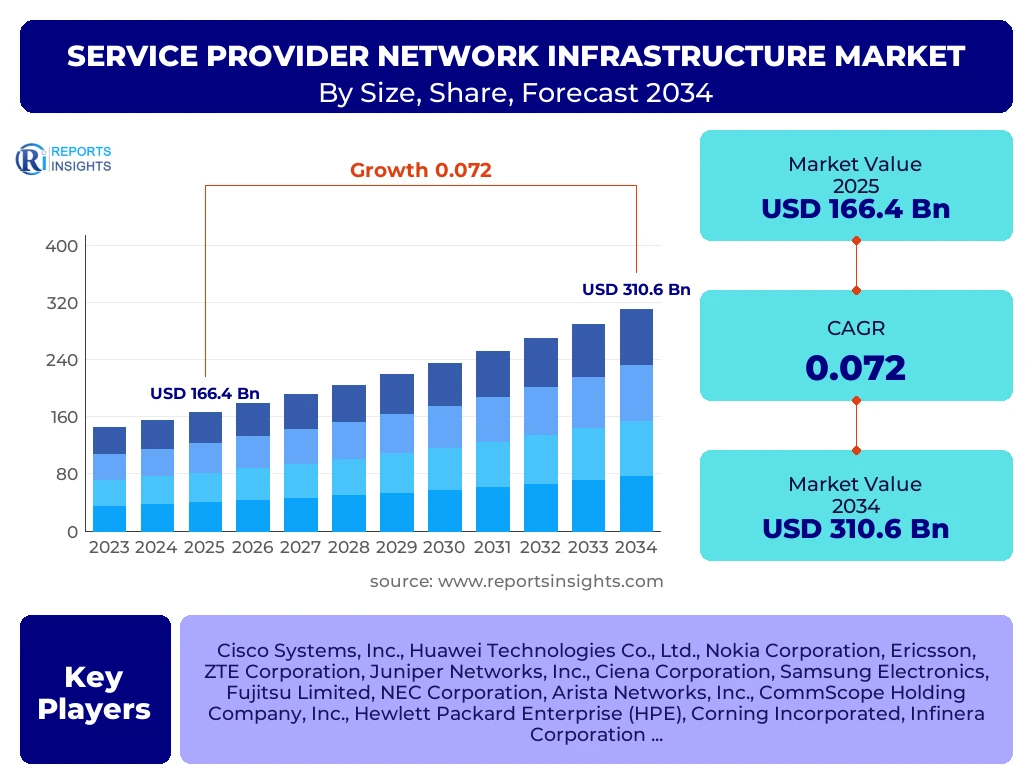
According to Reports Insights Consulting Pvt Ltd, The Service Provider Network Infrastructure Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.2% between 2025 and 2034. The market is estimated at USD 178.4 Billion in 2026 and is projected to reach USD 310.6 Billion by the end of the forecast period in 2034.
Key Service Provider Network Infrastructure Market Trends & Insights
The global connectivity landscape is currently undergoing a foundational transformation as telecommunications operators and internet service providers transition from legacy hardware-centric models to software-defined, cloud-native architectures. This shift is primarily dictated by the exponential surge in data consumption, the commercial maturation of 5G Standalone (SA) networks, and the integration of artificial intelligence at the network edge. Users and enterprise stakeholders are increasingly inquiring about the viability of Open Radio Access Networks (Open RAN) and the role of network slicing in monetizing next-generation infrastructure. Benchmarking reveals that established leaders are aggressively pivoting toward sustainable, energy-efficient networking hardware to align with global ESG mandates, while simultaneously investing in automated orchestration tools to manage the burgeoning complexity of multi-vendor environments.
- Largest Region: North America remains the dominant revenue contributor, sustained by early 5G adoption and massive investments in hyperscale data center connectivity.
- Fastest Growing Region: Asia-Pacific is anticipated to exhibit the highest CAGR due to rapid urbanization, digital transformation initiatives in India and Southeast Asia, and aggressive infrastructure expansion in China.
- Largest Segment: The Wireless Infrastructure segment, encompassing 5G RAN and core components, currently holds the largest market share as operators prioritize mobile broadband capacity.
- Emerging Trend: The adoption of AI-driven Predictive Maintenance is becoming a standard for reducing operational expenditure (OpEx) across distributed network footprints.
Key Takeaways Service Provider Network Infrastructure Market Size & Forecast
The trajectory of the Service Provider Network Infrastructure market is characterized by a strategic pivot toward decentralized architecture. Analysis of industry inquiries suggests that the primary concerns for stakeholders revolve around the interoperability of legacy systems with new virtualization layers and the long-term cost-benefits of migrating to 400G and 800G optical transport networks. The forecast period indicates a robust consolidation of service offerings where infrastructure is no longer just a pipe for data but an intelligent platform capable of hosting edge computing services. This evolution is critical for supporting the low-latency requirements of autonomous systems, industrial IoT, and immersive reality applications.
- Leading Country: The United States leads in technological innovation and private equity investment into specialized network security and orchestration software.
- Strategic Importance: Network densification through Small Cell deployment is identified as the most critical factor for achieving consistent 5G coverage in high-density urban environments.
- Market Maturity: While Western Europe shows signs of a mature market, the focus there has shifted heavily toward fiber-to-the-x (FTTx) expansions and the decommissioning of copper-based networks.
- Value Chain Shift: There is a visible transition of value from pure hardware manufacturers to software providers offering Network-as-a-Service (NaaS) models.
Service Provider Network Infrastructure Market Drivers Analysis
The primary catalysts for market expansion involve the relentless demand for high-speed internet and the structural shift toward cloud-based enterprise operations. As global digital traffic increases, service providers are compelled to upgrade their core and backhaul infrastructures to prevent bottlenecks. Furthermore, the proliferation of Internet of Things (IoT) devices creates a necessity for massive machine-type communications (mMTC), which only advanced network infrastructure can facilitate effectively. The integration of high-performance computing at the network edge also acts as a significant propellant, enabling real-time processing that traditional centralized architectures cannot support.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Acceleration of 5G Standalone (SA) Deployments | +2.4% | Global (Strongest in China, USA, South Korea) | 2025–2030 |
| Surge in Demand for Hyperscale Data Center Connectivity | +1.8% | North America and Western Europe | 2025–2034 |
| Explosion of IoT and Industrial Automation | +1.5% | Asia-Pacific and Germany | 2026–2034 |
Service Provider Network Infrastructure Market Restraints Analysis
Despite the positive growth outlook, the market faces significant headwinds, most notably the high capital expenditure (CapEx) required for next-generation hardware rollouts. Many service providers, particularly in emerging markets, struggle with the financial burden of spectrum auctions combined with the physical infrastructure costs. Additionally, the complexity of managing hybrid environments where legacy 3G/4G systems must coexist with 5G architecture creates technical friction and slows down the full implementation of unified software-defined networking (SDN) solutions. Regulatory hurdles and geopolitical tensions affecting vendor selection also present persistent obstacles to global supply chain stability.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Capital Expenditure for Fiber and 5G Infrastructure | -1.2% | Latin America and Africa | 2025–2028 |
| Geopolitical Trade Restrictions on Telecom Equipment | -0.8% | Global (Primarily US-China axis) | 2025–2034 |
Service Provider Network Infrastructure Market Opportunities Analysis
The most promising opportunities within the market lie in the commercialization of Edge Computing and the adoption of Open RAN (ORAN) architectures. By moving processing power closer to the end-user, service providers can offer new revenue-generating services such as ultra-low latency gaming, private 5G networks for smart factories, and enhanced localized content delivery. Open RAN presents an opportunity for service providers to break away from vendor lock-in, fostering a more competitive ecosystem that could lead to reduced long-term hardware costs and increased flexibility in network design. Additionally, the greening of networks through energy-efficient photonics and AI-managed power scaling represents a significant area for innovation.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Private 5G Networks for Enterprises | +1.6% | Germany, Japan, USA | 2026–2034 |
| Adoption of Open RAN and Virtualized RAN (vRAN) | +1.1% | Developed Markets | 2027–2034 |
Service Provider Network Infrastructure Market Challenges Impact Analysis
The primary challenges involve the escalating sophistication of cybersecurity threats targeting critical telecommunications infrastructure. As networks become more software-reliant and decentralized, the attack surface expands, requiring unprecedented levels of investment in zero-trust architectures and encrypted transport protocols. Furthermore, a significant talent gap exists; the industry requires a workforce skilled in both traditional RF engineering and modern cloud-native software development. Rapid technological obsolescence also poses a challenge, as hardware installed today may be surpassed by more efficient iterations within a shorter-than-expected lifecycle, complicating long-term investment strategies.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Vulnerabilities in Virtualized Networks | -0.9% | Global | 2025–2034 |
| Shortage of Skilled Cloud-Networking Professionals | -0.5% | North America and Europe | 2025–2030 |
Service Provider Network Infrastructure Market - Updated Report Scope
This comprehensive market report provides an exhaustive analysis of the global service provider network infrastructure sector, covering hardware, software, and managed service components across wireless and wireline technologies. The scope includes a detailed breakdown of the transition from 4G to 5G, the rise of software-defined networking (SDN), and the integration of optical transport evolution. The study evaluates the competitive landscape, regulatory frameworks, and technological roadmaps that will define the industry for the next decade.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 166.4 Billion |
| Market Forecast in 2034 | USD 310.6 Billion |
| Growth Rate | 7.2% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Cisco Systems, Inc., Huawei Technologies Co., Ltd., Nokia Corporation, Ericsson, ZTE Corporation, Juniper Networks, Inc., Ciena Corporation, Samsung Electronics, Fujitsu Limited, NEC Corporation, Arista Networks, Inc., CommScope Holding Company, Inc., Hewlett Packard Enterprise (HPE), Corning Incorporated, Infinera Corporation, Ribbon Communications, ADVA Optical Networking, Dell Technologies Inc., Mavenir Systems, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Service Provider Network Infrastructure market is segmented based on technology, component, and infrastructure type to provide a granular view of investment flows. The wireless infrastructure segment is currently the primary driver of market value, fueled by the global mandate for 5G coverage. However, the optical transport segment is witnessing a significant resurgence as the data heavy-lifting required by 5G and cloud services necessitates robust fiber backbones. Software-defined networking and virtualization are also emerging as high-growth sub-segments, as operators seek to decouple hardware from software to achieve greater operational agility and lower costs.
- By Technology: 5G remains the dominant growth engine, with 4G/LTE infrastructure still receiving maintenance and regional expansion investments in developing economies. IP/MPLS and Optical Transport are critical for core network scalability.
- By Infrastructure Type: Includes Radio Access Networks (RAN), Core Networks, and Backhaul. Small cell densification is a key focus area within wireless infrastructure to address urban capacity demands.
- By Component: Hardware maintains the largest share of historical revenue, but software and services are growing at a faster rate due to the industry-wide transition toward Network Functions Virtualization (NFV).
- By End-User: Traditional Tier-1 telecommunications companies are the largest spenders, while specialized internet service providers and cable operators are increasing their investment in high-speed fiber aggregation.
Regional Highlights
- North America: The region is the largest market by value, characterized by the presence of major hyperscalers and early-stage 5G SA adoption. The United States is a hub for SDN and NFV innovation.
- Asia-Pacific: This is the fastest-growing region, led by massive infrastructure projects in China and India. Government-led digital initiatives and a huge subscriber base drive the demand for high-capacity networking equipment.
- Europe: The market is focused on digital sovereignty and the rollout of fiber networks. Strict regulatory environments regarding vendor security and data privacy influence infrastructure procurement strategies.
- Latin America: Growth is steady, driven by the ongoing transition from 3G to 4G and the initial stages of 5G auctions in Brazil and Mexico.
- Middle East & Africa: Significant investments are being made in the GCC countries for smart city initiatives, while other parts of the region focus on expanding basic broadband connectivity through satellite and terrestrial wireless.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Service Provider Network Infrastructure Market.
- Cisco Systems, Inc.
- Huawei Technologies Co., Ltd.
- Nokia Corporation
- Ericsson
- ZTE Corporation
- Juniper Networks, Inc.
- Ciena Corporation
- Samsung Electronics
- Fujitsu Limited
- NEC Corporation
- Arista Networks, Inc.
- CommScope Holding Company, Inc.
- Hewlett Packard Enterprise (HPE)
- Corning Incorporated
- Infinera Corporation
- Ribbon Communications
- ADVA Optical Networking
- Dell Technologies Inc.
- Mavenir Systems, Inc.
- Extreme Networks, Inc.
Frequently Asked Questions
What is the projected market size of the Service Provider Network Infrastructure market by 2034?
The market is projected to reach approximately USD 310.6 Billion by 2034, growing at a steady CAGR of 7.2% from 2025.
Which technology segment is expected to lead the market growth?
The 5G technology segment is expected to lead the growth, particularly through the deployment of 5G Standalone (SA) cores and the expansion of the Radio Access Network (RAN).
How is AI influencing the Service Provider Network Infrastructure market?
AI is being integrated into network orchestration and management software to enable automated fault detection, traffic optimization, and predictive maintenance, significantly reducing operational costs.
What role does Open RAN play in the current market landscape?
Open RAN allows service providers to use interoperable hardware and software from different vendors, reducing vendor lock-in and fostering innovation through a more diverse ecosystem.
What are the main challenges facing network infrastructure providers?
Key challenges include high capital expenditure requirements, cybersecurity risks in virtualized environments, and geopolitical tensions that disrupt the global supply chain for critical components.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
