Encryption Market
Encryption Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711641 | Published On : November 10, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Encryption Market Size
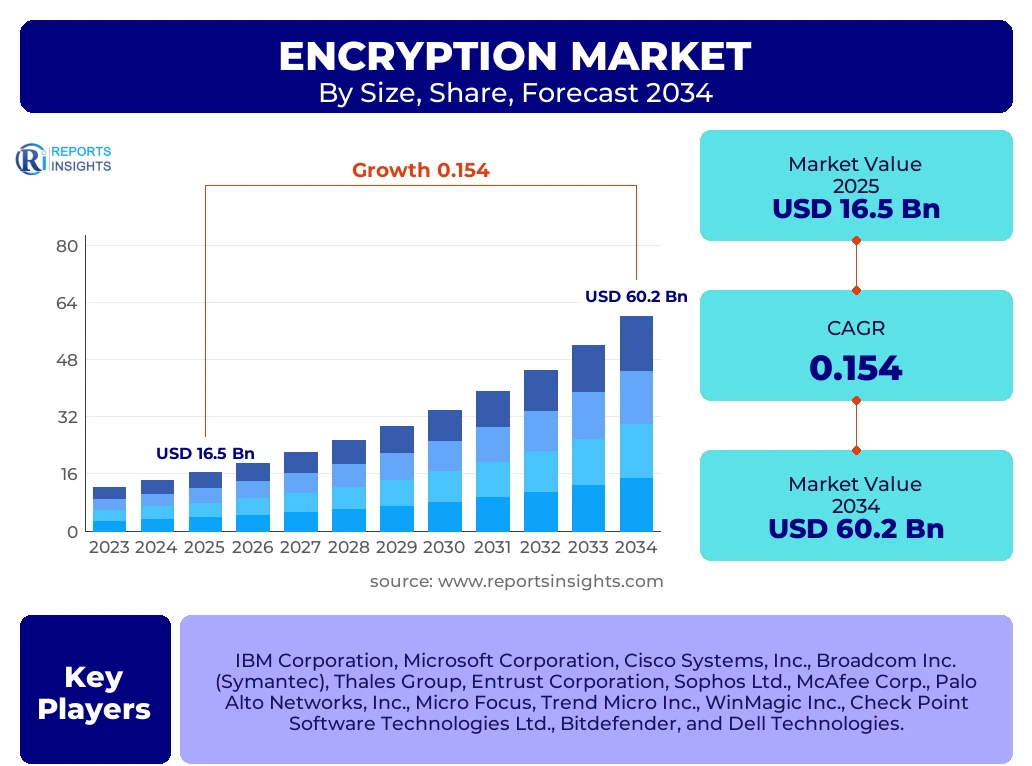
According to Reports Insights Consulting Pvt Ltd, The Encryption Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 15.4% between 2025 and 2034. The market is estimated at USD 19.04 Billion in 2026 and is projected to reach USD 60.2 Billion by the end of the forecast period in 2034.
Key Encryption Market Trends & Insights
The global encryption market is currently undergoing a paradigm shift driven by the convergence of hyper-connectivity and sophisticated cyber threats. Enterprises are transitioning from traditional perimeter-based security to data-centric models where encryption serves as the final line of defense. The proliferation of remote work, multi-cloud environments, and the rapid adoption of Internet of Things (IoT) devices have expanded the attack surface, making robust cryptographic solutions indispensable. Furthermore, the emergence of generative AI has introduced a dual-edged sword: while it enhances threat detection, it also empowers adversaries to conduct automated, high-frequency attacks, necessitating more resilient encryption protocols.
Regional dynamics indicate that North America maintains its leadership due to early adoption of advanced cybersecurity frameworks, while the Asia-Pacific region is emerging as the fastest-growing market, fueled by massive digital transformation initiatives in India and Southeast Asia. Within the technology landscape, there is a significant movement toward Post-Quantum Cryptography (PQC) as organizations prepare for the potential of quantum computers to break existing RSA and ECC algorithms. This trend is accompanied by an increased focus on Hardware Security Modules (HSM) and Transparent Data Encryption (TDE) as organizations seek to secure data both at rest and in transit without compromising operational performance.
- Largest Region: North America remains the dominant revenue contributor, accounting for over 38% of the total market share, driven by stringent data privacy laws such as CCPA and the presence of major technology providers.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR, exceeding 17%, as emerging economies invest heavily in digital infrastructure and national cybersecurity policies.
- Largest Segment by Component: The software segment currently holds the largest market share, as organizations prioritize scalable, cloud-native encryption platforms over localized hardware solutions.
- Leading Deployment Mode: Cloud-based deployment is outpacing on-premise solutions, reflecting the broader global migration toward SaaS-based security architectures and flexible consumption models.
Key Takeaways Encryption Market Size & Forecast
The market trajectory underscores a fundamental shift in how corporate and governmental entities perceive data integrity. The exponential growth in data volume, combined with the rising cost of data breaches—which now average millions of dollars per incident—is forcing a mandatory adoption of encryption across all verticals. We observe a trend where encryption is no longer an optional security layer but a foundational requirement for business continuity and regulatory adherence. The integration of AI and machine learning into encryption management platforms is also expected to streamline key management lifecycle processes, reducing the administrative burden on IT departments.
- BFSI Dominance: The Banking, Financial Services, and Insurance (BFSI) sector remains the primary end-user, utilizing encryption for securing cross-border transactions and sensitive customer intelligence.
- Regulatory Catalysts: Global mandates like GDPR in Europe and the HIPAA in the United States act as continuous growth drivers, mandating end-to-end encryption for sensitive personal and health data.
- Strategic Focus on SMEs: Small and Medium Enterprises (SMEs) are becoming a vital growth pocket as providers launch cost-effective, managed encryption services (Encryption-as-a-Service) tailored for smaller budgets.
- Zero Trust Integration: Encryption is becoming a core component of Zero Trust Architecture (ZTA), ensuring that data is protected regardless of where it resides or who is accessing it.
Encryption Market Drivers Analysis
The acceleration of the encryption market is primarily fueled by the escalating frequency of sophisticated data breaches and the subsequent financial and reputational damages. As organizations migrate their critical assets to the cloud, the necessity for robust encryption to protect data in multi-tenant environments has become paramount. Additionally, the tightening of global data residency and sovereignty laws is compelling multinational corporations to implement localized encryption strategies to remain compliant across different jurisdictions.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Surge in High-Profile Data Breaches | +4.2% | Global (United States, UK, Germany) | 2025-2034 |
| Expansion of Cloud-Based Services | +3.8% | North America and Europe | 2025-2030 |
| Stringent Regulatory Compliance (GDPR/HIPAA) | +3.5% | European Union and North America | 2025-2034 |
| Growth of IoT and Connected Devices | +2.9% | Asia-Pacific (China, India, Japan) | 2026-2034 |
Encryption Market Restraints Analysis
Despite the high demand, several factors hinder the universal adoption of advanced encryption technologies. High implementation and maintenance costs remain a significant barrier for smaller organizations. Furthermore, the complexity associated with managing cryptographic keys across diverse IT environments often leads to operational bottlenecks. In some jurisdictions, government regulations regarding "backdoor" access to encrypted data for law enforcement create a climate of uncertainty for service providers and enterprises concerned about absolute privacy.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Investment and Operational Costs | -1.8% | Emerging Markets (Latin America, Africa) | 2025-2028 |
| Complexity in Key Management Lifecycle | -1.2% | Global | 2025-2034 |
| Regulatory Conflict Over Encryption Standards | -0.9% | Middle East and Asia | 2025-2030 |
Encryption Market Opportunities Analysis
The market is ripe with opportunities, particularly in the realm of emerging technologies. Homomorphic encryption, which allows for data processing without decryption, is gaining traction in the healthcare and research sectors as it enables data collaboration while maintaining strict privacy. There is also a burgeoning market for mobile device encryption as organizations embrace Bring Your Own Device (BYOD) policies. The transition toward Post-Quantum Cryptography presents a massive upgrade cycle opportunity for hardware and software vendors over the next decade.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Post-Quantum Cryptography | +4.8% | Global (Advanced Economies) | 2028-2034 |
| Rise of Homomorphic Encryption in Research | +3.1% | North America and Europe | 2026-2034 |
| Increased Demand for Mobile Encryption | +2.7% | Asia-Pacific and Latin America | 2025-2030 |
Encryption Market Challenges Impact Analysis
Technical challenges continue to evolve alongside the market. The primary concern is the performance overhead; intensive encryption processes can lead to latency issues in high-speed data processing environments. Moreover, the global shortage of cybersecurity professionals capable of architecting complex encryption frameworks poses a significant risk to deployment timelines. The risk of "harvest now, decrypt later" strategies by malicious actors targeting currently encrypted data for future quantum-based decryption also looms large.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Performance Latency in Real-time Applications | -1.5% | Global | 2025-2034 |
| Cybersecurity Skill Gap and Talent Shortage | -2.2% | Global (High Impact in North America) | 2025-2030 |
| Standardization of Post-Quantum Protocols | -1.1% | Global | 2025-2027 |
Encryption Market - Updated Report Scope
This report provides a granular analysis of the global encryption landscape, covering software, hardware, and service components. It examines deployment models across cloud and on-premise environments and evaluates vertical-specific adoption rates. The scope includes a detailed forecast period from 2026 to 2034, with a base year of 2025, providing stakeholders with actionable intelligence on market sizing, competitive positioning, and technological evolution.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 16.5 Billion |
| Market Forecast in 2034 | USD 60.2 Billion |
| Growth Rate | 15.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | IBM Corporation, Microsoft Corporation, Cisco Systems, Inc., Broadcom Inc. (Symantec), Thales Group, Entrust Corporation, Sophos Ltd., McAfee Corp., Palo Alto Networks, Inc., Micro Focus, Trend Micro Inc., WinMagic Inc., Check Point Software Technologies Ltd., Bitdefender, and Dell Technologies. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The encryption market is segmented to reflect the diverse needs of modern IT infrastructures, ranging from individual endpoint protection to massive database and network-level security. Software remains the dominant component as it offers the flexibility required for cloud-native architectures, while hardware segments, particularly HSMs, are seeing renewed growth in sectors requiring high-assurance security like finance and government. Application-wise, cloud encryption is witnessing the fastest growth due to the global shift toward hybrid-cloud environments.
- By Component:
- Software (Platform and standalone solutions)
- Hardware (HSMs, encrypted USBs, and self-encrypting drives)
- Services (Professional and Managed Services)
- By Deployment Mode:
- Cloud (SaaS, PaaS, IaaS encryption)
- On-premise (Local server-based installations)
- By Application:
- Endpoint Encryption
- Network Encryption
- Cloud Encryption
- Database Encryption
- Disk Encryption
- File/Folder Encryption
- By End-User Vertical:
- BFSI
- IT and Telecom
- Government and Defense
- Healthcare and Life Sciences
- Retail and E-commerce
- Manufacturing
- Others
Regional Highlights
The global encryption landscape is marked by distinct regional characteristics shaped by technological maturity and regulatory frameworks. North America remains the epicenter of innovation, with the US government’s push toward quantum-resistant standards setting the pace for the global market. Europe follows closely, where data privacy is treated as a fundamental right, necessitating widespread encryption adoption across all business sizes.
- North America: The largest market share holder, dominated by the United States. High concentration of security vendors and strict enforcement of data protection laws drive continuous investment.
- Europe: A mature market characterized by the GDPR. Countries like Germany, the UK, and France are leading in adopting sophisticated file and email encryption to avoid heavy non-compliance penalties.
- Asia-Pacific: The fastest-growing region. Rapid digitization in India, China, and Australia, coupled with increasing cyber-attacks, is compelling enterprises to adopt encryption at an unprecedented rate.
- Latin America: Showing steady growth, particularly in Brazil and Mexico, as financial institutions upgrade their digital security infrastructure.
- Middle East & Africa: Growth is driven by government initiatives in the GCC countries to build secure smart cities and robust national cybersecurity frameworks.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Encryption Market.- IBM Corporation
- Microsoft Corporation
- Cisco Systems, Inc.
- Broadcom Inc. (Symantec)
- Thales Group
- Entrust Corporation
- Sophos Ltd.
- McAfee Corp.
- Palo Alto Networks, Inc.
- Micro Focus
- Trend Micro Inc.
- WinMagic Inc.
- Check Point Software Technologies Ltd.
- Bitdefender
- Dell Technologies
- Fortinet, Inc.
- Gemalto (acquired by Thales)
- F-Secure Corporation
- Proofpoint, Inc.
- ESET, spol. s r.o.
Frequently Asked Questions
What is the projected growth rate of the Encryption Market?
The global encryption market is expected to grow at a Compound Annual Growth Rate (CAGR) of 15.4% from 2025 to 2034, reaching a total valuation of USD 60.2 Billion by the end of the forecast period.
Who are the leading players in the encryption industry?
The market is led by major technology and security firms including IBM, Microsoft, Thales Group, Cisco, and Broadcom (Symantec), which provide a mix of hardware, software, and managed security services.
Which region is expected to grow the fastest in the forecast period?
The Asia-Pacific region is projected to be the fastest-growing market, driven by rapid industrialization, digital transformation in emerging economies like India and China, and increasing awareness of data security.
What is the impact of Quantum Computing on the encryption market?
Quantum computing poses a significant challenge to current encryption standards like RSA. This has triggered a shift toward Post-Quantum Cryptography (PQC), creating a new growth avenue as organizations upgrade to quantum-resistant algorithms.
Why is the BFSI sector a major adopter of encryption technologies?
The BFSI sector handles vast amounts of sensitive financial and personal data, making it a prime target for cyber-attacks. High regulatory standards and the need for secure digital transactions make encryption a critical requirement for this vertical.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
