Service Orchestration Market
Service Orchestration Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711837 | Published On : November 18, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Service Orchestration Market Size
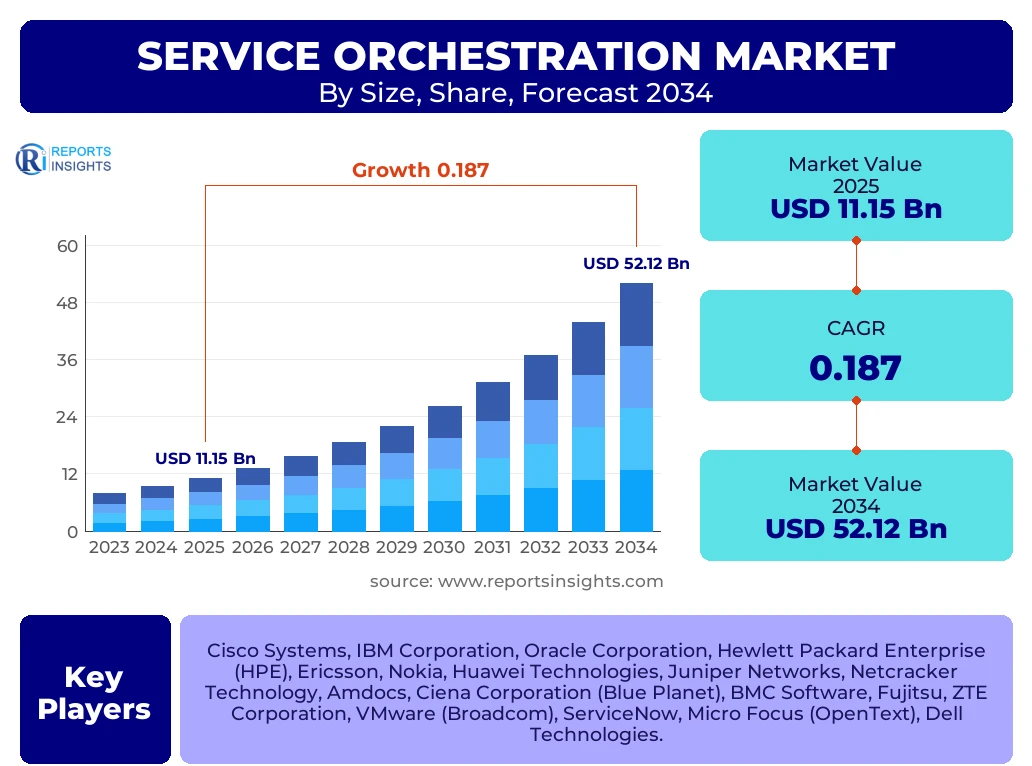
According to Reports Insights Consulting Pvt Ltd, The Service Orchestration Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 18.7% between 2025 and 2034. The market is estimated at USD 13.24 Billion in 2026 and is projected to reach USD 52.12 Billion by the end of the forecast period in 2034.
Key Service Orchestration Market Trends & Insights
The global service orchestration landscape is undergoing a radical transformation as enterprises pivot toward autonomous, self-healing networks and multi-cloud environments. Market analysis indicates that the integration of Artificial Intelligence (AI) and Machine Learning (ML) into orchestration platforms—often referred to as AIOps—is becoming the primary differentiator for vendors. Regional insights suggest that while North America remains the technological hub for early adoption, the Asia-Pacific region is experiencing the most rapid acceleration due to massive investments in 5G infrastructure and digital-first initiatives in emerging economies. Competitive benchmarking reveals a shift from monolithic orchestration suites to modular, microservices-based architectures that allow for greater agility and reduced vendor lock-in. Furthermore, the rise of edge computing is necessitating a more decentralized approach to orchestration, where services must be managed across a distributed fabric of local and centralized nodes.
- Largest Region: North America holds the highest market share, driven by a mature telecommunications sector and the rapid transition of large enterprises to hybrid cloud models.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR through 2034, fueled by large-scale digital transformation projects in China, India, and Southeast Asia.
- Leading Segment by Component: The Software and Platform segment currently dominates the market as organizations prioritize the deployment of core orchestration engines over consulting services.
- Leading Segment by Deployment: Cloud-based deployment models are outpacing on-premise installations, reflecting the broader industry trend toward scalable and flexible operational frameworks.
- Dominant End-User: Communication Service Providers (CSPs) represent the largest revenue-generating segment, necessitated by the complexity of managing 5G network slicing and virtualized functions.
Key Takeaways Service Orchestration Market Size & Forecast
The forecast for the service orchestration market points toward a decade of sustained growth driven by the "automation-first" mindset across the BFSI, Telecom, and Manufacturing sectors. Stakeholders are increasingly focusing on the orchestration of end-to-end workflows rather than isolated silos, aiming to achieve "Zero-Touch" operations. This strategic shift is reflected in the market size projections, which anticipate a fourfold increase in value over the next nine years. The demand for cross-domain orchestration, which bridges the gap between IT and network operations, is identified as a critical success factor for modern enterprises looking to optimize their total cost of ownership (TCO) and improve service delivery speeds.
- Market Valuation: The total addressable market is expected to surpass the USD 50 Billion mark by 2034, highlighting the essential nature of orchestration in modern IT stacks.
- Regional Leadership: The United States and China remain the two most influential countries, accounting for a significant portion of the global investment in orchestration technologies.
- Operational Efficiency: Implementation of advanced orchestration solutions is linked to a 30% to 45% reduction in operational expenditure for Tier-1 telecommunication operators.
- Strategic Shift: Transition from reactive troubleshooting to proactive, intent-based orchestration is a primary objective for nearly 70% of Fortune 500 companies.
- Growth Engine: The proliferation of Internet of Things (IoT) devices is a secondary but powerful driver, requiring sophisticated orchestration to manage millions of concurrent connections.
Service Orchestration Market Drivers Analysis
The primary catalyst for the service orchestration market is the escalating complexity of hybrid and multi-cloud infrastructures. As organizations deploy workloads across diverse environments—including public clouds, private data centers, and edge locations—the need for a unified management layer becomes imperative. Additionally, the rapid rollout of 5G technology demands dynamic network slicing and resource allocation that can only be achieved through automated orchestration. Business-level drivers include the pressure to reduce time-to-market for new services and the ongoing necessity to minimize human error in configuration management, which remains a leading cause of network downtime.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of 5G and Network Slicing | +5.2% | Global (Leading in APAC and North America) | 2025 - 2030 |
| Adoption of Hybrid and Multi-Cloud Strategies | +4.8% | North America and Europe | 2025 - 2034 |
| Need for Operational Cost Reduction (OpEx) | +3.5% | Global | 2026 - 2034 |
| Rise of AI-Driven Autonomous Operations | +3.2% | Developed Economies | 2027 - 2034 |
Service Orchestration Market Restraints Analysis
Despite the robust growth projections, the market faces significant headwinds from the persistence of legacy infrastructure. Many enterprises are burdened by "technical debt," where older systems lack the APIs or compatibility required for seamless orchestration integration. Furthermore, the lack of standardized protocols across different vendors creates silos that hinder end-to-end visibility. Security concerns also act as a restraint, as centralized orchestration platforms become high-value targets for cyberattacks, leading to cautious adoption in highly regulated sectors like defense and healthcare.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration Challenges with Legacy Systems | -2.1% | Europe and North America | 2025 - 2029 |
| High Initial Implementation Costs | -1.5% | Emerging Markets (MEA, Latin America) | 2025 - 2028 |
| Complexity in Multi-Vendor Environments | -1.2% | Global | 2025 - 2030 |
Service Orchestration Market Opportunities Analysis
Significant opportunities reside in the integration of edge computing with orchestration frameworks. As data processing moves closer to the source (IoT devices, autonomous vehicles), the demand for "Edge Orchestration" is skyrocketing. Another major opportunity exists in the development of intent-based networking (IBN) solutions, where the orchestrator translates high-level business policies into technical configurations automatically. Service providers also have the opportunity to offer "Orchestration-as-a-Service" (OaaS) to Small and Medium Enterprises (SMEs) that lack the internal expertise to manage complex automation platforms.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Edge Computing Orchestration | +4.5% | China, USA, Germany | 2026 - 2034 |
| Intent-Based Networking (IBN) Development | +3.8% | Global | 2027 - 2034 |
| Orchestration for Private 5G Networks | +2.9% | Japan, South Korea, Germany | 2026 - 2032 |
Service Orchestration Market Challenges Impact Analysis
The most pressing challenge is the widening skills gap in the global workforce. Designing and maintaining sophisticated orchestration workflows requires a blend of software engineering and traditional networking expertise, a combination that is currently in short supply. Additionally, data sovereignty and local privacy regulations (such as GDPR) complicate the orchestration of services that span multiple geographic regions. The rapid pace of technological change also creates a challenge where platforms may become obsolete within a few years if they are not built on flexible, open-standard architectures.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Talent and Skill Shortages | -1.8% | Global | 2025 - 2034 |
| Regulatory and Data Residency Barriers | -1.4% | European Union, India | 2025 - 2034 |
| Interoperability Standards Lack | -1.1% | Global | 2025 - 2029 |
Service Orchestration Market - Updated Report Scope
This report provides a comprehensive examination of the Service Orchestration Market, encompassing software platforms, managed services, and professional consulting. It analyzes the lifecycle of service delivery from initial provisioning and configuration to ongoing optimization and decommissioning. The scope includes cross-industry applications with a specific focus on Telecommunications, IT and ITeS, BFSI, Manufacturing, Healthcare, and Government sectors. Geographic analysis covers key performance indicators across major global regions and 20+ sub-countries. The study utilizes a data-driven methodology to correlate macroeconomic factors with industry-specific technology adoption rates to provide accurate forecast models.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 11.15 Billion |
| Market Forecast in 2034 | USD 52.12 Billion |
| Growth Rate | 18.7% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Cisco Systems, IBM Corporation, Oracle Corporation, Hewlett Packard Enterprise (HPE), Ericsson, Nokia, Huawei Technologies, Juniper Networks, Netcracker Technology, Amdocs, Ciena Corporation (Blue Planet), BMC Software, Fujitsu, ZTE Corporation, VMware (Broadcom), ServiceNow, Micro Focus (OpenText), Dell Technologies. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Service Orchestration market is segmented based on the structural components required for deployment and the specific operational functions they perform. The software segment remains the primary engine of growth, specifically orchestration engines that utilize TOSCA (Topology and Orchestration Specification for Cloud Applications) or YANG models to define service templates. Deployment models are shifting rapidly toward Cloud-Native architectures, leveraging Docker and Kubernetes to ensure that orchestration layers are as scalable as the microservices they manage. Vertical-specific segmentation shows that while Telecom is the most mature, Manufacturing is emerging as a high-growth vertical due to the Industry 4.0 movement and the need to orchestrate robotics and supply chain sensors.
- By Component:
- Software Platforms (Orchestration Engines, Controllers)
- Services (Consulting, Implementation, Support & Maintenance)
- By Deployment:
- Public Cloud
- Private Cloud / Hybrid Cloud
- On-Premise
- By Organization Size:
- Large Enterprises (Revenue > $1B)
- Small and Medium Enterprises (SMEs)
- By Vertical:
- Telecommunications (5G, NFV, SDN)
- BFSI (Digital Banking, Fintech Integration)
- Healthcare (Telemedicine, Data Management)
- Manufacturing (Industrial IoT, Smart Factories)
- Retail & E-commerce
Regional Highlights
Geographic analysis reveals distinct maturity levels and growth patterns across the global market. North America currently leads the market, primarily due to the presence of major technology vendors and the aggressive adoption of 5G and hybrid cloud by U.S.-based enterprises. Europe follows closely, with a strong focus on security and data sovereignty-driven orchestration solutions, particularly in Germany and the UK. The Asia-Pacific region is the "growth engine" of the market, where rapid urbanization and government-led digital initiatives are forcing a leapfrog effect from manual processes to automated orchestration. The Middle East and Africa are seeing niche growth in the oil and gas sector and smart city projects, while Latin America is gradually modernizing its telecom infrastructure.
- North America: The largest market share holder; dominated by the United States due to high R&D investment and early adoption of AI-orchestration.
- Europe: Leading in the adoption of open-source orchestration standards and strict adherence to regulatory compliance (GDPR/GAIA-X).
- Asia-Pacific: The fastest-growing region with China and India leading in 5G infrastructure spend and massive scale cloud migrations.
- Middle East & Africa: Growth driven by large-scale digital transformation in Saudi Arabia (Vision 2030) and the UAE.
- Latin America: Developing market with significant potential in Brazil and Mexico as telecom operators upgrade to 4G/5G hybrid networks.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Service Orchestration Market.- Cisco Systems, Inc.
- IBM Corporation
- Oracle Corporation
- Hewlett Packard Enterprise (HPE)
- Telefonaktiebolaget LM Ericsson
- Nokia Corporation
- Huawei Technologies Co., Ltd.
- Juniper Networks, Inc.
- Netcracker Technology (NEC Corporation)
- Amdocs
- Ciena Corporation (Blue Planet)
- BMC Software, Inc.
- Fujitsu Limited
- ZTE Corporation
- VMware by Broadcom
- ServiceNow, Inc.
- Micro Focus (OpenText)
- Dell Technologies
- Red Hat (IBM)
- T-Systems International
Frequently Asked Questions
What is the current market size of the global Service Orchestration market?
The global Service Orchestration market is estimated to be valued at approximately USD 11.15 Billion in 2025 and is projected to reach USD 52.12 Billion by 2034, growing at a CAGR of 18.7%.
What are the primary drivers for Service Orchestration adoption?
The main drivers include the rollout of 5G networks, the shift toward hybrid and multi-cloud environments, and the urgent need for enterprises to reduce operational costs through automated lifecycle management.
Which region is expected to grow the fastest during the forecast period?
The Asia-Pacific (APAC) region is expected to be the fastest-growing market, driven by rapid digitalization, government investments in smart infrastructure, and high 5G penetration in countries like China and South Korea.
How does AI impact the Service Orchestration market?
AI enables "AIOps" or autonomous orchestration, allowing systems to predict failures, automatically scale resources, and optimize network performance without human intervention, which significantly boosts efficiency and reliability.
What are the key challenges facing Service Orchestration vendors?
Major challenges include the difficulty of integrating with complex legacy systems, a global shortage of specialized talent, and the lack of unified industry standards for multi-vendor interoperability.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
