Private LTE 5G Network Market
Private LTE 5G Network Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711495 | Published On : November 04, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Private LTE 5G Network Market Size
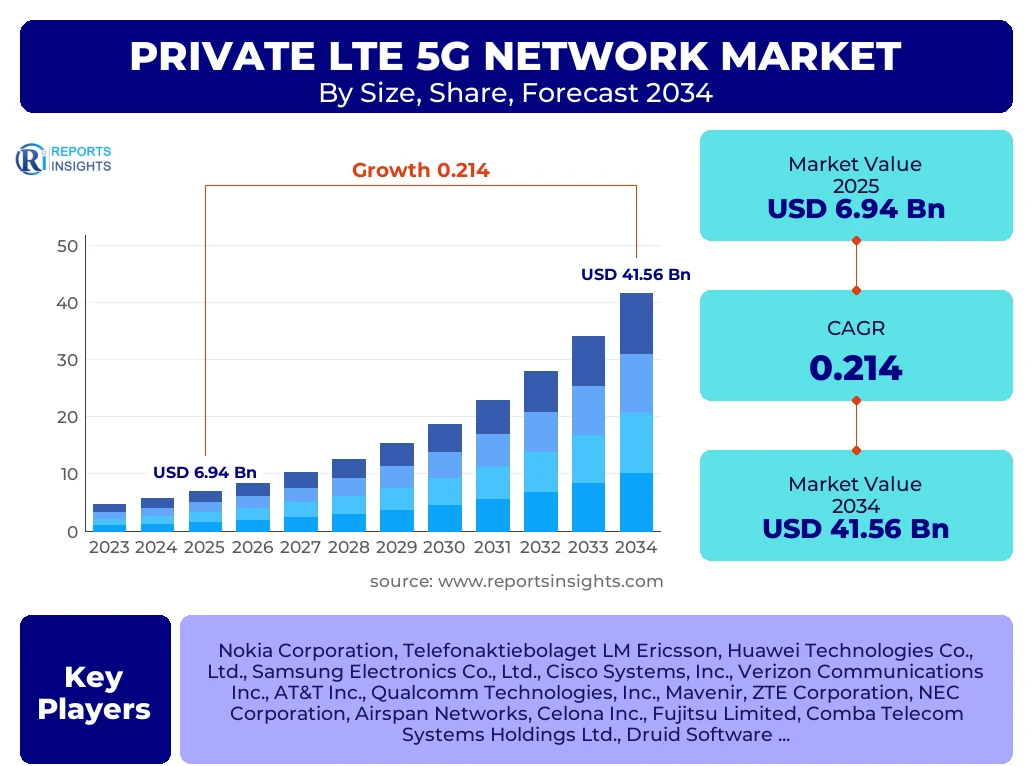
According to Reports Insights Consulting Pvt Ltd, The Private LTE 5G Network Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 21.4% between 2025 and 2034. The market is estimated at USD 8.42 Billion in 2026 and is projected to reach USD 41.56 Billion by the end of the forecast period in 2034.
Key Private LTE 5G Network Market Trends & Insights
The global landscape for private cellular networks is undergoing a fundamental shift as industrial entities prioritize digital sovereignty and ultra-reliable low-latency communications (URLLC). Current market intelligence suggests that the convergence of Operational Technology (OT) and Information Technology (IT) is the primary catalyst for Private 5G adoption. Organizations are increasingly moving away from legacy Wi-Fi systems in mission-critical environments due to handoff issues and interference vulnerabilities. Furthermore, the democratization of spectrum, such as the Citizens Broadband Radio Service (CBRS) in the United States and localized spectrum licensing in Germany, Japan, and the United Kingdom, has lowered the entry barrier for non-telecom enterprises to deploy and manage their own dedicated infrastructure.
- Largest Region: North America remains the dominant revenue contributor due to early adoption of CBRS and high concentration of tech-forward industrial hubs.
- Fastest Growing Region: Asia-Pacific is anticipated to exhibit the highest CAGR, fueled by massive investments in smart manufacturing in China, South Korea, and India.
- Leading Segment: The Manufacturing vertical holds the largest market share as Industry 4.0 initiatives demand deterministic networking for autonomous mobile robots (AMRs) and predictive maintenance.
- Technology Shift: While Private LTE currently supports the bulk of legacy IoT devices, the transition to Standalone (SA) 5G is accelerating for greenfield deployments requiring high bandwidth and network slicing.
Key Takeaways Private LTE 5G Network Market Size & Forecast
Market data indicates that the scalability of Private 5G is no longer theoretical but a core component of enterprise architecture. Stakeholders are shifting focus from trial phases to full-scale commercial deployments, particularly in isolated environments such as mines, offshore oil rigs, and large-scale logistics centers. The forecast period 2026-2034 will see a significant surge in Managed Service Provider (MSP) models, allowing smaller enterprises to utilize private networks without the burden of heavy internal technical expertise. Strategic partnerships between cloud hyperscalers and traditional telecom equipment manufacturers are expected to redefine the value chain by integrating edge computing directly into the private network core.
- Dominant Country: The United States leads in value due to the maturity of the private wireless ecosystem and diverse spectrum availability.
- Infrastructure Evolution: Virtualized and Open RAN (O-RAN) architectures are gaining traction, providing enterprises with vendor flexibility and reduced long-term CAPEX.
- Security Superiority: Enhanced SIM-based security and localized data processing are driving adoption in sensitive sectors like Defense and Healthcare.
- Market Maturity: By 2030, the replacement of aging Wi-Fi 5/6 systems in heavy industrial plants with Private 5G will be a primary revenue driver.
Private LTE 5G Network Market Drivers Analysis
The expansion of the Private LTE and 5G market is driven by the necessity for guaranteed Quality of Service (QoS) that public networks cannot provide. Industrial automation, the rise of the Internet of Things (IoT), and the demand for high-capacity, secure wireless data transmission are the fundamental engines of this growth.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Industry 4.0 and Smart Factory Initiatives | +6.2% | Global (Strongest in Germany/China) | 2025 - 2034 |
| Spectrum Liberalization Policies | +5.5% | USA, UK, Germany, Japan | 2025 - 2030 |
| Demand for Ultra-Reliable Low-Latency (URLLC) | +4.8% | North America & APAC | 2026 - 2034 |
| Heightened Data Security and Privacy Needs | +3.9% | Europe & North America | 2025 - 2034 |
Private LTE 5G Network Market Restraints Analysis
Despite the optimistic outlook, the market faces hurdles related to high initial implementation costs and the complexity of integrating cellular technology with existing legacy industrial hardware. The shortage of specialized workforce skilled in both cellular RF and industrial networking also acts as a bottleneck.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial CAPEX for Infrastructure | -2.5% | Developing Nations (LATAM/Africa) | 2025 - 2028 |
| Complexity of Legacy System Integration | -1.8% | Global | 2025 - 2030 |
| Regulatory Delays in Spectrum Allocation | -1.2% | South Asia and Middle East | 2025 - 2027 |
Private LTE 5G Network Market Opportunities Analysis
Emerging opportunities lie in the integration of Artificial Intelligence at the Edge (Edge AI) and the expansion of private networks into the public sector, such as smart cities and educational campuses. The "Network-as-a-Service" (NaaS) model presents a massive opportunity for telecom operators to diversify their revenue streams.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Network-as-a-Service (NaaS) Subscription Models | +5.1% | North America & Europe | 2026 - 2034 |
| Edge Computing Integration | +4.4% | Advanced Industrial Hubs | 2027 - 2034 |
| Public Safety and Government Applications | +3.2% | Global | 2025 - 2034 |
Private LTE 5G Network Market Challenges Impact Analysis
Interoperability between different vendor equipments and the management of interference in unlicensed bands remain significant technical challenges. Furthermore, competition from evolving Wi-Fi 7 standards poses a threat for less critical enterprise applications.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Vendor Interoperability and O-RAN Maturity | -1.5% | Global | 2025 - 2029 |
| Competition from Wi-Fi 7 Adoption | -2.1% | Commercial Office Environments | 2026 - 2030 |
| Workforce Skill Gaps | -1.0% | Global | 2025 - 2034 |
Private LTE 5G Network Market - Updated Report Scope
This report provides a granular analysis of the global private wireless market, covering the transition from LTE to 5G SA/NSA architectures. It examines the entire value chain, from chipsets and radio access network (RAN) equipment to core software and managed services. The scope includes a detailed breakdown of licensed, unlicensed, and shared spectrum models across diverse industry verticals.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 6.94 Billion |
| Market Forecast in 2034 | USD 41.56 Billion |
| Growth Rate | 21.4% CAGR |
| Number of Pages | 267 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Nokia Corporation, Telefonaktiebolaget LM Ericsson, Huawei Technologies Co., Ltd., Samsung Electronics Co., Ltd., Cisco Systems, Inc., Verizon Communications Inc., AT&T Inc., Qualcomm Technologies, Inc., Mavenir, ZTE Corporation, NEC Corporation, Airspan Networks, Celona Inc., Fujitsu Limited, Comba Telecom Systems Holdings Ltd., Druid Software, JMA Wireless. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented to reflect the diverse technological requirements across different economic sectors. The component segment is currently led by hardware, though software and services are expected to gain share as network virtualization becomes the norm. Vertical segmentation shows a heavy tilt toward heavy industries where traditional wireless solutions fail to meet performance benchmarks.
- By Component:
- Hardware (Radio Access Network, Core Networks, Backhaul & Transport)
- Software (Network Management, Orchestration)
- Services (Integration & Deployment, Support & Maintenance, Managed Services)
- By Technology:
- Private LTE (Long Term Evolution)
- Private 5G (Standalone and Non-Standalone architectures)
- By Spectrum:
- Licensed Spectrum (Exclusively held by MNOs or Enterprises)
- Unlicensed Spectrum (Open bands)
- Shared Spectrum (CBRS and similar frameworks)
- By Industry Vertical:
- Manufacturing (Automotive, Electronics, Heavy Machinery)
- Energy and Utilities (Oil & Gas, Smart Grids, Renewables)
- Mining (Autonomous Haulage, Remote Operation)
- Logistics and Transportation (Ports, Warehousing, Airports)
- Public Safety and Defense
- Healthcare (Connected Hospitals, Telemedicine)
- Retail and Hospitality
Regional Highlights
- North America: The largest market share holder, driven by the FCC's supportive stance on CBRS spectrum and the presence of major tech innovators. The region sees high adoption in logistics and defense.
- Asia-Pacific: The fastest-growing region. China leads in the number of Private 5G base stations deployed, primarily in mining and manufacturing sectors. Japan and South Korea are also major contributors due to local spectrum licensing for "Local 5G."
- Europe: Characterized by strong industrial policies (Industry 4.0). Germany is the regional leader, with companies like Siemens and Bosch operating their own private networks using the 3.7-3.8 GHz band.
- Middle East & Africa: Growth is concentrated in the energy sector, specifically for digitalizing oil and gas fields in the GCC countries to improve operational safety and efficiency.
- Latin America: Emerging market with growing interest in Brazil and Chile for mining applications, though spectrum availability remains a secondary challenge.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Private LTE 5G Network Market.- Nokia Corporation
- Telefonaktiebolaget LM Ericsson
- Huawei Technologies Co., Ltd.
- Samsung Electronics Co., Ltd.
- Cisco Systems, Inc.
- Verizon Communications Inc.
- AT&T Inc.
- Qualcomm Technologies, Inc.
- Mavenir
- ZTE Corporation
- NEC Corporation
- Airspan Networks
- Celona Inc.
- Fujitsu Limited
- Comba Telecom Systems Holdings Ltd.
- Druid Software
- JMA Wireless
- Athonet (a Hewlett Packard Enterprise company)
- Baicells Technologies
- T-Systems International GmbH
Frequently Asked Questions
What is the primary difference between Private LTE and Private 5G?
Private LTE is a mature technology based on 4G standards, suitable for high-speed data and voice with wide coverage. Private 5G offers significantly lower latency, higher device density (mMTC), and much higher data throughput (eMBB), making it ideal for real-time industrial automation and robotics.
Why are companies choosing Private 5G over Wi-Fi 6?
While Wi-Fi 6 is cost-effective, Private 5G provides superior mobility (handoff), better penetration in dense metallic environments, guaranteed bandwidth through network slicing, and enhanced SIM-based security, which are critical for mission-critical industrial operations.
What role does CBRS play in the Private LTE/5G market?
The Citizens Broadband Radio Service (CBRS) in the US allows for shared spectrum usage. It enables enterprises to deploy private cellular networks without needing to purchase expensive exclusive licenses from the government, significantly lowering the cost of entry.
Which industry vertical is expected to lead Private 5G adoption?
Manufacturing is the leading vertical. The need for "lights-out" manufacturing, autonomous mobile robots (AMRs), and real-time high-definition video inspection requires the deterministic performance that only Private 5G can provide.
How does network slicing benefit private enterprises?
Network slicing allows a single physical 5G network to be divided into multiple virtual networks. Each slice can be optimized for specific needs—such as one slice for ultra-low latency for robots and another for high-bandwidth video surveillance—ensuring performance isolation.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
