Sensor Fusion Market
Sensor Fusion Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711648 | Published On : November 10, 2026 |
Format : 


 | Author : Shamin Verma
Sensor Fusion Market Size
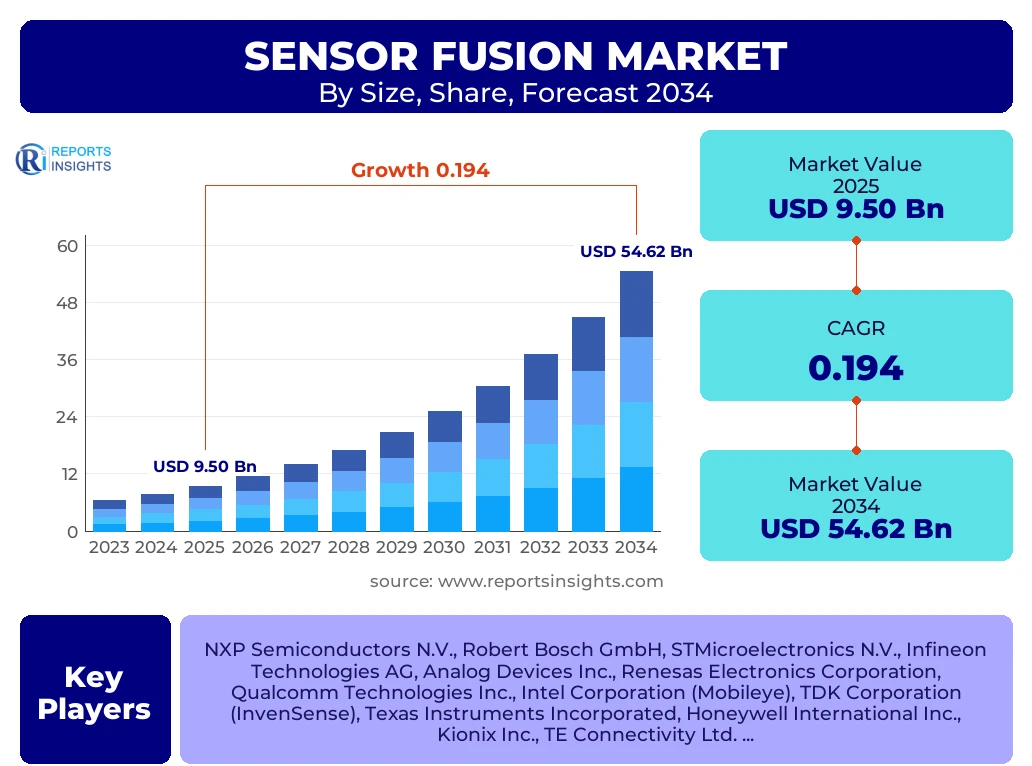
According to Reports Insights Consulting Pvt Ltd, The Sensor Fusion Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 19.4% between 2025 and 2034. The market is estimated at USD 11.34 Billion in 2026 and is projected to reach USD 54.62 Billion by the end of the forecast period in 2034.
Key Sensor Fusion Market Trends & Insights
The global landscape for sensor fusion technology is undergoing a transformative shift driven by the convergence of artificial intelligence, high-speed connectivity, and the escalating demand for autonomous systems. Industry participants are increasingly pivoting toward edge-based processing where data from multiple sensors—such as LiDAR, radar, and cameras—is synthesized locally to reduce latency. This trend is particularly dominant in the automotive and industrial robotics sectors, where split-second decision-making is critical for safety and operational efficiency. Furthermore, the integration of micro-electromechanical systems (MEMS) with sophisticated software algorithms is enabling more compact and power-efficient solutions for consumer electronics and wearable health devices.
- Largest Region: Asia-Pacific currently maintains the largest market share, driven by massive manufacturing hubs in China, Japan, and South Korea, coupled with the rapid adoption of smart city infrastructure.
- Fastest Growing Region: Asia-Pacific is also expected to witness the highest CAGR due to increasing investments in electric vehicles (EVs) and 5G-enabled IoT ecosystems.
- Largest Segment by Technology: The software segment is capturing a significant portion of the market value as the complexity of multi-sensor data integration requires advanced Kalman filters and machine learning models.
- Leading Vertical: The Automotive industry remains the primary revenue generator, specifically within Advanced Driver Assistance Systems (ADAS) and autonomous driving levels 3 and 4.
Key Takeaways Sensor Fusion Market Size & Forecast
The market trajectory suggests a robust expansion period as industries transition from simple sensing to intelligent perception. The forecast period between 2025 and 2034 will be characterized by a significant move toward "all-weather" sensing capabilities, where sensor fusion compensates for the limitations of individual sensors in adverse environmental conditions. This evolution is critical for the commercialization of fully autonomous transport and high-precision industrial automation. Stakeholders are focusing on modular architectures that allow for seamless scaling and updates, ensuring longevity in hardware deployments.
- Market Valuation: The leap from USD 11.34 Billion in 2026 to over USD 54 Billion by 2034 highlights a nearly fivefold growth in market scale.
- Strategic Pivot: A major transition is occurring from hardware-centric sales to software-defined sensing platforms, offering higher margins for technology providers.
- Regional Leader: China is emerging as the central node for sensor fusion production and consumption, particularly in the consumer electronics and automotive sectors.
- Technological Synergy: The synergy between 5G and sensor fusion is creating new opportunities in remote surgery and real-time asset tracking in logistics.
Sensor Fusion Market Drivers Analysis
The acceleration of the sensor fusion market is primarily fueled by the rigorous safety standards mandated by governments worldwide for the automotive sector. As regulatory bodies push for standardizing automatic emergency braking and lane-keep assist, the necessity for reliable sensor fusion becomes paramount. Additionally, the proliferation of the Internet of Things (IoT) across industrial landscapes (Industry 4.0) demands high-fidelity data that can only be achieved through the harmonious integration of diverse sensor types to monitor equipment health and optimize production cycles.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Proliferation of ADAS and Autonomous Vehicles | +6.5% | Global (Strongest in North America and Europe) | 2025 - 2034 |
| Explosive Growth of Wearable Healthcare Devices | +4.2% | United States, Japan, Germany | 2026 - 2030 |
| Industrial Automation and Industry 4.0 Initiatives | +3.8% | China, Germany, South Korea | 2025 - 2034 |
Sensor Fusion Market Restraints Analysis
Despite the optimistic growth outlook, the market faces significant hurdles related to the high cost of sophisticated sensor hardware like high-resolution LiDAR and the computational power required for real-time processing. Furthermore, the absence of standardized protocols for data fusion across different manufacturers creates interoperability challenges, slowing down the integration process in complex multi-vendor environments. Data privacy and security also remain top concerns, especially in consumer-facing applications where personal health or location data is synthesized.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Implementation and R&D Costs | -2.1% | Developing Economies (India, Brazil) | 2025 - 2028 |
| Complexity in Data Synchronization and Latency | -1.5% | Global | 2025 - 2034 |
Sensor Fusion Market Opportunities Analysis
The integration of AI-driven predictive analytics within sensor fusion frameworks presents a massive opportunity for the predictive maintenance market. By fusing thermal, acoustic, and vibration data, enterprises can anticipate machinery failures with unprecedented accuracy. Moreover, the rise of the "Metaverse" and Augmented Reality (AR) requires highly precise spatial awareness and gesture recognition, which are fundamentally reliant on advanced sensor fusion. This opens a new frontier for consumer-focused technology firms to innovate in human-machine interfaces.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in AR/VR and Spatial Computing | +5.1% | North America, East Asia | 2027 - 2034 |
| Emergence of Smart City Infrastructure | +3.4% | Middle East (NEOM), China, Singapore | 2026 - 2034 |
Sensor Fusion Market Challenges Impact Analysis
One of the most pressing challenges is the environmental reliability of fused systems. Ensuring that a system can maintain 99.99% accuracy in heavy rain, snow, or blinding sunlight remains a technical bottleneck for autonomous transport. Additionally, the global semiconductor supply chain volatility continues to pose a risk to the steady production of specialized sensor fusion chips, potentially leading to project delays and increased procurement costs for Tier 1 suppliers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Supply Chain Disruptions for Specialized ICs | -1.8% | Global | 2025 - 2027 |
| Stringent Regulatory Compliance and Certification | -1.2% | European Union (EU), North America | 2025 - 2030 |
Sensor Fusion Market - Updated Report Scope
This comprehensive report provides an in-depth analysis of the global sensor fusion ecosystem, covering hardware components, software algorithms, and end-user vertical applications. The study examines the competitive landscape, identifying key strategic moves such as mergers, acquisitions, and technological partnerships that are shaping the market. With a focus on the 2025-2034 forecast period, the report utilizes advanced statistical modeling to provide granular insights into regional growth drivers and the technological shift toward AI-integrated sensing solutions.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 9.50 Billion |
| Market Forecast in 2034 | USD 54.62 Billion |
| Growth Rate | 19.4% CAGR |
| Number of Pages | 256 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | NXP Semiconductors N.V., Robert Bosch GmbH, STMicroelectronics N.V., Infineon Technologies AG, Analog Devices Inc., Renesas Electronics Corporation, Qualcomm Technologies Inc., Intel Corporation (Mobileye), TDK Corporation (InvenSense), Texas Instruments Incorporated, Honeywell International Inc., Kionix Inc., TE Connectivity Ltd., Murata Manufacturing Co., Ltd., Broadcom Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the sensor fusion market reflects the diversity of its applications, ranging from high-precision military equipment to mass-market consumer gadgets. The hardware segment, while currently the largest by revenue, is seeing rapid commoditization, leading players to differentiate through proprietary software stacks. The software segment is expected to outpace hardware growth as AI and deep learning become integral to interpreting complex environmental data. Vertical-wise, the automotive sector dominates, but the healthcare sector is emerging as a high-growth area due to the fusion of bio-sensors in remote patient monitoring systems.
- By Component:
- Hardware (Inertial Sensors, Magnetic Sensors, Temperature Sensors, Image Sensors)
- Software (Kalman Filters, Bayesian Theory, Neural Networks)
- Services (Integration, Maintenance, Consulting)
- By Technology:
- MEMS (Micro-Electro-Mechanical Systems)
- Non-MEMS Technology
- By Vertical:
- Automotive (ADAS, V2X, Autonomous Driving)
- Consumer Electronics (Smartphones, Tablets, Wearables)
- Industrial (Robotics, Predictive Maintenance, Drones)
- Healthcare (Medical Imaging, Wearable Health Monitors)
- Aerospace & Defense (Navigation, Surveillance)
Regional Highlights
The regional distribution of the sensor fusion market is heavily influenced by the presence of technology giants and manufacturing infrastructure. Asia-Pacific leads the global market, accounting for over 40% of the total share, primarily due to the concentration of consumer electronics manufacturing in China and Vietnam, and advanced automotive electronics in Japan and South Korea. North America follows closely, characterized by intense R&D activities in autonomous vehicle testing and high adoption of smart home technologies. Europe’s market is anchored by its strong automotive heritage, with Germany being a critical hub for sensor fusion innovation in luxury and commercial vehicles. Meanwhile, the Middle East is witnessing a surge in demand due to massive smart city projects that integrate fused sensor networks for urban management.
- Asia-Pacific: Largest and fastest-growing region; dominant in consumer electronics and EV manufacturing.
- North America: Leader in AI-driven software innovation for sensor fusion and defense applications.
- Europe: Hub for automotive sensor standards and industrial automation expertise.
- Middle East & Africa: Rapidly emerging market driven by infrastructure modernization and oil & gas automation.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Sensor Fusion Market.- NXP Semiconductors N.V.
- Robert Bosch GmbH
- STMicroelectronics N.V.
- Infineon Technologies AG
- Analog Devices, Inc.
- Renesas Electronics Corporation
- Qualcomm Technologies, Inc.
- Intel Corporation (Mobileye)
- TDK Corporation (InvenSense)
- Texas Instruments Incorporated
- Honeywell International Inc.
- Kionix, Inc.
- TE Connectivity Ltd.
- Murata Manufacturing Co., Ltd.
- Broadcom Inc.
- Microchip Technology Inc.
- Hillcrest Labs (CEVA, Inc.)
- Basler AG
- Baumer Group
- Piera Systems Inc.
Frequently Asked Questions
What is the current market size and projected growth of the Sensor Fusion Market?
The Sensor Fusion Market is estimated to be valued at USD 11.34 Billion in 2026 and is expected to reach USD 54.62 Billion by 2034, growing at a CAGR of 19.4%. This growth is driven by the increasing demand for autonomous systems and smart devices.
Which industry vertical is the primary driver of the Sensor Fusion Market?
The automotive industry is the primary driver, particularly through the implementation of Advanced Driver Assistance Systems (ADAS) and the development of self-driving vehicles, which require high-precision data fusion from multiple sensors.
Who are the leading players in the global Sensor Fusion landscape?
Key companies include NXP Semiconductors, Robert Bosch GmbH, STMicroelectronics, Infineon Technologies, and Analog Devices. These firms focus on integrating AI with sensor hardware to provide comprehensive perception solutions.
What are the main technological trends influencing this market?
Major trends include the shift toward Edge AI processing, the adoption of 4D imaging radar, and the use of sensor fusion in AR/VR and wearable healthcare technology for more accurate environmental and biological monitoring.
What challenges could hinder the expansion of the Sensor Fusion Market?
Significant challenges include the high cost of advanced sensors like LiDAR, the complexity of real-time data synchronization, and potential supply chain vulnerabilities for specialized semiconductor components.
Author
S
Shamin Verma is a Senior Analyst Semiconductor and Electronics Research with over 7+ years of experience in the Semiconductor and Electronics Industry. She specializes in semiconductor market intelligence, electronics supply chain analysis, wafer fabrication trends, competitive benchmarking, demand forecasting, component pricing analysis, emerging technology assessment, integrated circuit market evaluation, and industry ecosystem research. Her expertise in translating complex market data into strategic insights enables organizations to make informed business decisions, identify high-growth opportunities, optimize operational planning, anticipate evolving technology trends, and strengthen their competitive positioning in the global semiconductor and electronics market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
