Residential Commercial Roofing Materials Market
Residential Commercial Roofing Materials Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711251 | Published On : October 22, 2026 |
Format : 


 | Author : Jonathan Sikka
Residential Commercial Roofing Materials Market Size
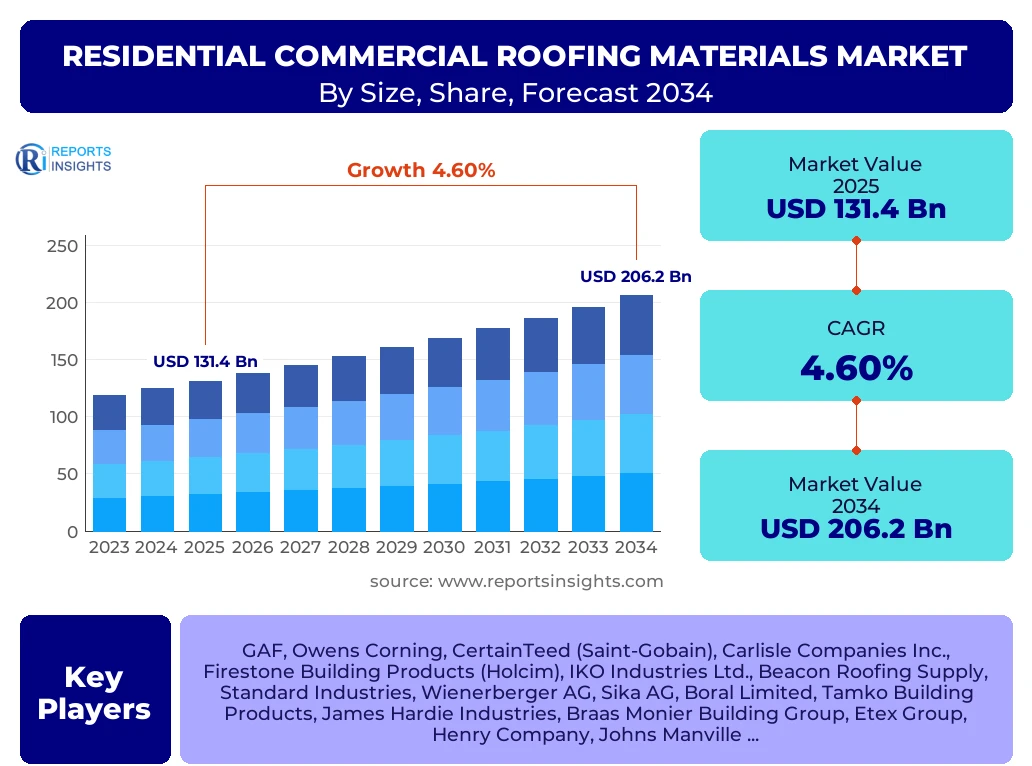
According to Reports Insights Consulting Pvt Ltd, The Residential Commercial Roofing Materials Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 4.6% between 2025 and 2034. The market is estimated at USD 137.5 Billion in 2026 and is projected to reach USD 206.2 Billion by the end of the forecast period in 2034.
Key Residential Commercial Roofing Materials Market Trends & Insights
The global roofing materials market is currently undergoing a significant paradigm shift driven by the dual imperatives of environmental sustainability and technological integration. Historically, the residential and commercial sectors operated in silos, but recent years have seen a convergence in material performance requirements. Residential consumers are increasingly seeking the durability and longevity associated with commercial-grade materials, such as metal roofing and synthetic membranes, while commercial developers are adopting aesthetic-forward solutions previously reserved for high-end residential projects. This cross-pollination is accelerating product innovation across the board. Regional insights indicate that while North America remains the value leader due to the prevalence of high-cost replacement projects, the Asia-Pacific region is the fastest-growing volume market, fueled by massive urbanization and infrastructure development in China, India, and Southeast Asia. Competitive benchmarking reveals that industry leaders are pivoting toward circular economy models, focusing on recyclable materials and zero-waste manufacturing processes to align with tightening global carbon regulations.
- Largest Region: North America currently holds the largest market share by value, driven by a robust renovation and replacement sector and the high adoption rate of premium roofing materials like asphalt shingles and metal systems.
- Fastest-Growing Region: Asia-Pacific is projected to exhibit the highest CAGR, primarily due to rapid industrialization, expanding commercial construction, and rising middle-class housing demands.
- Largest Segment by Material: Asphalt shingles continue to dominate the residential segment in terms of volume, whereas single-ply membranes (TPO/EPDM) lead the commercial sector.
- Emerging Trend: The integration of Building-Integrated Photovoltaics (BIPV) is transforming roofs from passive protective shells into active energy-generating assets.
- Technological Shift: The use of drone-based inspection and AI-driven damage assessment is streamlining the maintenance and insurance processes for large-scale commercial roofing.
Key Takeaways Residential Commercial Roofing Materials Market Size & Forecast
The long-term outlook for the Residential Commercial Roofing Materials market is characterized by resilient growth despite short-term economic fluctuations. The market's stability is anchored by the essential nature of roofing as a primary structural requirement for both new builds and the massive global backlog of aging infrastructure requiring replacement. Analysts highlight that the shift toward green building certifications (such as LEED and BREEAM) is no longer a niche preference but a core market driver, influencing the selection of reflective cool roofs and high-thermal-performance insulation materials. Furthermore, the forecast period suggests a significant increase in the adoption of synthetic and composite materials that offer superior resistance to extreme weather events, which are becoming more frequent globally. Market stakeholders are increasingly focusing on vertical integration and strategic partnerships to mitigate supply chain risks and ensure the availability of raw materials like bitumen, steel, and polymers.
- Leading Country: The United States remains the single most influential market for residential roofing innovation, particularly in the asphalt and metal categories.
- Dominant Sector: The replacement and reroofing segment accounts for over 60% of total market activity in mature economies, providing a stable revenue base regardless of new construction cycles.
- High-Growth Material: Metal roofing is gaining significant ground in the residential sector due to its 50-plus-year lifespan and high recyclability.
- Forecast Certainty: The commercial sector's growth is heavily tied to the resurgence of logistics and warehousing facilities necessitated by the global e-commerce boom.
- Strategic Focus: Manufacturers are investing heavily in low-VOC (volatile organic compound) adhesives and sustainable sourcing to meet environmental compliance standards.
Residential Commercial Roofing Materials Market Drivers Analysis
The fundamental growth of the roofing materials sector is propelled by several macro-economic and industry-specific factors. Population growth and urban migration are necessitating the construction of high-density residential complexes and expansive commercial hubs. Additionally, the global trend toward energy efficiency is a powerful catalyst; modern roofing systems are designed to minimize heat gain and reduce HVAC energy consumption, making them central to the "green building" movement. Government incentives for energy-efficient upgrades and the implementation of stricter building codes regarding wind and fire resistance are also compelling property owners to opt for high-quality, modern materials rather than traditional low-cost options. The convergence of these factors creates a sustained demand environment for advanced roofing solutions.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Urbanization and Infrastructure Development | +1.5% | Global (Strongest in APAC) | 2025 - 2034 |
| Rise in Energy-Efficient "Cool Roof" Demand | +1.2% | North America and Europe | 2026 - 2034 |
| Post-Pandemic Logistics/Warehouse Expansion | +0.8% | Global (Strongest in US/China) | 2025 - 2030 |
| Stricter Building Codes and Safety Regulations | +1.1% | Developed Economies | 2025 - 2034 |
Residential Commercial Roofing Materials Market Restraints Analysis
Despite strong demand, the market faces significant headwinds that could temper growth. The volatility of raw material prices, particularly for petroleum-based products like asphalt and synthetic polymers, creates pricing uncertainty for manufacturers and contractors. Labor shortages remain a critical bottleneck, as the roofing industry requires skilled installers who are increasingly difficult to recruit and retain. Furthermore, rising interest rates in several major economies have led to a slowdown in some new residential construction projects, forcing the market to rely more heavily on the replacement sector. Environmental regulations, while driving innovation, also impose high compliance costs on manufacturers, particularly in the production of traditional materials.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in Raw Material Prices (Bitumen/Steel) | -0.9% | Global | 2025 - 2028 |
| Shortage of Skilled Labor and Installers | -0.7% | North America and Europe | 2025 - 2034 |
| High Interest Rates Affecting New Construction | -0.5% | United States and EU | 2025 - 2027 |
Residential Commercial Roofing Materials Market Opportunities Analysis
The evolving landscape presents lucrative opportunities for players who can innovate beyond standard protection. The integration of solar technology into roofing materials—building-integrated photovoltaics (BIPV)—represents a massive frontier, allowing roofs to generate revenue for building owners. There is also a growing market for "living roofs" or green roofs in urban areas to combat the heat island effect and manage stormwater runoff. Additionally, the digitalization of the roofing lifecycle, from VR-assisted design to blockchain-enabled supply chain tracking, offers opportunities for efficiency gains and enhanced customer service. Emerging markets in Latin America and Africa also offer untapped potential as their construction sectors modernize and adopt standardized roofing practices.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Solar Integration (BIPV) and Smart Roofs | +1.4% | California (US), Germany, China | 2026 - 2034 |
| Expansion of Green/Vegetative Roof Systems | +0.6% | Urban Metropolitan Areas | 2027 - 2034 |
| Growth in Eco-friendly and Recycled Materials | +0.9% | Europe and North America | 2025 - 2034 |
Residential Commercial Roofing Materials Market Challenges Impact Analysis
The industry must navigate complex challenges that threaten operational margins and project timelines. The primary challenge is the intensifying frequency of extreme weather events, which requires materials to undergo more rigorous testing and certification, often increasing production costs. Furthermore, the global shift toward sustainability necessitates a complete overhaul of waste management practices within the industry, as roofing tear-offs contribute significantly to landfill volume. Managing the transition to a circular economy while maintaining cost-competitiveness against low-cost, less-sustainable alternatives is a major strategic hurdle for established manufacturers.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Environmental Waste Management (Tear-off Disposal) | -0.4% | Global | 2025 - 2034 |
| Adherence to Evolving Environmental Regulations | -0.3% | European Union and North America | 2025 - 2030 |
| Extreme Weather Resilience Requirements | -0.4% | Coastal and Cyclone-Prone Regions | 2025 - 2034 |
Residential Commercial Roofing Materials Market - Updated Report Scope
This comprehensive market report provides an in-depth analysis of the global residential and commercial roofing materials industry, spanning from historical trends to a ten-year forward-looking forecast. The scope encompasses a detailed evaluation of material types, application sectors, and geographic performance. It includes rigorous competitive benchmarking of the top 20 industry players, analyzing their market share, product portfolios, and strategic initiatives. The report also investigates the impact of technological advancements such as smart sensors and sustainable manufacturing on the overall market trajectory, providing stakeholders with actionable insights to navigate the evolving construction landscape.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 131.4 Billion |
| Market Forecast in 2034 | USD 206.2 Billion |
| Growth Rate | 4.6% CAGR |
| Number of Pages | 278 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | GAF, Owens Corning, CertainTeed (Saint-Gobain), Carlisle Companies Inc., Firestone Building Products (Holcim), IKO Industries Ltd., Beacon Roofing Supply, Standard Industries, Wienerberger AG, Sika AG, Boral Limited, Tamko Building Products, James Hardie Industries, Braas Monier Building Group, Etex Group, Henry Company, Johns Manville, Kingspan Group |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented based on material composition, end-use application, and project type to provide a granular view of growth pockets. The material segment is currently led by asphalt shingles in residential applications due to their cost-effectiveness and ease of installation. However, in the commercial sector, single-ply membranes like TPO and EPDM are the standard due to their durability and reflective properties. The application segment is divided into residential and commercial, with residential currently holding a slight lead in total market value, though commercial projects often involve higher-value individual contracts. Project-wise, reroofing dominates in mature markets, while new construction is the primary driver in developing regions.
- By Material Type:
- Asphalt Shingles (Organic, Fiberglass)
- Metal Roofing (Steel, Aluminum, Copper, Zinc)
- Single-ply Membranes (TPO, EPDM, PVC)
- Modified Bitumen
- Elastomeric Coatings
- Clay and Concrete Tiles
- Slate and Synthetic Slate
- Wood Shingles and Shakes
- By Application:
- Residential: Single-family housing, Multi-family apartments, Townhouses.
- Commercial: Corporate offices, Retail centers, Warehouses and Industrial plants, Institutional buildings (Schools, Hospitals).
- By Project Type:
- New Construction: Driven by housing starts and commercial expansion.
- Replacement/Retrofit: Driven by maintenance cycles, weather damage, and energy upgrades.
Regional Highlights
Regional dynamics are shaped by climatic conditions, local building regulations, and economic maturity. North America, particularly the United States, is a mature market characterized by a high demand for premium replacement materials and strict energy codes. Europe follows a similar pattern but with an even stronger emphasis on environmental sustainability and historical preservation, favoring high-end tiles and slate in certain regions. The Asia-Pacific region is the engine of volume growth, where rapid urbanization and government-led infrastructure projects in China and India are creating massive demand for commercial roofing and affordable residential solutions. Latin America and the MEA region are seeing emerging growth as construction standards modernize and investment in industrial parks increases.
- North America: Largest value market; leading adoption of cool roofs and high-impact resistant shingles. The US is the primary contributor.
- Asia-Pacific: Fastest-growing region; CAGR exceeding 5.5% in key sub-regions like Southeast Asia. Dominance of industrial and commercial construction.
- Europe: Hub for innovation in sustainable and green roofing; strict adherence to carbon reduction targets in construction.
- Middle East: High demand for heat-reflective and durable materials suited for extreme desert climates; significant investment in luxury commercial projects.
- Latin America: Growing demand for metal roofing and asphalt products in urbanizing centers like Brazil and Mexico.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Residential Commercial Roofing Materials Market.- GAF
- Owens Corning
- CertainTeed (Saint-Gobain)
- Carlisle Companies Inc.
- Firestone Building Products (Holcim)
- IKO Industries Ltd.
- Beacon Roofing Supply
- Standard Industries
- Wienerberger AG
- Sika AG
- Boral Limited
- Tamko Building Products
- James Hardie Industries
- Braas Monier Building Group
- Etex Group
- Henry Company
- Johns Manville (Berkshire Hathaway)
- Kingspan Group
- Atlas Roofing Corporation
- Duro-Last Inc.
Frequently Asked Questions
What is the current market size and forecast for roofing materials?
The market is estimated at USD 137.5 Billion in 2026 and is projected to grow to USD 206.2 Billion by 2034, representing a CAGR of 4.6% over the forecast period.
Which roofing material is seeing the fastest growth in the residential sector?
Metal roofing is experiencing the fastest growth in residential applications due to its long lifespan, fire resistance, and increasing availability of styles that mimic traditional shingles.
How is the "Cool Roof" trend impacting the commercial market?
Cool roofs, which reflect more sunlight and absorb less heat, are becoming standard in commercial construction to reduce energy costs and meet stricter environmental building codes.
What are the main challenges facing the roofing industry today?
Key challenges include the volatility of raw material prices (like asphalt and steel), a persistent shortage of skilled labor for installation, and the need for better waste management for old roofing materials.
Which region offers the most growth potential for new construction roofing?
The Asia-Pacific region, specifically China, India, and Southeast Asian nations, offers the most significant growth potential for new construction due to rapid urbanization and industrial expansion.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
