Waste Management Market
Waste Management Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711151 | Published On : October 13, 2026 |
Format : 


 | Author : Jonathan Sikka
Waste Management Market Size
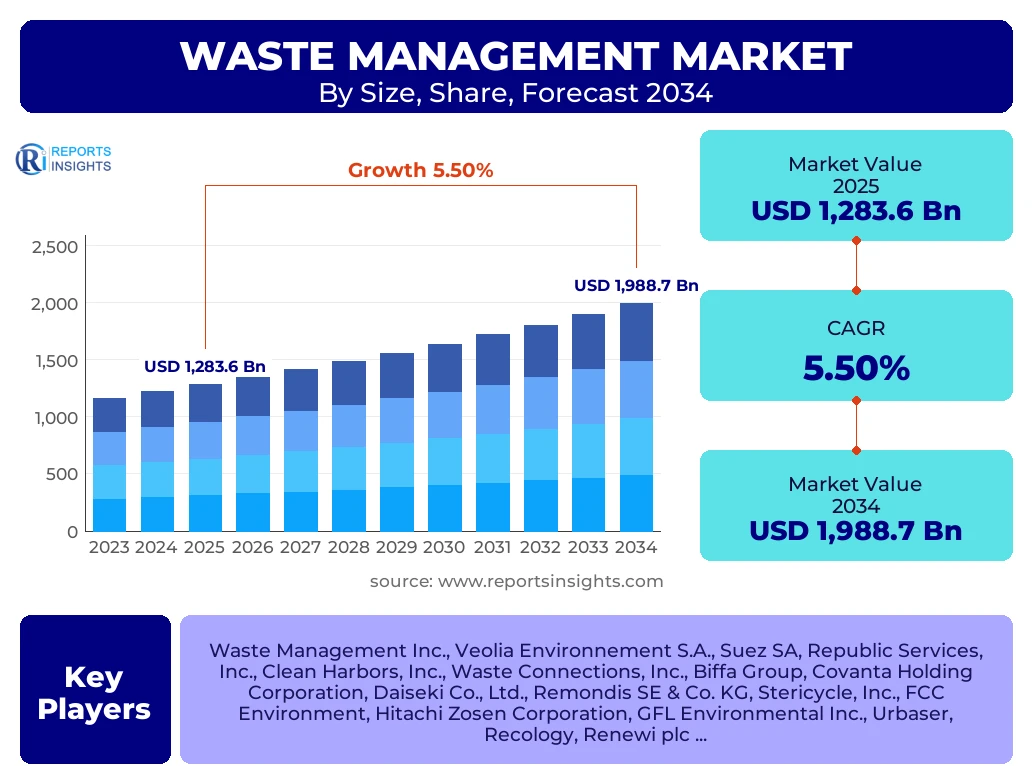
According to Reports Insights Consulting Pvt Ltd, The Waste Management Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.5% between 2025 and 2034. The market is estimated at USD 1,354.2 Billion in 2026 and is projected to reach USD 1,988.7 Billion by the end of the forecast period in 2034.
Key Waste Management Market Trends & Insights
The global waste management sector is undergoing a profound transformation driven by the integration of advanced digital technologies and a global pivot toward the circular economy. Stakeholders are increasingly prioritizing resource recovery over traditional landfill disposal. The rise of Smart Waste Management, utilizing Internet of Things (IoT) sensors for route optimization and fill-level monitoring, has significantly reduced operational overheads for municipal bodies. Furthermore, the industrial sector is adopting Zero Waste to Landfill (ZWTL) protocols to meet stringent Environmental, Social, and Governance (ESG) criteria. Competitive benchmarking reveals that leading players are shifting from being mere service providers to technology-integrated resource managers, focusing heavily on chemical recycling and waste-to-energy conversion to capitalize on high-value secondary raw materials.
- Largest Region: North America currently holds the largest market share due to highly developed waste collection infrastructure and stringent environmental regulations governing industrial and hazardous waste.
- Fastest Growing Region: Asia-Pacific is anticipated to exhibit the highest CAGR, fueled by rapid urbanization in China and India, coupled with aggressive government initiatives like the Swachh Bharat Mission and China waste import bans.
- Largest Segment by Share: The Industrial Waste segment dominates the market in terms of volume and revenue, necessitated by the massive output from manufacturing, construction, and chemical processing sectors.
- Emerging Trend: The proliferation of E-waste recycling is becoming a critical sub-segment as the lifecycle of consumer electronics shortens and precious metal recovery becomes economically viable.
Key Takeaways Waste Management Market Size & Forecast
The Waste Management market is characterized by a steady transition from linear disposal models to closed-loop systems. Analysis of market dynamics suggests that the integration of artificial intelligence in sorting facilities is the primary catalyst for increasing purity levels in recycled streams, thereby enhancing market profitability. As global populations concentrate in urban centers, the demand for efficient municipal solid waste management services is expected to scale exponentially. Investors are focusing on high-growth emerging economies where waste infrastructure is currently being modernized through public-private partnerships (PPP).
- The global market value is expected to surpass the 1.9 trillion dollar mark by 2034, reflecting the essential nature of waste services in a post-industrial world.
- Asia-Pacific is the strategic focal point for infrastructure investment, with China and India leading the regional demand for modernized disposal facilities.
- The recycling segment is projected to grow faster than the landfill segment as carbon taxes and landfill levies make disposal increasingly expensive.
- Regulatory frameworks such as the European Green Deal and the Circular Economy Action Plan are serving as blueprints for waste management policies globally.
- Energy recovery (Waste-to-Energy) is gaining significant traction as a viable solution for non-recyclable waste, providing a dual benefit of waste reduction and renewable energy generation.
Waste Management Market Drivers Analysis
The primary drivers for the waste management market include escalating global waste generation rates and the implementation of rigorous environmental protection laws. As industrialization expands in developing nations, the volume of hazardous and non-hazardous waste requires specialized handling and disposal services. Additionally, the growing awareness regarding the environmental impact of plastic pollution has led to a surge in demand for sophisticated plastic recycling technologies.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rapid Urbanization and Population Growth | +1.8% | India, China, Southeast Asia | 2025 - 2034 |
| Strict Environmental Regulations and ESG Mandates | +1.5% | European Union, North America | 2025 - 2030 |
| Technological Advancements in Sorting and Recycling | +1.2% | Germany, Japan, USA | 2026 - 2034 |
| Growth in Waste-to-Energy Initiatives | +1.0% | Nordic Countries, China | 2025 - 2034 |
Waste Management Market Restraints Analysis
Despite growth, the market faces significant restraints, most notably the high capital expenditure required for setting up modern recycling and incineration plants. In many developing regions, the lack of standardized collection and segregation at the source hinders the efficiency of downstream processing. Furthermore, illegal dumping and informal waste sectors in certain geographies create pricing pressures for formal, regulated service providers.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Operational and Maintenance Costs | -0.8% | Global | 2025 - 2034 |
| Lack of Awareness and Poor Segregation at Source | -0.7% | LAMEA, Parts of APAC | 2025 - 2029 |
| Stringent Permitting and Regulatory Hurdles | -0.5% | North America, Western Europe | 2025 - 2034 |
Waste Management Market Opportunities Analysis
The market is ripe with opportunities, particularly in the domain of specialized waste streams such as E-waste and medical waste. The recovery of rare earth metals from discarded electronics presents a multi-billion dollar opportunity. Moreover, the development of biodegradable alternatives and the expansion of the "circularity-as-a-service" business model allow waste management companies to integrate deeper into the supply chains of manufacturing firms.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| E-waste Mining and Precious Metal Recovery | +2.1% | Global (Lead by Japan and USA) | 2026 - 2034 |
| Expansion of Smart Waste Management Solutions | +1.4% | Smart Cities in Middle East and APAC | 2025 - 2034 |
| Bio-medical Waste Treatment Services | +0.9% | Global | 2025 - 2034 |
Waste Management Market Challenges Impact Analysis
Key challenges include the volatility of commodity prices for recycled materials, which can impact the profitability of recycling operations. Labor shortages in the collection and sorting sectors, particularly in developed economies, are forcing companies to accelerate automation. Additionally, the "Not In My Backyard" (NIMBY) sentiment continues to pose a challenge for the siting of new landfills or waste-to-energy plants near residential areas.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Fluctuating Secondary Raw Material Prices | -0.6% | Global | 2025 - 2034 |
| Public Opposition to New Facility Sites (NIMBY) | -0.4% | USA, UK, Germany | 2025 - 2034 |
| Worker Safety and Health Hazards | -0.3% | Emerging Economies | 2025 - 2030 |
Waste Management Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the global waste management landscape, covering municipal, industrial, hazardous, and electronic waste. It evaluates the entire value chain from collection and transportation to final disposal and resource recovery. The report utilizes a combination of primary and secondary research, including expert interviews and data modeling, to provide actionable insights for stakeholders seeking to navigate the evolving regulatory and technological environment.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1,283.6 Billion |
| Market Forecast in 2034 | USD 1,988.7 Billion |
| Growth Rate | 5.5% CAGR |
| Number of Pages | 276 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Waste Management Inc., Veolia Environnement S.A., Suez SA, Republic Services, Inc., Clean Harbors, Inc., Waste Connections, Inc., Biffa Group, Covanta Holding Corporation, Daiseki Co., Ltd., Remondis SE & Co. KG, Stericycle, Inc., FCC Environment, Hitachi Zosen Corporation, GFL Environmental Inc., Urbaser, Recology, Renewi plc, Rumpke Consolidated Companies, Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Waste Management Market is segmented into several critical categories to provide a granular view of the industry. The Waste Type segment remains the primary differentiator, with Industrial Waste accounting for the largest share due to the sheer volume of output from global manufacturing hubs. Municipal Solid Waste (MSW) follows closely, driven by rising consumption levels in urban environments. The Service segment is dominated by Collection, which involves the highest operational cost, while Disposal and Recycling are the fastest-growing sub-segments as regulatory pressure shifts focus toward recovery.
- By Waste Type:
- Municipal Solid Waste (Residential and Organic)
- Industrial Waste (Construction, Manufacturing, Chemical)
- Hazardous Waste (Flammable, Corrosive, Toxic, Reactive)
- Electronic Waste (Smartphones, Computers, Consumer Electronics)
- Bio-medical Waste (Hospital and Clinical Waste)
- By Service:
- Collection (Pick-up, Sorting, Transfer Stations)
- Disposal (Landfill, Incineration, Open Dumping)
- Recycling (Material Recovery Facilities, Chemical Recycling)
- Composting and Anaerobic Digestion
- By End-User:
- Residential (Urban and Rural Housing)
- Commercial (Retail, Offices, Hospitality)
- Industrial (Heavy Industry, Power Plants, Mining)
Regional Highlights
- North America: The largest market share holder, North America is characterized by advanced waste processing technologies and high per-capita waste generation. The United States leads the region with a mature recycling infrastructure and significant investments in hazardous waste management.
- Europe: The leader in regulatory innovation, Europe boasts the highest recycling rates globally. Countries like Germany and the Netherlands serve as benchmarks for the circular economy, with stringent landfill bans and high adoption of waste-to-energy.
- Asia-Pacific: The fastest-growing region, driven by massive urbanization in China, India, and Indonesia. China's "Waste-free Cities" initiative and the regional push for improved sanitation are creating immense opportunities for infrastructure providers.
- Middle East and Africa: A developing market where major investments are being made in Saudi Arabia (Vision 2030) and the UAE to divert waste from landfills and establish modern treatment facilities.
- Latin America: Focused on improving collection coverage and transitioning from open dumpsites to sanitary landfills, with Brazil and Mexico as the primary growth drivers.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Waste Management Market.- Waste Management Inc.
- Veolia Environnement S.A.
- Suez SA
- Republic Services, Inc.
- Clean Harbors, Inc.
- Waste Connections, Inc.
- Biffa Group
- Covanta Holding Corporation
- Daiseki Co., Ltd.
- Remondis SE & Co. KG
- Stericycle, Inc.
- FCC Environment
- Hitachi Zosen Corporation
- GFL Environmental Inc.
- Urbaser
- Recology
- Renewi plc
- Rumpke Consolidated Companies, Inc.
Frequently Asked Questions
What is the current size of the global Waste Management Market?
As of 2026, the global Waste Management Market is estimated at USD 1,354.2 Billion and is expected to grow steadily through 2034.
Which region is expected to grow the fastest in the Waste Management Market?
The Asia-Pacific region is projected to be the fastest-growing market due to rapid urbanization, rising industrialization, and favorable government policies regarding waste treatment.
What are the key drivers for the Waste Management Market growth?
Key drivers include the rising global population, stringent environmental regulations, increasing awareness of the circular economy, and the technological shift toward smart waste management.
Who are the leading players in the Waste Management Market?
Prominent leaders include Waste Management Inc., Veolia, Suez, and Republic Services, all of whom are investing heavily in recycling and digital waste tracking technologies.
What is the impact of digitalization on waste management?
Digitalization enables real-time monitoring of waste levels, route optimization for collection trucks, and automated AI-driven sorting at material recovery facilities, significantly improving efficiency and lowering costs.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
