Remote Patient Monitoring System Market
Remote Patient Monitoring System Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_710989 | Published On : September 25, 2026 |
Format : 


 | Author : Erika Grotto
Remote Patient Monitoring System Market Size
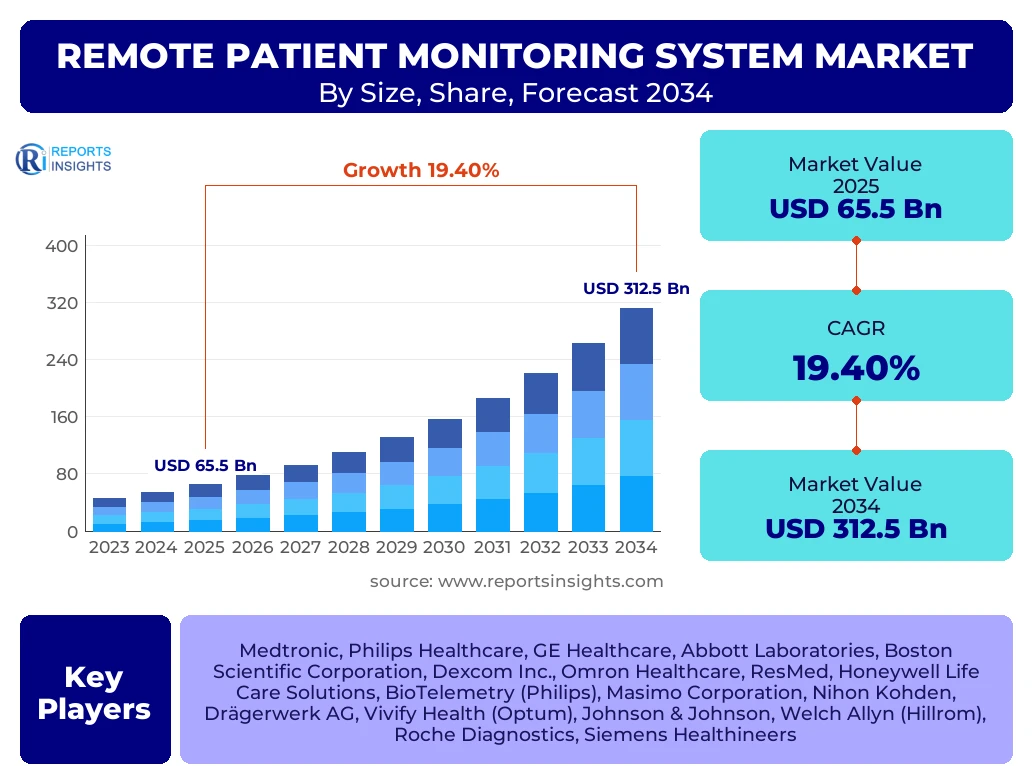
According to Reports Insights Consulting Pvt Ltd, The Remote Patient Monitoring System Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 19.4% between 2026 and 2034. The market is estimated at USD 78.2 Billion in 2026 and is projected to reach USD 312.5 Billion by the end of the forecast period in 2034.
Key Remote Patient Monitoring System Market Trends & Insights
The Remote Patient Monitoring (RPM) system market is undergoing a seismic shift driven by the convergence of digital health technologies and a global pivot toward value-based care models. Current market intelligence indicates that the integration of Artificial Intelligence (AI) and Machine Learning (ML) is the primary catalyst for market evolution, enabling predictive analytics that can alert healthcare providers to potential health crises before they manifest clinically. Furthermore, the decentralization of clinical trials and the rise of Hospital-at-Home initiatives are significantly expanding the total addressable market for RPM solutions across both developed and emerging economies.
- Largest Region: North America remains the dominant regional market, currently accounting for over 42% of the global market share due to advanced healthcare infrastructure and favorable reimbursement policies.
- Fastest Growing Region: Asia-Pacific is identified as the most rapid-growth sector, fueled by escalating healthcare expenditures in China and India and an increasing burden of chronic lifestyle diseases.
- Largest Segment by Component: The Services segment holds the largest market share, as healthcare providers increasingly outsource the monitoring and data analysis components to specialized third-party vendors.
- Key Technology Trend: The adoption of cellular-based RPM devices is outpacing Wi-Fi-reliant systems, particularly in rural and underserved areas, due to superior connectivity and ease of use for elderly populations.
- Market Consolidation: Strategic mergers and acquisitions are accelerating as traditional medical device manufacturers seek to acquire software capabilities to offer end-to-end monitoring ecosystems.
Key Takeaways Remote Patient Monitoring System Market Size & Forecast
The forecast for the Remote Patient Monitoring System market reflects a sustained double-digit growth trajectory, underpinned by the necessity to mitigate rising healthcare costs associated with chronic disease management. Research suggests that as healthcare systems worldwide grapple with nursing shortages and aging populations, RPM serves as a critical force multiplier, allowing a single clinician to manage a larger patient panel with greater precision. The market is transitioning from simple vital sign monitoring to complex, multi-parameter health management systems that integrate with electronic health records (EHRs) seamlessly.
- Leading Country: The United States leads globally, driven by Centers for Medicare & Medicaid Services (CMS) reimbursement codes that incentivize RPM adoption.
- Strategic Imperative: Interoperability is the primary focus for market players; systems that cannot integrate with existing hospital workflows are rapidly losing competitive relevance.
- Growth Driver: The increasing prevalence of cardiovascular diseases and diabetes is the fundamental driver, with glucose monitors and heart rate monitors leading the device category.
- Forecast Stability: The market displays high resilience; even amidst economic fluctuations, healthcare systems prioritize RPM to reduce high-cost hospital readmissions.
Remote Patient Monitoring System Market Drivers Analysis
The primary driver of the Remote Patient Monitoring market is the global escalation of the geriatric population, which is intrinsically linked to a higher incidence of chronic conditions requiring continuous management. This demographic shift necessitates a move away from traditional hospital-centric care to home-based monitoring to prevent system overload. Additionally, the increasing cost of inpatient care is compelling insurers and governments to support RPM as a cost-effective alternative for post-operative recovery and long-term illness management.
Technological advancements in sensor precision and battery life have also removed significant barriers to patient compliance. The miniaturization of components allows for wearable devices that are non-intrusive, encouraging 24/7 monitoring. Furthermore, the rapid expansion of 5G networks provides the high-bandwidth, low-latency connectivity required for real-time transmission of high-fidelity medical data, which is essential for acute care monitoring in a domestic setting.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rising Prevalence of Chronic Diseases | +6.2% | Global | 2025–2034 |
| Favorable Reimbursement Policies (CMS) | +5.5% | United States | 2025–2030 |
| Shortage of Healthcare Professionals | +4.1% | Europe & North America | 2025–2034 |
| Advancements in AI and Predictive Analytics | +3.6% | APAC & North America | 2026–2034 |
Remote Patient Monitoring System Market Restraints Analysis
Despite robust growth, the market faces significant restraints related to data security and patient privacy. The transmission of sensitive medical data over public and private networks makes RPM systems a prime target for cyberattacks, leading to concerns among both providers and patients. Compliance with stringent regulations such as HIPAA in the United States and GDPR in Europe adds a layer of operational complexity and cost for manufacturers and service providers.
Another major restraint is the lack of standardized reimbursement frameworks in developing nations. While the U.S. has made significant strides, many countries in the APAC and Latin American regions still operate on fee-for-service models that do not adequately compensate clinicians for time spent reviewing remote data. This creates a financial disincentive for large-scale RPM implementation in those territories.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Data Privacy and Cybersecurity Concerns | -2.8% | Global (High in EU) | 2025–2034 |
| High Initial Implementation Costs | -2.1% | Emerging Economies | 2025–2028 |
| Inconsistent Reimbursement Landscapes | -1.9% | Middle East & Africa | 2025–2030 |
Remote Patient Monitoring System Market Opportunities Analysis
The expansion into mental health monitoring represents a significant untapped opportunity within the RPM sector. By utilizing physiological markers such as heart rate variability and sleep patterns, RPM systems can assist in the remote management of depression, anxiety, and PTSD, providing clinicians with objective data to supplement patient self-reporting. This holistic approach to health is increasingly favored by integrated delivery networks (IDNs).
Furthermore, the integration of RPM with pharmacy benefit management (PBM) and medication adherence tools offers a high-growth niche. Systems that can monitor whether a patient has taken their medication and simultaneously record the physiological response provide a comprehensive closed-loop data set. This is particularly valuable for pharmaceutical companies conducting post-market surveillance and Phase IV clinical trials, opening new revenue streams beyond traditional healthcare providers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| RPM Integration in Clinical Trials | +4.8% | Global | 2026–2034 |
| Behavioral Health & Mental Monitoring | +3.5% | United Kingdom & U.S. | 2025–2034 |
| Expansion into Veterinary RPM | +1.2% | North America | 2027–2034 |
Remote Patient Monitoring System Market Challenges Impact Analysis
One of the most persistent challenges is the "digital divide," where elderly or socioeconomically disadvantaged patients lack the technical literacy or reliable internet access necessary to engage with RPM platforms. This creates a risk of exacerbating healthcare inequities rather than resolving them. Manufacturers must focus on "zero-touch" setup and highly intuitive user interfaces to overcome this barrier.
Interoperability remains a significant hurdle as the market is currently fragmented with numerous proprietary platforms that do not communicate effectively with one another. Healthcare systems often find themselves locked into a specific vendor's ecosystem, making it difficult to aggregate data from multiple types of devices. The transition toward HL7 FHIR standards is underway but faces resistance from incumbent players protecting their market share.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Lack of Universal Data Standards | -2.5% | Global | 2025–2029 |
| Low Tech Literacy in Geriatric Patients | -2.2% | Japan & Southern Europe | 2025–2034 |
| Supply Chain Vulnerabilities for Semiconductors | -1.4% | Global | 2025–2027 |
Remote Patient Monitoring System Market - Updated Report Scope
The scope of this market research report encompasses a comprehensive analysis of the global Remote Patient Monitoring (RPM) ecosystem, including hardware devices, specialized software platforms, and professional services. The report evaluates the market dynamics across various clinical applications including, but not limited to, cardiovascular health, diabetes management, respiratory care, and oncology. This updated scope specifically addresses the transition from legacy telehealth to modern asynchronous monitoring and AI-enabled diagnostic support systems.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 65.5 Billion |
| Market Forecast in 2034 | USD 312.5 Billion |
| Growth Rate | 19.4% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Medtronic, Philips Healthcare, GE Healthcare, Abbott Laboratories, Boston Scientific Corporation, Dexcom Inc., Omron Healthcare, ResMed, Honeywell Life Care Solutions, BioTelemetry (Philips), Masimo Corporation, Nihon Kohden, Drägerwerk AG, Vivify Health (Optum), Johnson & Johnson, Welch Allyn (Hillrom), Roche Diagnostics, Siemens Healthineers |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Remote Patient Monitoring System market is segmented based on component, clinical application, and end-user, providing a granular view of the value chain. The Vital Sign Monitors segment currently dominates the hardware category, as these devices are the fundamental building blocks of any RPM program. However, the Specialized Monitors segment—particularly Continuous Glucose Monitors (CGM)—is seeing the highest growth rate due to the global diabetes epidemic. Software and Services are increasingly bundled, with cloud-based SaaS models becoming the industry standard due to their scalability and ease of updates.
- By Component:
- Vital Sign Monitors (Blood Pressure, Heart Rate, Pulse Oximeters, Thermometers)
- Specialized Monitors (Glucose Monitors, ECG/EKG, EEG, Anesthesia Monitors, Fetal Monitors)
- Software & Platforms (Cloud-based, On-premise)
- Professional Services (Data Analysis, Installation, Consulting)
- By Application:
- Cardiovascular Diseases (Congestive Heart Failure, Hypertension)
- Diabetes Management
- Respiratory Diseases (COPD, Asthma)
- Neurological Disorders
- Oncology (Post-chemotherapy monitoring)
- By End-User:
- Hospitals and Clinics
- Homecare Settings
- Ambulatory Care Centers
- Long-term Care Facilities
Regional Highlights
- North America: Holds the largest market share (approx. 42%). Growth is underpinned by a robust reimbursement framework, the presence of major industry players, and a high rate of adoption among private healthcare providers seeking to reduce readmission penalties.
- Europe: The second-largest market, with Germany, the UK, and France leading. Growth is driven by government-sponsored digital health initiatives and a strong focus on data privacy (GDPR) which has shaped the development of secure RPM platforms.
- Asia-Pacific: The fastest-growing region with a projected CAGR exceeding 21%. Rapid urbanization, a burgeoning middle class in China and India, and government initiatives to provide healthcare to remote rural populations are the primary drivers.
- Latin America: Showing significant potential in Brazil and Mexico. The focus here is on managing chronic diseases in urban centers and utilizing RPM to bridge the gap in specialist availability.
- Middle East & Africa: Steady growth observed in GCC countries like Saudi Arabia and the UAE, where investment in "Smart Hospitals" and digital infrastructure is a national strategic priority.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Remote Patient Monitoring System Market.- Medtronic plc
- Koninklijke Philips N.V.
- GE Healthcare
- Abbott Laboratories
- Boston Scientific Corporation
- Dexcom, Inc.
- Omron Healthcare, Inc.
- ResMed Inc.
- Honeywell Life Care Solutions
- BioTelemetry, Inc. (A Philips Company)
- Masimo Corporation
- Nihon Kohden Corporation
- Drägerwerk AG & Co. KGaA
- Vivify Health (Optum)
- Masimo
- Johnson & Johnson
- Siemens Healthineers
- Welch Allyn (Hill-Rom Services Inc.)
- Roche Diagnostics
- A&D Medical
Frequently Asked Questions
What is driving the growth of the Remote Patient Monitoring System market?
The market is primarily driven by the rising prevalence of chronic diseases like diabetes and heart disease, an aging global population, and the need for healthcare systems to reduce costs by shifting care from hospitals to home settings. Technological advancements in AI and 5G also play a critical role.
Which region is expected to see the fastest growth through 2034?
Asia-Pacific is projected to be the fastest-growing region. This is due to increasing healthcare investments, large patient populations in China and India, and a rapid digital transformation across the region's medical infrastructure.
How do reimbursement policies affect the RPM market?
Reimbursement policies are crucial; in regions like the U.S., CMS codes that pay clinicians for time spent monitoring patient data have significantly accelerated adoption. Lack of similar codes in other regions remains a barrier to market entry.
What are the main security concerns in remote patient monitoring?
The primary concerns involve data breaches, unauthorized access to sensitive patient health information (PHI), and the potential for cyberattacks on connected medical devices. Manufacturers must adhere to strict regulations like HIPAA and GDPR to mitigate these risks.
What is the difference between RPM hardware and software segments?
Hardware refers to the physical devices (e.g., blood pressure cuffs, glucose monitors), while software refers to the cloud-based platforms and applications that collect, store, and analyze the data for healthcare providers to review.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted