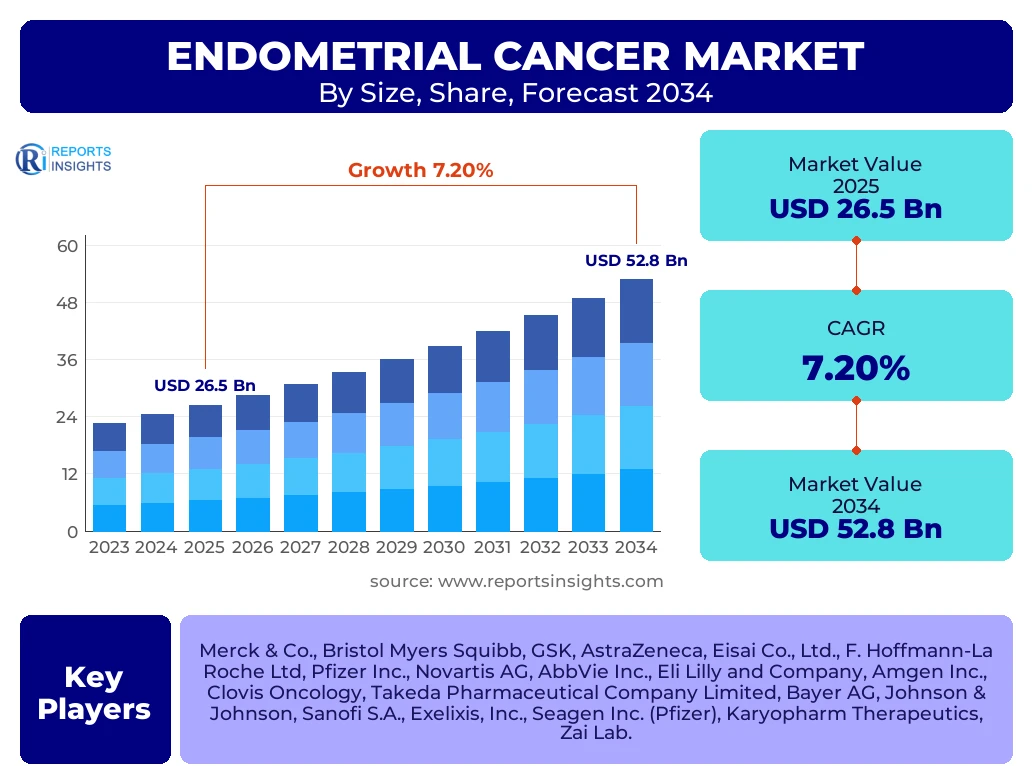
Endometrial Cancer Market
Endometrial Cancer Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711313 | Published On : October 26, 2026 |
Format : 


 | Author : Erika Grotto
Endometrial Cancer Market Size
According to Reports Insights Consulting Pvt Ltd, The Endometrial Cancer Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.2% between 2025 and 2034. The market is estimated at USD 28.4 Billion in 2026 and is projected to reach USD 52.8 Billion by the end of the forecast period in 2034.
Key Endometrial Cancer Market Trends & Insights
The global endometrial cancer market is undergoing a significant transformation driven by the paradigm shift from traditional cytotoxic chemotherapy to personalized medicine and targeted immunotherapy. Increasing investments in genomic sequencing and the identification of specific biomarkers such as Microsatellite Instability-High (MSI-H) and Mismatch Repair Deficient (dMMR) have enabled clinicians to tailor treatments more effectively. This shift is particularly evident in the rapid adoption of PD-1 and PD-L1 inhibitors, which have shown remarkable efficacy in advanced and recurrent cases. Furthermore, the integration of artificial intelligence in diagnostic imaging and pathology is enhancing early detection rates, which remains a critical factor in improving patient survival outcomes.
Market dynamics are also being influenced by the rising prevalence of lifestyle-related risk factors, most notably obesity and physical inactivity, which are strongly correlated with the development of Type I endometrial carcinomas. Emerging economies in the Asia-Pacific region are witnessing an uptick in disease incidence due to changing dietary habits and an aging female population. Competitive benchmarking indicates that leading pharmaceutical players are increasingly focusing on combination therapies, such as pairing Tyrosine Kinase Inhibitors (TKIs) with immunotherapeutic agents, to overcome resistance mechanisms and expand their market footprint in second-line and third-line treatment settings.
- North America remains the largest regional market due to high healthcare expenditure and early adoption of advanced therapies.
- Asia-Pacific is identified as the fastest-growing region, fueled by improving healthcare infrastructure and rising awareness.
- The Immunotherapy segment is currently the largest in terms of market share and value growth within the treatment category.
- Biomarker-driven clinical trials are the primary focus for R&D departments across the top ten pharmaceutical companies.
- The Hospitals segment continues to dominate the end-user landscape, accounting for the highest volume of high-cost therapeutic administrations.
Key Takeaways Endometrial Cancer Market Size & Forecast
The forecast period from 2025 to 2034 suggests a robust expansion of the endometrial cancer market, underpinned by a high volume of late-stage clinical trial completions and subsequent regulatory approvals. The transition towards outpatient care and oral targeted therapies is expected to redefine the cost structure of treatment regimens. Moreover, the increasing emphasis on molecular classification, as recommended by the International Federation of Gynecology and Obstetrics (FIGO) and the European Society of Gynaecological Oncology (ESGO), is standardizing global treatment protocols, thereby streamlining market entry for new diagnostic and therapeutic products.
- The United States is the leading country in terms of market value, driven by a robust pipeline of novel biologics.
- Targeted therapy is expected to witness the highest CAGR as molecular profiling becomes standard of care.
- Strategic collaborations between diagnostic companies and biopharma firms are accelerating the companion diagnostics market.
- Patient advocacy and increased funding for women’s health initiatives are significantly boosting screening rates globally.
- Expansion of healthcare insurance coverage in developing nations is unlocking previously untapped patient populations for premium treatments.
Endometrial Cancer Market Drivers Analysis
The primary catalysts for the endometrial cancer market include the rising global incidence of uterine cancers and the rapid regulatory approval of breakthrough therapies. Advancements in biotechnology have allowed for a more nuanced understanding of the tumor microenvironment, leading to the development of highly specific antibodies. Furthermore, the increasing prevalence of metabolic syndromes, which are established precursors to endometrial malignancies, ensures a steady rise in the patient pool, necessitating more advanced management solutions.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in Immunotherapy and PD-1/PD-L1 Blockades | +2.1% | Global (High in US and EU) | 2025 - 2034 |
| Rising Prevalence of Obesity and Sedentary Lifestyles | +1.8% | North America and Europe | 2025 - 2034 |
| Expansion of Molecular Profiling and Companion Diagnostics | +1.5% | Germany, Japan, USA | 2026 - 2030 |
| Governmental Initiatives for Early Cancer Detection | +1.2% | China, India, Brazil | 2027 - 2034 |
Endometrial Cancer Market Restraints Analysis
Despite the growth, the market faces significant hurdles including the high cost of newly approved biologics and the restrictive reimbursement policies in various middle-income countries. Additionally, the severe side effects associated with prolonged chemotherapy and some targeted treatments can lead to high patient attrition rates. Regulatory complexities in multi-regional clinical trials also pose a delay in the commercialization of cross-border therapeutic innovations.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Advanced Immunotherapy Drugs | -1.4% | Global (Specific to MEA and LATAM) | 2025 - 2034 |
| Severe Adverse Effects and Treatment Toxicity | -0.8% | Global | 2025 - 2030 |
| Stringent Regulatory Approval Frameworks | -0.6% | Europe and Japan | 2025 - 2034 |
Endometrial Cancer Market Opportunities Analysis
Opportunities abound in the development of combination therapies that target multiple pathways simultaneously, potentially improving overall survival rates in refractory patients. The rise of telemedicine and digital health platforms offers a new avenue for monitoring patient health and managing treatment-related toxicity remotely. Furthermore, the focus on rare subtypes of endometrial cancer, such as serous and clear cell carcinomas, presents a niche market for specialized orphan drug development.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Personalized Medicine and Next-Generation Sequencing (NGS) | +2.4% | USA, UK, South Korea | 2026 - 2034 |
| Growth in Medical Tourism for Specialized Oncology Care | +1.1% | India, Thailand, Singapore | 2026 - 2034 |
| Development of Oral Small Molecule Inhibitors | +1.3% | Global | 2027 - 2034 |
Endometrial Cancer Market Challenges Impact Analysis
Market participants must navigate the challenges of drug resistance and the high failure rate of oncology drugs in phase III clinical trials. Maintaining a balance between affordability and innovation remains a persistent challenge for manufacturers, especially with the emergence of biosimilars which threaten the market share of original patented biologics. Furthermore, the disparity in healthcare infrastructure between urban and rural areas in developing nations hinders the widespread adoption of advanced diagnostic tools.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Emergence of Drug Resistance Mechanisms | -1.2% | Global | 2025 - 2034 |
| Inter-Specialty Coordination in Multimodal Care | -0.5% | Global | 2025 - 2030 |
| Patent Expirations of Key Blockbuster Oncology Drugs | -1.0% | USA and Europe | 2028 - 2032 |
Endometrial Cancer Market - Updated Report Scope
This report provides a comprehensive examination of the endometrial cancer therapeutic and diagnostic landscape, covering multiple dimensions including drug class, therapy type, and geographic penetration. The scope encompasses detailed financial modeling and competitive intelligence for the period between 2025 and 2034, ensuring stakeholders have a granular understanding of market shifts and investment hotspots.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 26.5 Billion |
| Market Forecast in 2034 | USD 52.8 Billion |
| Growth Rate | 7.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Merck & Co., Bristol Myers Squibb, GSK, AstraZeneca, Eisai Co., Ltd., F. Hoffmann-La Roche Ltd, Pfizer Inc., Novartis AG, AbbVie Inc., Eli Lilly and Company, Amgen Inc., Clovis Oncology, Takeda Pharmaceutical Company Limited, Bayer AG, Johnson & Johnson, Sanofi S.A., Exelixis, Inc., Seagen Inc. (Pfizer), Karyopharm Therapeutics, Zai Lab. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The endometrial cancer market is segmented based on the mechanism of action of the therapeutics and the histological characteristics of the malignancy. The move toward biomarker-driven segmentation is the most prominent development, allowing for more precise targeting of treatments. For instance, tumors are now categorized by their MMR status, which directly dictates the eligibility for various immunotherapy regimens. This granular segmentation facilitates a more focused approach for pharmaceutical manufacturers during the clinical trial design phase and helps in optimizing market access strategies.
From an end-user perspective, hospitals remain the primary hub for treatment, particularly for surgical interventions and radiation therapy. However, the specialty clinics segment is expanding rapidly as oral targeted therapies become more prevalent, allowing for easier administration outside of a traditional hospital setting. The segmentation by cancer type shows that while Adenocarcinoma remains the most prevalent, there is significant high-value growth in the serous and clear cell carcinoma segments, which often require more aggressive and expensive therapeutic interventions due to their poor prognosis.
- By Therapy Type:
- Immunotherapy (PD-1, PD-L1 Inhibitors)
- Targeted Therapy (Tyrosine Kinase Inhibitors, Angiogenesis Inhibitors)
- Chemotherapy (Platinum-based, Taxanes)
- Hormonal Therapy (Progestins, Tamoxifen, Aromatase Inhibitors)
- Radiation Therapy and Surgery
- By Cancer Type:
- Endometrial Adenocarcinoma (Type I)
- Uterine Serous Carcinoma (Type II)
- Uterine Carcinosarcoma
- Clear Cell Adenocarcinoma
- Other Rare Variants
- By Distribution Channel:
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies and Specialty Distributors
Regional Highlights
North America currently holds the largest market share, a position sustained by high awareness regarding women’s health and the presence of major pharmaceutical corporations. The United States leads this region with extensive research funding and a healthcare system that rapidly integrates new oncological drugs. The prevalence of obesity and diabetes in this region also contributes to the high incidence rates of Type I endometrial cancer, further driving the demand for treatment solutions.
The Asia-Pacific region is projected to be the fastest-growing market over the forecast period. This growth is attributed to the expanding healthcare infrastructure in China and India, alongside a growing elderly population. Increased governmental focus on reducing cancer mortality through national screening programs and the local manufacturing of biosimilars are making treatments more accessible. Furthermore, Japan is a significant market within APAC due to its aging demographic and high adoption rate of innovative cancer therapies.
- North America is the dominant region, characterized by high treatment costs and advanced genomic testing adoption.
- Asia-Pacific is the fastest-growing region with a high CAGR due to increasing healthcare expenditure and large patient populations.
- Europe represents a mature market with a strong focus on cost-effectiveness and government-funded healthcare programs in countries like Germany and France.
- Latin America is witnessing moderate growth, driven by improvements in diagnostic capabilities and regional healthcare reforms.
- The Middle East and Africa region is showing emerging potential as specialized oncology centers are established in major urban hubs.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Endometrial Cancer Market.- Merck & Co., Inc.
- Bristol Myers Squibb Company
- GSK plc
- AstraZeneca PLC
- Eisai Co., Ltd.
- F. Hoffmann-La Roche Ltd
- Pfizer Inc.
- Novartis AG
- AbbVie Inc.
- Eli Lilly and Company
- Amgen Inc.
- Clovis Oncology, Inc.
- Takeda Pharmaceutical Company Limited
- Bayer AG
- Johnson & Johnson (Janssen Pharmaceuticals)
- Sanofi S.A.
- Exelixis, Inc.
- Seagen Inc.
- Karyopharm Therapeutics Inc.
- Zai Lab Limited
Frequently Asked Questions
What is the current market size and projected growth rate of the Endometrial Cancer Market?
The endometrial cancer market is valued at approximately USD 26.5 billion in 2025 and is expected to grow at a CAGR of 7.2% to reach USD 52.8 billion by 2034.
What are the primary drivers for growth in this market?
Growth is primarily driven by the increasing incidence of endometrial cancer due to rising obesity rates, the development of breakthrough immunotherapies like PD-1 inhibitors, and the integration of molecular profiling into standard diagnostic protocols.
Which therapy segment holds the largest market share?
Immunotherapy currently holds the largest and fastest-growing share of the market, particularly for patients with advanced or recurrent endometrial cancer who exhibit specific biomarkers like MSI-H or dMMR.
Which region is expected to show the fastest growth over the forecast period?
The Asia-Pacific region is anticipated to be the fastest-growing market due to rapid improvements in healthcare infrastructure, rising disposable income, and increasing awareness of specialized oncology treatments.
Who are the leading companies operating in the endometrial cancer space?
Leading players include Merck & Co., Bristol Myers Squibb, GSK, AstraZeneca, and Eisai, all of whom have significant therapeutic assets in late-stage clinical trials or already commercialized in the market.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
