Recycling Equipment Market
Recycling Equipment Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711157 | Published On : October 13, 2026 |
Format : 


 | Author : Jonathan Sikka
Recycling Equipment Market Size
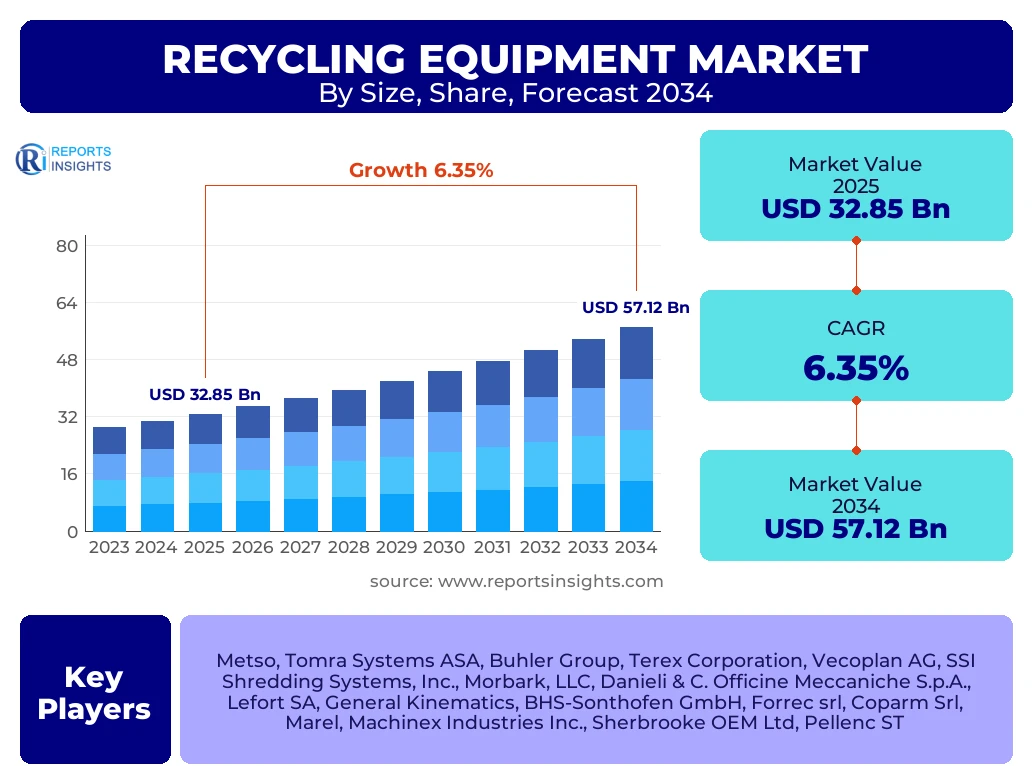
According to Reports Insights Consulting Pvt Ltd, The Recycling Equipment Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.35% between 2025 and 2034. The market is estimated at USD 34.93 Billion in 2026 and is projected to reach USD 57.12 Billion by the end of the forecast period in 2034.
Key Recycling Equipment Market Trends & Insights
The global recycling equipment market is undergoing a significant transformation driven by the transition toward a circular economy and the integration of advanced industrial automation. Stakeholders are increasingly focused on high-efficiency sorting and processing technologies that minimize human intervention and maximize the purity of recovered materials. The rise of sensor-based sorting, utilizing Near-Infrared (NIR) and Artificial Intelligence (AI), has revolutionized how plastic and metal scrap are categorized, allowing for higher recovery rates in facilities that were previously hampered by manual labor constraints. Furthermore, the push for Net-Zero emissions by 2050 is compelling manufacturers to develop energy-efficient equipment that reduces the carbon footprint of the recycling process itself.
Market intelligence indicates a surge in demand for specialized electronic waste (e-waste) and lithium-ion battery recycling machinery. As the automotive sector pivots toward electric vehicles, the need for localized recycling infrastructure capable of handling hazardous battery components has become a critical trend. Regional insights suggest that while Europe remains the regulatory vanguard, the Asia-Pacific region is experiencing the most rapid infrastructure build-out, fueled by massive waste generation in urban centers and government-led waste management initiatives. Companies are also adopting Modular Design principles, allowing recycling facilities to scale their operations by adding specific units for different material streams as market demand shifts.
- Largest Region: Europe currently holds the largest market share due to stringent waste management regulations and the Circular Economy Action Plan.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR, driven by industrialization in India, Southeast Asia, and China.
- Largest Segment by Material: The Metal Recycling segment dominates the market share in terms of value, attributed to the high resale price of ferrous and non-ferrous scrap.
- Leading Equipment Type: Shredders and Granulators represent the largest share of equipment sales, as they are essential primary processing units across all material types.
- Technological Shift: There is a definitive move from mechanical sorting toward AI-driven robotic sorting systems to improve output quality.
Key Takeaways Recycling Equipment Market Size & Forecast
The trajectory of the recycling equipment market is fundamentally linked to global sustainability mandates and the volatility of virgin raw material prices. When the cost of virgin plastic or metal rises, the economic viability of recycling equipment increases, prompting industrial players to invest in robust processing hardware. Analysis of the forecast period suggests that the market will see a steady 6.35% growth, with the latter half of the decade seeing a spike in adoption for specialized chemical recycling equipment. This shift is necessary to handle complex multi-layer plastics that traditional mechanical recycling equipment cannot process efficiently. Strategic investments are being directed toward high-capacity balers and compactors to optimize the logistics of waste transportation, which remains a significant cost factor in the recycling value chain.
- Market Valuation: The industry is poised to surpass the USD 57 billion mark by 2034, reflecting a robust long-term demand for waste-to-resource solutions.
- Key Country Growth: China remains the primary global hub for recycled material processing, while the United States is seeing a resurgence in domestic recycling infrastructure investment.
- Urbanization Impact: Rapid urbanization in emerging economies is generating unprecedented levels of municipal solid waste, necessitating large-scale sorting and baling installations.
- Regulatory Influence: Extended Producer Responsibility (EPR) laws are the most significant policy drivers, forcing manufacturers to take back products and invest in recycling technology.
- Sustainability Goals: Corporate ESG commitments are driving the demand for high-purity recycled resins, which can only be produced through advanced granulating and washing equipment.
Recycling Equipment Market Drivers Analysis
The primary driver for the recycling equipment market is the global legislative shift toward mandatory recycled content in consumer goods. Governments in the European Union and North America are implementing strict quotas that require packaging to contain a minimum percentage of post-consumer recycled (PCR) material. This has created an immediate need for advanced washing and pelletizing lines that can produce food-grade recycled plastic. Additionally, the depletion of primary natural resources is making the recovery of metals from urban mining more cost-effective than traditional mining, especially for rare earth elements found in electronics. This economic incentive is accelerating the procurement of sophisticated shredding and separation machinery.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Waste Management Regulations (EPR) | +2.1% | Europe and North America | Short to Long Term |
| Rapid Growth in E-waste Generation | +1.8% | Global (High in Asia-Pacific) | Mid to Long Term |
| Transition to Circular Economy Models | +1.5% | Developed Economies | Ongoing |
| Rising Prices of Virgin Raw Materials | +0.95% | Global | Short to Mid Term |
Recycling Equipment Market Restraints Analysis
Despite the positive growth outlook, the high initial capital expenditure (CAPEX) required for sophisticated recycling plants remains a significant barrier for small and medium enterprises (SMEs) in developing nations. High-tech sensor sorters and chemical recycling units involve substantial investment and long payback periods. Furthermore, the technical challenge of processing contaminated waste streams often leads to equipment wear and tear, increasing maintenance costs and reducing the overall efficiency of the operation. Inconsistent waste collection systems in many regions also lead to low capacity utilization of expensive machinery, deterring potential investors who fear insufficient feedstock supply.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Capital Investment | -1.2% | Developing Regions (Africa, SE Asia) | Ongoing |
| High Maintenance and Operational Costs | -0.8% | Global | Mid Term |
| Complexity in Sorting Multi-Material Waste | -0.5% | Global | Short to Mid Term |
Recycling Equipment Market Opportunities Analysis
The burgeoning Electric Vehicle (EV) market presents a massive opportunity for recycling equipment manufacturers. Specialized equipment designed for the safe discharge, disassembly, and shredding of large-scale lithium-ion battery packs is in high demand. Moreover, the integration of Industrial Internet of Things (IIoT) into recycling machinery offers opportunities for predictive maintenance and real-time monitoring of material throughput, which appeals to large-scale waste management firms looking for operational efficiency. Emerging markets in the Middle East and Africa are also beginning to formalize their waste sectors, providing a greenfield opportunity for the installation of primary sorting and baling equipment.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Lithium-ion Battery Recycling Infrastructure | +2.5% | USA, China, Germany | Long Term (2026-2034) |
| AI and Robotic Sorting Integration | +1.7% | Japan, South Korea, EU | Mid to Long Term |
| Growth in Chemical Recycling Equipment | +1.4% | Europe and USA | Short to Mid Term |
Recycling Equipment Market Challenges Impact Analysis
One of the most persistent challenges is the lack of standardized waste collection and sorting protocols globally, which results in feedstock of highly variable quality. Equipment must be engineered to be versatile enough to handle different levels of contamination, which often compromises processing speed. Additionally, fluctuations in the market value of recycled commodities can make revenue streams unpredictable for recycling facilities, leading to a cautious approach toward equipment upgrades. The environmental regulations governing the recycling process itself, such as wastewater management in plastic washing lines, also add a layer of regulatory complexity and cost to the installation of new equipment.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Inconsistent Feedstock Quality | -0.9% | Global | Ongoing |
| Volatility in Recycled Material Prices | -0.7% | Global | Short Term |
| Strict Environmental Norms for Processing Plants | -0.4% | OECD Countries | Mid Term |
Recycling Equipment Market - Updated Report Scope
This report provides a comprehensive analysis of the global recycling equipment market, covering key machinery types such as balers, shredders, granulators, and sorters across diverse material streams. The scope includes an in-depth evaluation of technological advancements, ranging from basic mechanical separation to sophisticated AI-driven systems. Regional dynamics are analyzed with a focus on both established waste management frameworks in developed nations and rapidly evolving infrastructures in emerging economies. The study also examines the impact of global trade policies on scrap metal and plastic movements, which directly influence the demand for local processing equipment.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 32.85 Billion |
| Market Forecast in 2034 | USD 57.12 Billion |
| Growth Rate | 6.35% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Metso, Tomra Systems ASA, Buhler Group, Terex Corporation, Vecoplan AG, SSI Shredding Systems, Inc., Morbark, LLC, Danieli & C. Officine Meccaniche S.p.A., Lefort SA, General Kinematics, BHS-Sonthofen GmbH, Forrec srl, Coparm Srl, Marel, Machinex Industries Inc., Sherbrooke OEM Ltd, Pellenc ST |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The recycling equipment market is segmented primarily by the type of machinery and the material it is designed to process. Shredders and balers remain the backbone of the industry, providing the necessary volume reduction for efficient transport and downstream processing. However, the sorting segment is witnessing the most significant technological leap, with NIR (Near Infrared) and XRF (X-ray Fluorescence) sorters becoming standard for high-purity metal and plastic recovery. By material, the metal recycling sector continues to lead due to the high economic value of steel, aluminum, and copper scrap, but the plastic recycling segment is growing at a faster rate due to the global backlash against single-use plastics and new regulatory packaging requirements.
- By Equipment Type:
- Shredders: Heavy-duty industrial shredders for metals, wood, and bulky waste.
- Balers: Vertical and horizontal balers for compacting paper, plastic, and cardboard.
- Granulators: Precision cutting machines for plastic and rubber downsizing.
- Sorters: Optical, magnetic, and eddy current separators for material categorization.
- Shears & Crushers: Specifically for scrap metal processing and construction waste.
- By Material Type:
- Metal Recycling: High-capacity processing for automotive and industrial scrap.
- Plastic Recycling: Lines for PET, HDPE, and LDPE washing and pelletizing.
- Electronic Waste (E-waste): Specialized equipment for PCB crushing and rare metal recovery.
- Paper and Cardboard: Large-scale pulping and de-inking preparation equipment.
- Wood and Construction: Heavy-duty crushers for C&D (Construction and Demolition) waste.
Regional Highlights
- Europe: The market leader, driven by the EU Circular Economy Package and strict landfill taxes that make recycling the most economically viable option. Germany and Italy are key manufacturing hubs for recycling machinery.
- Asia-Pacific: The fastest-growing region, with China’s "Operation National Sword" and India’s new Waste Management Rules creating a massive domestic demand for advanced processing equipment.
- North America: Focused on technological upgrades and the modernization of Materials Recovery Facilities (MRFs) with robotic sorting to combat high labor costs.
- Middle East & Africa: Emerging market with increasing investment in waste-to-energy and formal recycling facilities in the UAE, Saudi Arabia, and South Africa.
- Latin America: Growth is concentrated in Brazil and Mexico, focusing on metal scrap and plastic recycling to support local manufacturing industries.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Recycling Equipment Market.- Metso
- Tomra Systems ASA
- Buhler Group
- Terex Corporation
- Vecoplan AG
- SSI Shredding Systems, Inc.
- Morbark, LLC
- Danieli & C. Officine Meccaniche S.p.A.
- Lefort SA
- General Kinematics
- BHS-Sonthofen GmbH
- Forrec srl
- Coparm Srl
- Machinex Industries Inc.
- Sherbrooke OEM Ltd
- Pellenc ST
- Andritz AG
- Cumberland (A Brand of ACS Group)
- Eldan Recycling
- Lindner-Recyclingtech GmbH
Frequently Asked Questions
What is the projected market size of the Recycling Equipment Market by 2034?
The global recycling equipment market is projected to reach approximately USD 57.12 Billion by 2034, growing at a steady CAGR of 6.35% from 2025.
Which region is expected to grow the fastest in the recycling equipment industry?
The Asia-Pacific region is expected to be the fastest-growing market due to rapid urbanization, increased waste generation, and favorable government regulations in countries like China and India.
What are the primary drivers of the recycling equipment market?
Key drivers include stringent government regulations regarding waste management (EPR), the rising cost of raw materials, and the global push toward a circular economy.
Which material segment holds the largest share in the recycling equipment market?
The Metal Recycling segment holds the largest share because of the significant economic value and high recycling rate of ferrous and non-ferrous metals compared to other materials.
How is AI impacting the recycling equipment market?
AI is revolutionizing the market through automated robotic sorting systems that can identify and separate materials with much higher accuracy and speed than manual sorting, significantly improving the purity of recycled outputs.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
