Recycled Aluminum Market
Recycled Aluminum Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711696 | Published On : November 12, 2026 |
Format : 


 | Author : Shamin Verma
Recycled Aluminum Market Size
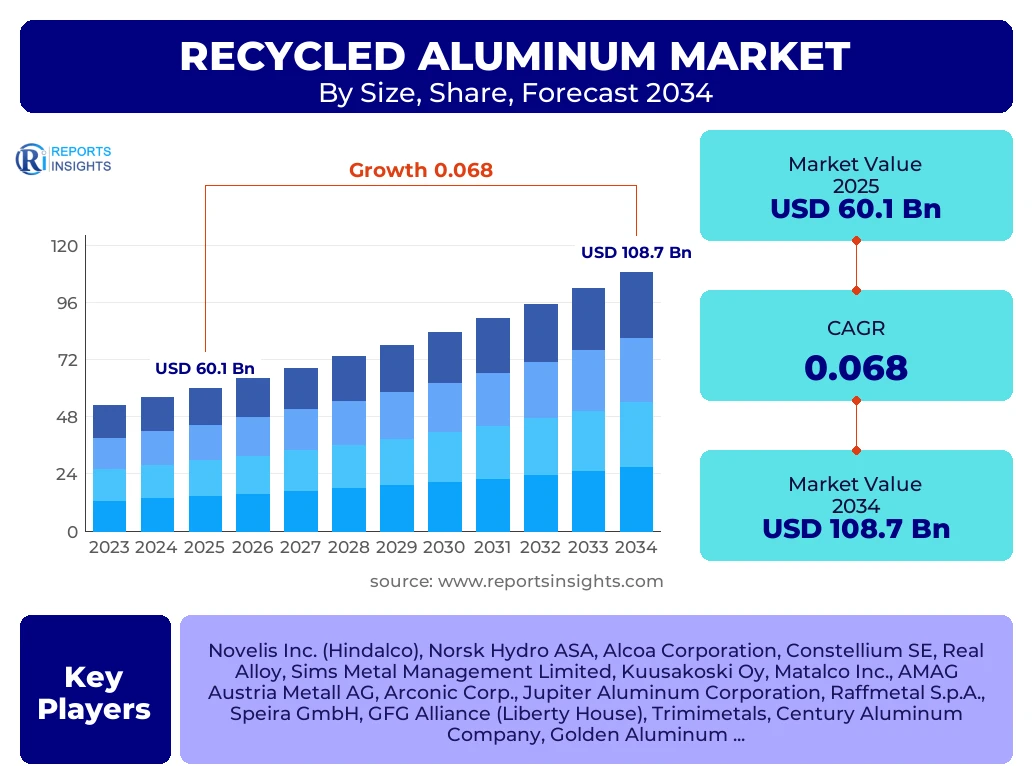
According to Reports Insights Consulting Pvt Ltd, The Recycled Aluminum Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.8% between 2025 and 2034. The market is estimated at USD 64.2 Billion in 2026 and is projected to reach USD 108.7 Billion by the end of the forecast period in 2034.
Key Recycled Aluminum Market Trends & Insights
The global recycled aluminum landscape is undergoing a structural transformation driven by the aggressive decarbonization mandates across the automotive and packaging sectors. Analysis of regional industrial activities indicates that the shift from primary to secondary aluminum production is no longer merely a cost-saving measure but a core strategic pillar for achieving net-zero emissions. Market participants are increasingly investing in advanced sorting technologies, such as Laser-Induced Breakdown Spectroscopy (LIBS) and X-ray Transmission (XRT), to enhance the purity of post-consumer scrap. This technological evolution allows for the production of high-grade alloys that were previously only possible using primary bauxite-derived aluminum. Furthermore, the integration of circular economy principles within the aerospace and construction industries is creating a robust pipeline for long-term demand stability.
The competitive benchmarking of the market reveals a high degree of consolidation among tier-one players who are vertically integrating their supply chains to secure consistent scrap inflows. Regional insights suggest that while China remains the dominant producer and consumer, the European Union is emerging as the fastest-growing market in terms of regulatory maturity and the implementation of green aluminum standards. The packaging industry, particularly for beverage cans, continues to represent the largest segment by volume due to the infinite recyclability of aluminum without loss of material properties. Innovations in alloy development are also enabling the automotive sector to utilize higher percentages of recycled content in structural components, significantly reducing the lifecycle carbon footprint of electric vehicles.
- Largest Region: Asia-Pacific, led by China and India, holds the highest market share due to massive infrastructure development and a robust manufacturing base.
- Fastest Growing Region: Europe is anticipated to witness the highest CAGR, propelled by the European Green Deal and stringent Circular Economy Action Plan targets.
- Largest Segment by Share: The Automotive & Transportation segment dominates the market, fueled by the demand for lightweighting in both internal combustion and electric vehicles.
- Technological Trend: Adoption of AI-driven robotic sorting and digital scrap tracking systems is optimizing the efficiency of secondary smelting operations globally.
Key Takeaways Recycled Aluminum Market Size & Forecast
The long-term forecast for the recycled aluminum market reflects a fundamental shift in global metallurgical preferences. Strategic analysis suggests that the market will experience sustained growth as the energy intensity of primary aluminum production becomes increasingly untenable under global carbon pricing frameworks. Stakeholders are focusing on closing the loop in the industrial manufacturing cycle, where "old scrap" from demolished buildings and end-of-life vehicles is treated as a critical resource rather than waste. The forecast period 2025–2034 is expected to see a significant narrowing of the price gap between primary and recycled aluminum, as "green premiums" become more prevalent in the market, rewarding producers who can certify low-carbon production methods.
Financial projections indicate that investment in secondary smelting capacity will outpace primary smelting expansions in most developed economies. The resilience of the recycled aluminum market is further bolstered by its 95 percent energy saving compared to primary smelting, which provides a natural hedge against volatile energy prices. Supply chain diversification and the regionalization of scrap collection networks are identified as critical success factors for maintaining margins. As the global supply of end-of-life aluminum increases, the market is poised to transition from a scrap-processing industry to a high-tech material manufacturing powerhouse, capable of meeting the rigorous standards of the electronics and telecommunications sectors.
- Dominant Country: China remains the global leader in both scrap processing and secondary aluminum production, accounting for over 40 percent of global capacity.
- Sustainability Impact: Every ton of recycled aluminum saves approximately 14,000 kWh of energy and prevents 9 tons of CO2 emissions.
- Growth Catalyst: The rapid expansion of the Electric Vehicle (EV) market is a primary driver, as EVs require significantly more aluminum for battery enclosures and chassis components.
- Strategic Move: Leading aluminum producers are forming strategic partnerships with waste management firms to secure high-quality scrap supplies for the next decade.
Recycled Aluminum Market Drivers Analysis
The upward trajectory of the recycled aluminum market is underpinned by a confluence of environmental, economic, and regulatory factors. As industrial sectors face mounting pressure to reduce Scope 3 emissions, recycled aluminum offers a turnkey solution for carbon footprint reduction. The economic viability of recycling, coupled with the rising cost of energy required for primary electrolysis, is compelling manufacturers to maximize secondary content. The following table highlights the primary drivers and their projected impact on the market CAGR through 2034.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Decarbonization Mandates | +2.1% | Global (Strongest in Europe) | 2025–2034 |
| Automotive Lightweighting & EV Proliferation | +1.8% | North America, China, Germany | 2025–2030 |
| 95% Energy Savings vs. Primary Production | +1.5% | Global | Continuous |
| Circular Economy Packaging Regulations | +1.4% | EU-27, United Kingdom | 2026–2034 |
Recycled Aluminum Market Restraints Analysis
Despite the positive outlook, the market faces significant headwinds related to the quality and consistency of scrap supply. The contamination of aluminum scrap with other metals like iron, zinc, and copper often complicates the smelting process and limits the end-use applications of the resulting alloy. Additionally, the fragmented nature of global scrap collection systems leads to logistical inefficiencies that can erode the cost advantages of recycling. The table below outlines the primary restraints affecting market growth.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Contamination & Purity Challenges | -0.9% | Global | Short to Medium Term |
| Scrap Export Restrictions | -0.7% | Russia, China, Southeast Asia | 2025–2028 |
| High Initial CAPEX for Sorting Tech | -0.5% | Developing Nations (India, Brazil) | 2025–2030 |
Recycled Aluminum Market Opportunities Analysis
The transition toward a sustainable industrial model presents substantial opportunities for innovation and market expansion. The development of specialized alloys specifically designed for recyclability, often referred to as "design for circularity," is a burgeoning field. Moreover, the digital transformation of the scrap market through blockchain-based traceability can provide the transparency required for premium "green aluminum" branding. Listed below are the most significant opportunities identified for the forecast period.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advanced Sensor-Based Sorting (LIBS/XRF) | +1.3% | North America, Europe, Japan | 2026–2034 |
| Growth in Sustainable Construction Projects | +1.1% | Middle East, APAC | 2027–2034 |
| Green Aluminum Certification Premiums | +0.9% | Global (Premium Automotive) | 2025–2034 |
Recycled Aluminum Market Challenges Impact Analysis
Market participants must navigate complex challenges ranging from price volatility in the London Metal Exchange (LME) to the lack of standardized global scrap grading. Furthermore, the varying environmental regulations across different jurisdictions create a non-level playing field for global recyclers. The table below provides an analysis of these challenges and their impact on market dynamics.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Volatility in LME Aluminum Prices | -0.8% | Global | Ongoing |
| Lack of Global Scrap Standards | -0.6% | Cross-border Trade | 2025–2030 |
| Informal Sector Competition | -0.4% | Africa, Parts of Asia | Long Term |
Recycled Aluminum Market - Updated Report Scope
The scope of this comprehensive report encompasses the entire value chain of the recycled aluminum industry, from scrap collection and sorting to secondary smelting and end-product integration. It provides a detailed analysis of market dynamics across key geographic regions and industrial sectors. The report utilizes a multi-dimensional approach to forecast market growth, integrating macro-economic indicators, regulatory shifts, and technological breakthroughs. Stakeholders will gain insights into competitive positioning, market share distribution, and the fiscal performance of leading industry players, ensuring a holistic understanding of the market's trajectory from 2025 to 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 60.1 Billion |
| Market Forecast in 2034 | USD 108.7 Billion |
| Growth Rate | 6.8% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Novelis Inc. (Hindalco), Norsk Hydro ASA, Alcoa Corporation, Constellium SE, Real Alloy, Sims Metal Management Limited, Kuusakoski Oy, Matalco Inc., AMAG Austria Metall AG, Arconic Corp., Jupiter Aluminum Corporation, Raffmetal S.p.A., Speira GmbH, GFG Alliance (Liberty House), Trimimetals, Century Aluminum Company, Golden Aluminum, United Company RUSAL. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The recycled aluminum market is segmented into several critical categories that define the flow of materials and value within the industry. By source, the market differentiates between post-consumer scrap—derived from products that have completed their lifecycle—and industrial scrap, which consists of residues from manufacturing processes. The end-use segmentation is particularly vital, as different industries require varying levels of alloy purity and mechanical properties. This granular analysis allows stakeholders to identify high-growth niches and tailor their procurement or production strategies accordingly.
- By Source:
- Post-Consumer Scrap (Old Scrap)
- Industrial Scrap (New Scrap)
- By Product Type:
- Cast Alloys (Used primarily in engine blocks and complex automotive parts)
- Wrought Alloys (Used in structural panels, extrusions, and beverage cans)
- By End-Use Industry:
- Automotive & Transportation (Chassis, body panels, powertrain)
- Packaging (Beverage cans, foil containers, aerosols)
- Building & Construction (Window frames, roofing, facades)
- Electrical & Electronics (Heat sinks, wiring, enclosures)
- Consumer Durables (Appliances, kitchenware)
- Machinery & Equipment
Regional Highlights
The regional distribution of the recycled aluminum market reflects the industrial maturity and environmental priorities of different geographic zones. Asia-Pacific remains the undisputed volume leader, driven by China’s massive automotive sector and its role as a global manufacturing hub. However, Europe is setting the benchmark for the "Circular Economy," with the highest recycling rates and advanced policy frameworks like the Carbon Border Adjustment Mechanism (CBAM), which incentivizes low-carbon materials. North America is witnessing a resurgence in secondary smelting investment as domestic manufacturers look to shore up supply chains and reduce dependence on primary imports. Emerging economies in Southeast Asia and Latin America are also expanding their recycling infrastructure as urbanization accelerates.
- Asia-Pacific: Largest market share, characterized by high demand in the construction and electronics sectors, particularly in China, India, and Vietnam.
- Europe: Fastest growing in terms of high-value green aluminum segments, supported by the EU Circular Economy Action Plan.
- North America: Significant growth in the automotive sector, with major investments in closed-loop recycling systems by tier-one OEMs.
- Middle East: Increasing focus on diversifying industrial output and leveraging the high energy efficiency of recycling to offset high primary smelting costs.
- Latin America: Brazil leads the world in aluminum can recycling rates, providing a model for efficient post-consumer scrap collection.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Recycled Aluminum Market.- Novelis Inc. (Subsidiary of Hindalco Industries)
- Norsk Hydro ASA
- Alcoa Corporation
- Constellium SE
- Real Alloy (A Real Industry Company)
- Sims Metal Management Limited
- Kuusakoski Oy
- Matalco Inc.
- AMAG Austria Metall AG
- Arconic Corporation
- Jupiter Aluminum Corporation
- Raffmetal S.p.A.
- Speira GmbH
- Century Aluminum Company
- United Company RUSAL
- Golden Aluminum
- Ex-Al Aluminum
- DUBAL Holding LLC
- Kobe Steel, Ltd.
- UACJ Corporation
Frequently Asked Questions
What is the current market size and projected growth of the Recycled Aluminum Market?
The market is estimated at USD 64.2 Billion in 2026 and is expected to reach USD 108.7 Billion by 2034, growing at a CAGR of 6.8 percent. This growth is driven by sustainability mandates and the 95 percent energy saving of recycling compared to primary production.
Which industry is the largest consumer of recycled aluminum?
The Automotive & Transportation sector is the largest consumer, utilizing recycled aluminum for lightweight components to improve fuel efficiency and extend the range of electric vehicles. Packaging, particularly beverage cans, follows closely as the second-largest segment.
How does recycled aluminum contribute to carbon neutrality?
Recycled aluminum production emits only 5 percent of the greenhouse gases compared to primary aluminum production. By utilizing scrap, manufacturers can significantly reduce their Scope 3 emissions and meet global net-zero targets.
What are the main challenges in the aluminum recycling process?
The primary challenges include scrap contamination with other metals, the high capital cost of advanced sorting technologies, and the volatility of scrap prices which can impact the margins of secondary smelters.
Which region holds the highest potential for market expansion?
While Asia-Pacific holds the largest share, Europe offers the highest growth potential for high-grade recycled alloys due to stringent environmental regulations and the rapid adoption of green manufacturing standards.
Author
S
Shamin Verma is a Senior Analyst Semiconductor and Electronics Research with over 7+ years of experience in the Semiconductor and Electronics Industry. She specializes in semiconductor market intelligence, electronics supply chain analysis, wafer fabrication trends, competitive benchmarking, demand forecasting, component pricing analysis, emerging technology assessment, integrated circuit market evaluation, and industry ecosystem research. Her expertise in translating complex market data into strategic insights enables organizations to make informed business decisions, identify high-growth opportunities, optimize operational planning, anticipate evolving technology trends, and strengthen their competitive positioning in the global semiconductor and electronics market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
