Rail Mounted Gantry (RMG) Crane Market
Rail Mounted Gantry (RMG) Crane Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711464 | Published On : November 02, 2026 |
Format : 


 | Author : Jonathan Sikka
Rail Mounted Gantry (RMG) Crane Market Size
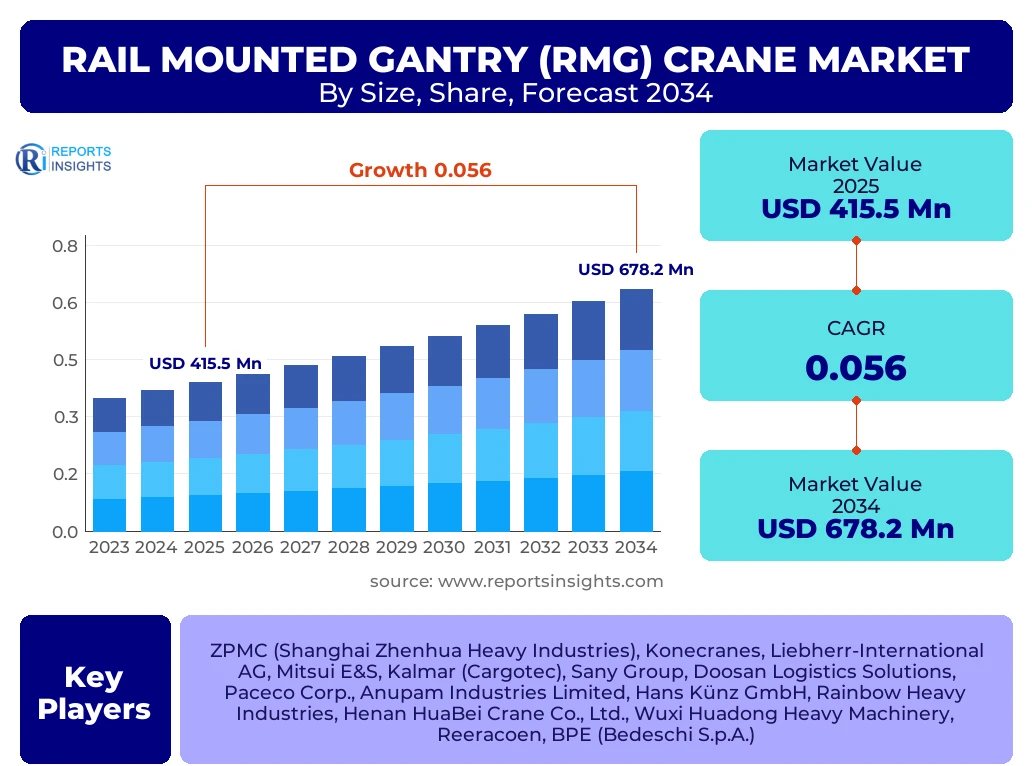
According to Reports Insights Consulting Pvt Ltd, The Rail Mounted Gantry (RMG) Crane Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.6% between 2025 and 2034. The market is estimated at USD 438.4 Million in 2026 and is projected to reach USD 678.2 Million by the end of the forecast period in 2034.
Key Rail Mounted Gantry (RMG) Crane Market Trends & Insights
The global shipping and logistics landscape is undergoing a monumental shift toward automated container handling to mitigate labor shortages and enhance operational throughput. Rail Mounted Gantry (RMG) cranes are at the forefront of this transformation, particularly as ports transition from traditional Rubber Tired Gantry (RTG) systems to rail-mounted solutions that offer superior stacking density and lower carbon footprints. Modern RMG units are increasingly integrated with Terminal Operating Systems (TOS) and utilize sophisticated sensor arrays, including LiDAR and 3D vision, to facilitate remote operation and fully autonomous stacking cycles. This technological convergence is not only improving safety by removing personnel from hazardous yard areas but also significantly reducing energy consumption per container move.
Furthermore, the rise of "Mega-vessels" and the subsequent increase in container traffic volume have necessitated more efficient land use within terminal boundaries. RMGs allow for higher and wider stacking profiles compared to their mobile counterparts, making them the preferred choice for greenfield terminal developments and brownfield modernization projects. The trend toward electrification is another dominant factor, as global port authorities face stringent environmental regulations. By eliminating diesel engines in favor of direct grid connections or high-capacity cable reels, RMG cranes represent a critical component in the "Green Port" initiatives seen across Europe and East Asia. Market intelligence suggests a growing preference for modular RMG designs that allow for easier scalability as terminal traffic grows over time.
- Largest Region: Asia Pacific remains the dominant market shareholder, driven by massive port infrastructure investments in China, India, and Southeast Asian hubs.
- Fastest Growing Region: North America is poised for the highest growth rate as intermodal rail terminals undergo massive modernization to handle increased inland container traffic.
- Largest Segment by Share: The automated RMG (ARMG) segment currently holds the largest market share as operators prioritize long-term labor cost savings and precision.
- Key Technology Trend: Integration of 5G connectivity and edge computing for real-time diagnostics and remote control operations.
- Sustainability Focus: High adoption of regenerative braking systems that feed energy back into the terminal grid during lowering operations.
Key Takeaways Rail Mounted Gantry (RMG) Crane Market Size & Forecast
The Rail Mounted Gantry (RMG) Crane market is characterized by a high barrier to entry due to the capital-intensive nature of the equipment and the specialized engineering required for installation. Strategic analysis indicates that the market is moving toward a service-oriented model where manufacturers provide not just the hardware, but also long-term maintenance contracts and software-as-a-service (SaaS) for yard optimization. As global trade routes stabilize post-pandemic, the demand for RMGs is being fueled by the expansion of inland dry ports and intermodal gateways, particularly in landlocked regions of Central Asia and the Midwestern United States. These facilities require the high-speed, high-density handling capabilities that only RMGs can provide in a rail-to-rail or rail-to-truck transfer environment.
- Leading Country: China is the world leader in both production and domestic deployment of RMG cranes, supported by the Belt and Road Initiative.
- Growth Driver: The expansion of intermodal transport networks is a critical lever, as rail is viewed as a more sustainable alternative to long-haul trucking.
- Market Constraint: High initial investment costs and the requirement for fixed rail infrastructure remain the primary hurdles for smaller terminal operators.
- Strategic Shift: Shift from traditional diesel-powered handling to zero-emission electric RMGs to comply with International Maritime Organization (IMO) targets.
- Competitive Edge: Companies offering customized gantry spans and advanced collision avoidance systems are capturing higher market premiums.
Rail Mounted Gantry (RMG) Crane Market Drivers Analysis
The primary growth engine for the RMG crane market is the global imperative for port automation and the increasing scale of containerized trade. As maritime logistics become more complex, the need for precision and high-speed stacking becomes a strategic necessity for port operators to maintain competitiveness and reduce vessel turnaround times.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Global Port Automation Initiatives | +1.8% | Global (Strongest in APAC and Europe) | 2025 - 2034 |
| Expansion of Intermodal Rail Networks | +1.5% | North America and Central Asia | 2026 - 2030 |
| Environmental Regulations & Decarbonization | +1.2% | European Union and California (USA) | 2025 - 2034 |
| Rise of Ultra-Large Container Vessels (ULCVs) | +1.1% | Major Trans-Pacific and Asia-Europe Routes | 2025 - 2029 |
Rail Mounted Gantry (RMG) Crane Market Restraints Analysis
Despite the strong growth trajectory, the market faces significant headwinds related to the high capital expenditure required for the transition from flexible RTG systems to fixed RMG infrastructure. The lack of flexibility in yard layout once rails are installed often deters smaller terminal operators from adopting this technology.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Capital Expenditure (CAPEX) | -0.9% | Developing Economies (Africa, SE Asia) | 2025 - 2034 |
| Infrastructural Rigidness & Civil Engineering Costs | -0.6% | Brownfield Terminal Sites | 2025 - 2030 |
| Geopolitical Trade Tensions | -0.4% | US-China and EU-Russia Trade Corridors | 2025 - 2028 |
Rail Mounted Gantry (RMG) Crane Market Opportunities Analysis
The integration of advanced digital technologies presents a massive frontier for growth. Opportunities lie in the retrofit market, where older manual RMGs are being upgraded with autonomous control systems, as well as the emerging "Dry Port" sector in developing regions where rail infrastructure is seeing renewed investment.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration of AI and Machine Learning for Predictive Maintenance | +1.4% | Advanced Tech Hubs (South Korea, Germany) | 2026 - 2034 |
| Development of Small-Scale RMGs for Inland Logistics | +1.1% | India, Brazil, and Sub-Saharan Africa | 2027 - 2034 |
| Retrofitting Services for Semi-Automation | +0.9% | Global (Mature Markets) | 2025 - 2034 |
Rail Mounted Gantry (RMG) Crane Market Challenges Impact Analysis
Navigating the complex landscape of cybersecurity in automated systems and the requirement for highly skilled labor to maintain advanced robotic components are significant challenges. Furthermore, the volatility in steel prices and global supply chain disruptions can impact the manufacturing timelines of these massive structures.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Cybersecurity Vulnerabilities in Automated Terminals | -0.5% | High-Tech Port Facilities | 2025 - 2034 |
| Skilled Labor Shortages for Specialized Maintenance | -0.4% | Global | 2025 - 2034 |
| Fluctuating Raw Material Prices (Steel & Copper) | -0.3% | Manufacturing Centers (China, Europe) | 2025 - 2027 |
Rail Mounted Gantry (RMG) Crane Market - Updated Report Scope
This report provides an exhaustive analysis of the global Rail Mounted Gantry (RMG) crane industry, covering the complete value chain from raw material procurement to end-user deployment. It examines the technological shift from manual to fully autonomous systems and analyzes the impact of global trade policies on port infrastructure investments. The scope includes detailed profiling of major players, regional market dynamics, and a deep dive into the segments that are defining the future of container handling.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 415.5 Million |
| Market Forecast in 2034 | USD 678.2 Million |
| Growth Rate | 5.6% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | ZPMC (Shanghai Zhenhua Heavy Industries), Konecranes, Liebherr-International AG, Mitsui E&S, Kalmar (Cargotec), Sany Group, Doosan Logistics Solutions, Paceco Corp., Anupam Industries Limited, Hans Künz GmbH, Rainbow Heavy Industries, Henan HuaBei Crane Co., Ltd., Wuxi Huadong Heavy Machinery, Reeracoen, BPE (Bedeschi S.p.A.) |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Rail Mounted Gantry (RMG) crane market is segmented primarily by its level of technical sophistication and its operational environment. The shift toward fully automated systems is the most significant trend within the segmentation, as it addresses the core industry pain points of labor cost and operational consistency. Capacity-based segmentation is also critical, as the trend toward larger vessels and higher stacking requirements pushes the market toward cranes capable of handling over 60 tons with wider spans.
- By Type:
- Single Girder: Primarily used for smaller facilities or specialized industrial applications where weight and cost are primary factors.
- Double Girder: The industry standard for high-volume container terminals, offering superior stability and capacity for multi-row stacking.
- By Capacity:
- Below 40 Tons: Used in smaller inland terminals and regional rail hubs.
- 40-60 Tons: The most common segment for standard ISO container handling in maritime ports.
- Above 60 Tons: Growing segment driven by the need to handle twin-20ft containers and heavy-lift specialized cargo.
- By Automation Level:
- Manual: Traditional systems requiring on-board operators, still prevalent in developing markets.
- Semi-Automated: Systems where the long travel and stacking are automated, but final placement is handled remotely.
- Fully Automated (ARMG): The high-growth segment integrated with TOS for hands-off container management.
- By Application:
- Sea Ports/Container Terminals: The largest revenue contributor, focused on high-throughput maritime logistics.
- Intermodal/Railway Terminals: The fastest-growing application as rail becomes the backbone of sustainable inland logistics.
Regional Highlights
- Asia Pacific: Holds over 45% of the global market share. The presence of the world’s busiest ports in China, combined with massive state-led investments in automation, makes this the cornerstone of the industry.
- North America: Expected to witness the highest CAGR through 2034. The revitalization of the U.S. rail system and the expansion of inland "dry ports" to relieve coastal congestion are the primary drivers.
- Europe: A pioneer in green technology and automation. Ports like Rotterdam, Hamburg, and Antwerp are setting global standards for zero-emission, fully automated RMG yards.
- Middle East: Strong growth in the UAE and Saudi Arabia as part of their national visions to become global logistics hubs, with a focus on cutting-edge automated infrastructure.
- Latin America & Africa: Emerging markets where port privatization and infrastructure modernization are slowly introducing RMG systems to replace aging mobile equipment.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Rail Mounted Gantry (RMG) Crane Market.
- ZPMC (Shanghai Zhenhua Heavy Industries)
- Konecranes
- Liebherr-International AG
- Mitsui E&S
- Kalmar (Cargotec Corporation)
- Sany Group
- Doosan Logistics Solutions
- Paceco Corp.
- Anupam Industries Limited
- Hans Künz GmbH
- Rainbow Heavy Industries
- Henan HuaBei Crane Co., Ltd.
- Wuxi Huadong Heavy Machinery
- Terex Corporation
- TMEIC (Toshiba Mitsubishi-Electric Industrial Systems Corporation)
- Bedeschi S.p.A.
- Sumitomo Heavy Industries, Ltd.
- JASO Industrial Cranes
Frequently Asked Questions
What is the primary difference between an RMG and an RTG crane?
The primary difference lies in the mobility and power source. Rail Mounted Gantry (RMG) cranes run on fixed tracks, are typically powered by electricity from the grid, and offer higher stacking density and automation potential. Rubber Tired Gantry (RTG) cranes use tires to move freely within the yard, usually rely on diesel engines, and offer more flexibility but lower stacking precision.
Why is the market for Automated RMGs (ARMGs) growing faster than manual versions?
ARMGs are growing faster because they provide consistent 24/7 operational efficiency, reduce labor costs, and significantly improve safety by removing human operators from the yard. They also integrate seamlessly with modern Terminal Operating Systems to optimize container placement and retrieval speeds.
Which region is expected to lead the RMG crane market by 2034?
Asia Pacific will continue to lead the market in terms of total value and volume due to the sheer scale of port operations in China and Southeast Asia. However, North America is expected to show the fastest growth rate as its rail-based inland logistics infrastructure modernizes.
What role does sustainability play in the Rail Mounted Gantry crane market?
Sustainability is a major driver as ports aim for net-zero emissions. RMGs are inherently more eco-friendly than diesel RTGs because they are electric. Modern RMGs also use regenerative drive systems that capture energy during container lowering to power other port operations, reducing the overall carbon footprint.
What are the main challenges in implementing RMG systems in existing ports?
The main challenges are high capital costs and the "brownfield" challenge. Installing RMGs requires significant civil engineering for the rail tracks and power infrastructure, which can disrupt existing terminal operations. Furthermore, the fixed nature of the tracks limits the future flexibility of the yard layout compared to mobile solutions.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
