Radiation Cured Market
Radiation Cured Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711917 | Published On : November 21, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Radiation Cured Market Size
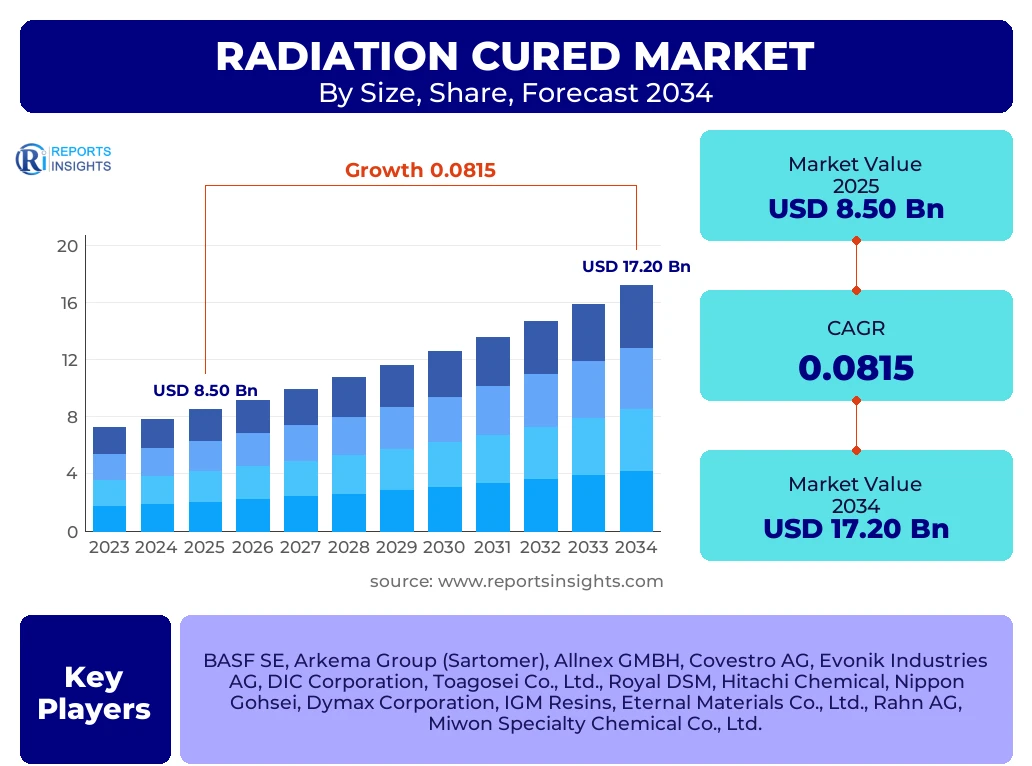
According to Reports Insights Consulting Pvt Ltd, The Radiation Cured Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 8.15% between 2025 and 2034. The market is estimated at USD 9.19 Billion in 2026 and is projected to reach USD 17.20 Billion by the end of the forecast period in 2034.
Key Radiation Cured Market Trends & Insights
The radiation cured market is currently undergoing a transformative phase driven by the convergence of industrial automation and stringent environmental mandates. Strategic shifts toward solvent-free formulations and the adoption of high-efficiency curing technologies are reshaping the competitive landscape. Modern manufacturing ecosystems are increasingly prioritizing "instant-dry" solutions to enhance throughput and reduce energy consumption. Furthermore, the integration of smart manufacturing and Internet of Things (IoT) sensors into curing lines allows for real-time monitoring of dosage and intensity, ensuring consistent product quality across large-scale production cycles. These developments are particularly evident in the electronics and packaging sectors, where precision and speed are non-negotiable performance metrics.
- Largest Region: Asia Pacific remains the dominant market shareholder, accounting for over 42% of global demand due to the concentration of electronics and automotive manufacturing hubs in China, Japan, and South Korea.
- Fastest Growing Region: Southeast Asia is projected to witness the highest growth rate, fueled by rapid industrialization and the migration of manufacturing facilities to Vietnam and Thailand.
- Largest Segment by Type: Radiation-cured coatings represent the largest segment, widely utilized in wood flooring, metal packaging, and plastic components for their superior durability.
- Emerging Technology: UV-LED curing technology is rapidly replacing traditional mercury vapor lamps due to its lower heat emission, energy efficiency, and longer operational lifespan.
- Sustainability Focus: There is a significant increase in the development of bio-based oligomers and monomers to meet the growing demand for sustainable and green chemical solutions.
Key Takeaways Radiation Cured Market Size & Forecast
The global radiation cured market is positioned for robust growth as industries pivot from conventional thermal curing to more efficient ultraviolet (UV) and electron beam (EB) processes. This transition is not merely a technical upgrade but a strategic response to global energy volatility and carbon neutrality goals. Market participants are heavily investing in Research and Development (R&D) to broaden the compatibility of radiation-curable materials with diverse substrates, including heat-sensitive plastics and complex 3D-printed geometries. The forecast period suggests a sustained trajectory of value expansion, particularly as the "circular economy" gains traction in the packaging and printing industries.
- Market Leadership: China continues to lead the global market in both production capacity and consumption, specifically within the consumer electronics and furniture segments.
- Growth Engine: The digital printing industry is a primary growth engine, with UV-curable inks becoming the standard for wide-format and industrial inkjet applications.
- Regulatory Influence: REACH and other regional VOC (Volatile Organic Compound) regulations are acting as catalysts, forcing manufacturers to abandon solvent-borne systems in favor of radiation-cured alternatives.
- Material Innovation: High-performance photoinitiators and dual-cure systems are enabling applications in thicker and opaque coatings that were previously difficult to cure using traditional radiation methods.
- Strategic Consolidation: The market is seeing increased M&A activity as major chemical conglomerates acquire niche players to strengthen their portfolio of specialty UV resins and additives.
Radiation Cured Market Drivers Analysis
The primary driver for the radiation cured market is the urgent global shift toward sustainable manufacturing practices. Traditional thermal curing methods are energy-intensive and often involve the emission of harmful volatile organic compounds (VOCs). Radiation curing, which utilizes UV light or electron beams to trigger a photochemical reaction, offers a nearly solvent-free process that aligns with the environmental objectives of modern enterprises and government regulations.
Additionally, the demand for increased productivity and reduced manufacturing cycle times is pushing companies to adopt radiation-cured solutions. The ability to achieve near-instantaneous curing allows for immediate downstream processing, such as stacking, packaging, or further assembly, which significantly reduces work-in-progress (WIP) inventory and footprint requirements on the factory floor.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent VOC Regulations | +2.1% | European Union & North America | 2025 - 2034 |
| Adoption of UV-LED Technology | +1.8% | Global / China | 2025 - 2030 |
| Expansion in Electronics Industry | +1.5% | South Korea / Taiwan / Vietnam | 2026 - 2034 |
Radiation Cured Market Restraints Analysis
One of the significant barriers to market expansion is the high initial capital expenditure required for installing radiation curing equipment. While the long-term operational costs are lower, the upfront investment in UV-LED arrays or EB accelerators can be prohibitive for small and medium-sized enterprises (SMEs) currently utilizing traditional gas-fired ovens.
Furthermore, the cost of raw materials, specifically high-performance photoinitiators and specialty oligomers, remains higher than those used in solvent-based or water-based systems. Fluctuations in the global supply chain for these specialized chemicals can lead to price volatility, making it challenging for manufacturers to maintain consistent margins in highly competitive segments like wood coatings or general industrial finishes.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Equipment Costs | -1.2% | Developing Markets / India | 2025 - 2028 |
| Raw Material Price Volatility | -0.8% | Global | 2025 - 2034 |
Radiation Cured Market Opportunities Analysis
The rise of Additive Manufacturing (3D Printing) presents a monumental opportunity for the radiation cured market. Stereolithography (SLA) and Digital Light Processing (DLP) technologies rely almost exclusively on UV-curable resins. As 3D printing transitions from prototyping to functional end-use parts in automotive and medical sectors, the volume of radiation-curable materials required is expected to surge.
Another promising avenue is the development of bio-renewable and circular economy-compliant radiation-cured resins. Brands in the consumer goods and luxury packaging sectors are seeking ways to reduce their petroleum footprint. Companies that can provide high-performance, bio-based UV resins that do not compromise on chemical resistance or finish quality will likely capture a significant premium in the coming decade.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Growth in 3D Printing Resins | +2.4% | United States / Germany | 2026 - 2034 |
| Development of Bio-based Resins | +1.3% | Nordic Countries / North America | 2027 - 2034 |
| Smart Packaging and Functional Inks | +1.1% | Japan / UK | 2025 - 2034 |
Radiation Cured Market Challenges Impact Analysis
Technical limitations regarding "shadow areas" and opaque substrates remain a challenge for radiation curing. Since UV curing requires a direct line of sight, complex three-dimensional objects can sometimes have uncured or "tacky" areas in recessed sections. While dual-cure systems (combining UV with thermal or moisture cure) exist, they add complexity and cost to the manufacturing process.
Additionally, health and safety concerns regarding the handling of certain monomers and photoinitiators require rigorous workplace protocols. Regulatory bodies like ECHA (European Chemicals Agency) frequently update their lists of restricted substances, which forces manufacturers to constantly reformulate their products, leading to increased R&D costs and potential disruptions in product availability.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Curing Limitations on 3D Geometries | -0.7% | Automotive Sector / Global | 2025 - 2034 |
| Evolving Chemical Safety Regulations | -0.5% | European Union | Continuous |
Radiation Cured Market - Updated Report Scope
This report provides a comprehensive examination of the global radiation cured ecosystem, analyzing the symbiotic relationship between chemical suppliers and equipment manufacturers. The scope encompasses detailed volume and value forecasts across various chemistries, including acrylates and epoxies, and evaluates the performance of these materials across diverse application landscapes such as consumer electronics, aerospace, and high-speed printing. By integrating macroeconomic indicators with bottom-up industry data, the report offers a granular view of the market's future trajectory.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 8.50 Billion |
| Market Forecast in 2034 | USD 17.20 Billion |
| Growth Rate | 8.15% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, Arkema Group (Sartomer), Allnex GMBH, Covestro AG, Evonik Industries AG, DIC Corporation, Toagosei Co., Ltd., Royal DSM, Hitachi Chemical, Nippon Gohsei, Dymax Corporation, IGM Resins, Eternal Materials Co., Ltd., Rahn AG, Miwon Specialty Chemical Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The radiation cured market is segmented based on product type, curing technology, and end-use application, reflecting a highly specialized chemical landscape. Acrylate-based systems dominate the market due to their rapid reaction rates and excellent mechanical properties. However, the market is seeing a diversification into cationic curing systems for specific applications where adhesion to difficult substrates and low shrinkage are paramount. The segmentation analysis reveals that the versatility of these materials is the primary reason for their adoption across disparate industrial sectors.
- By Product Type:
- Radiation Cured Coatings (Overprint Varnishes, Wood Finishes, Automotive Clearcoats)
- Radiation Cured Inks (Digital Inkjet, Offset, Packaging Inks)
- Radiation Cured Adhesives (Electronic Assembly, Medical Devices, Lamination)
- Radiation Cured Sealants
- By Curing Technology:
- Ultraviolet (UV) Curing (Mercury Vapor, UV-LED)
- Electron Beam (EB) Curing
- By Application:
- Electronics (Semiconductors, Printed Circuit Boards, Displays)
- Printing & Packaging (Flexible Packaging, Labels, Folding Cartons)
- Wood & Furniture (Flooring, Cabinetry)
- Automotive (Interior Trim, Headlamps, Refinish)
- Healthcare (Medical Adhesives, Dental Composites)
Regional Highlights
- Asia Pacific: Holds the largest market share (over 40%) and is the production powerhouse for radiation-curable resins, driven by massive manufacturing infrastructure in China and India.
- North America: A leader in innovation, particularly in EB curing and medical-grade UV adhesives, with a strong focus on high-value aerospace applications.
- Europe: The region is characterized by the strictest environmental regulations, which have accelerated the adoption of waterborne UV and bio-based coatings in Germany, France, and Italy.
- Latin America: Expected to show steady growth in the furniture and wood finishing sectors, particularly in Brazil and Mexico.
- Middle East & Africa: Emerging opportunities in the construction and metal coating sectors as the region looks to diversify its industrial base.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Radiation Cured Market.- BASF SE
- Arkema Group (Sartomer)
- Allnex GMBH
- Covestro AG
- Evonik Industries AG
- DIC Corporation
- Toagosei Co., Ltd.
- Royal DSM
- Hitachi Chemical
- Nippon Gohsei
- Dymax Corporation
- IGM Resins
- Eternal Materials Co., Ltd.
- Rahn AG
- Miwon Specialty Chemical Co., Ltd.
- Double Bond Chemical Ind. Co., Ltd.
- Jiangsu Litian Technology Co., Ltd.
- Kurogane Kasei Co., Ltd.
- Soltech Ltd.
Frequently Asked Questions
What is driving the shift from traditional curing to radiation curing?
The shift is primarily driven by the need for faster production speeds, significant energy savings, and the elimination of Volatile Organic Compounds (VOCs), which helps manufacturers comply with global environmental regulations.
Which industry is the largest consumer of radiation-cured products?
The printing and packaging industry remains the largest consumer, specifically for UV-curable inks and overprint varnishes used in high-speed labeling and flexible packaging.
What are the advantages of UV-LED curing over traditional mercury lamps?
UV-LED curing offers longer lamp life, lower power consumption, instant on/off capabilities, and produces no ozone or infrared heat, making it suitable for heat-sensitive substrates.
Are there bio-based options available in the radiation cured market?
Yes, many key players are now offering bio-renewable oligomers and monomers derived from plant-based feedstocks to cater to the growing demand for sustainable and carbon-neutral coating solutions.
How does electron beam (EB) curing differ from UV curing?
EB curing does not require photoinitiators as the high-energy electrons directly initiate the polymerization. It offers deeper penetration and is often preferred for food-safe packaging and thick, opaque coatings.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
