Zero Liquid Discharge Market
Zero Liquid Discharge Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711675 | Published On : November 12, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Zero Liquid Discharge Market Size
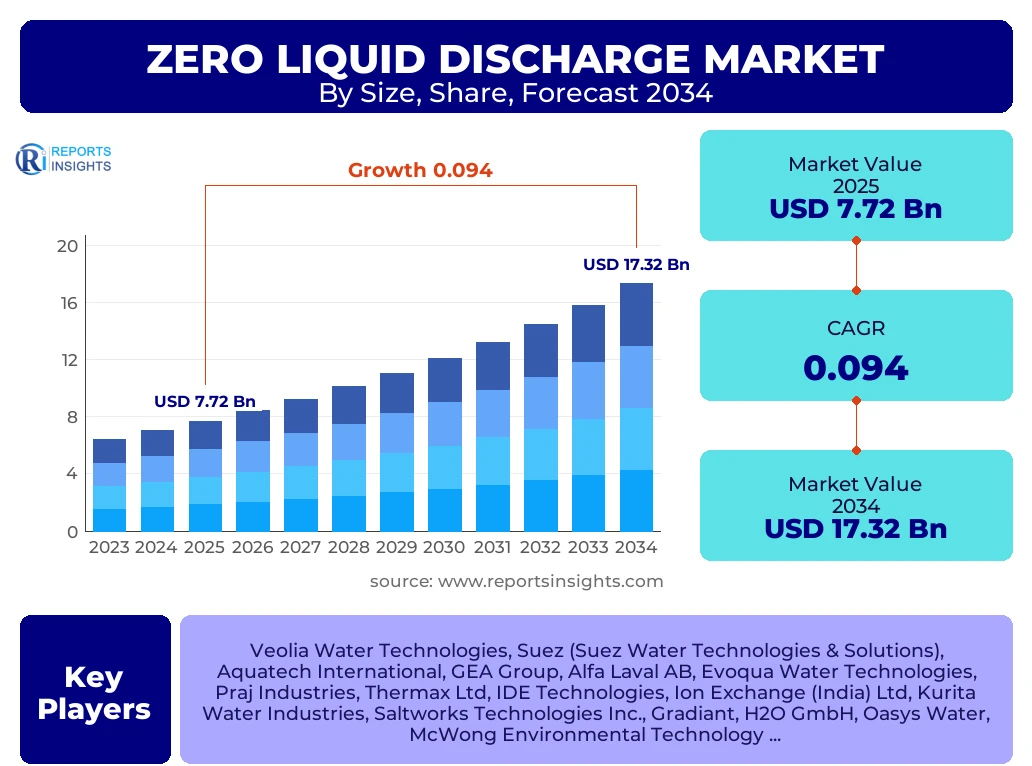
According to Reports Insights Consulting Pvt Ltd, The Zero Liquid Discharge Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 9.4% between 2025 and 2034. The market is estimated at USD 8.45 Billion in 2026 and is projected to reach USD 17.32 Billion by the end of the forecast period in 2034.
Key Zero Liquid Discharge Market Trends & Insights
The global Zero Liquid Discharge (ZLD) market is currently undergoing a transformative phase, driven by the convergence of stringent environmental mandates and the rapid advancement of water purification technologies. As industrial hubs face unprecedented water scarcity, the transition from conventional wastewater treatment to comprehensive ZLD systems has become a strategic imperative for heavy industries. Modern trends indicate a significant shift toward hybrid systems that integrate high-recovery membrane processes with traditional thermal evaporation. This evolution is primarily intended to reduce the high operational costs typically associated with ZLD installations. Furthermore, the integration of artificial intelligence and Internet of Things (IoT) sensors into water management systems allows for real-time monitoring of brine concentration levels, optimizing energy consumption and maximizing resource recovery from industrial effluents.
Regional insights suggest that the Asia-Pacific region, led by China and India, remains the primary engine of market growth due to aggressive industrialization and severe regulatory pressure from national environmental boards. Meanwhile, North America and Europe are pivoting toward the circular economy model, where ZLD is viewed not just as a waste management solution but as a mechanism for recovering valuable minerals and high-purity water for reuse in closed-loop manufacturing processes. The emergence of lithium-ion battery manufacturing and the expansion of the hydrogen economy are providing new avenues for ZLD application, as these sectors require ultra-pure water and generate complex waste streams that necessitate advanced treatment protocols.
- Largest Region: Asia-Pacific, accounting for over 42% of the global market share, driven by industrial expansion in China, India, and Southeast Asia.
- Fastest Growing Region: Middle East & Africa, specifically Saudi Arabia and the UAE, due to extreme water scarcity and massive investment in green hydrogen and petrochemical infrastructure.
- Largest Segment by Technology: Thermal-based systems (Evaporators and Crystallizers) continue to hold the highest value share, although membrane-based systems are expanding at a faster rate.
- Leading End-Use Industry: Energy & Power, particularly coal-fired and nuclear power plants, remains the largest consumer of ZLD solutions globally.
- Emerging Trend: Mineral recovery from brine, where companies are extracting lithium, magnesium, and gypsum from ZLD waste streams to create secondary revenue sources.
Key Takeaways Zero Liquid Discharge Market Size & Forecast
The valuation of the Zero Liquid Discharge market reflects a growing global recognition of water as a finite, high-risk asset for industrial continuity. The projected CAGR of 9.4% is underpinned by the massive scale of industrial projects in emerging economies and the refurbishment of aging infrastructure in developed nations. Stakeholders are increasingly focusing on the "Water-Positive" movement, where corporations aim to return more water to the ecosystem than they consume, naturally positioning ZLD systems at the heart of corporate sustainability strategies. The forecast suggests that the market will nearly double in size over the next decade as technical barriers to entry are lowered by modular, containerized ZLD units that offer lower CAPEX for small-to-medium enterprises.
- Strategic Market Expansion: China and India have implemented mandatory ZLD policies for highly polluting industries like textiles, tanning, and chemicals, creating a non-negotiable demand for these technologies.
- Technological Convergence: The combination of Forward Osmosis (FO) and Membrane Distillation (MD) with traditional MVC (Mechanical Vapor Compression) is significantly reducing the carbon footprint of ZLD plants.
- Investment Dynamics: Institutional investors are prioritizing ESG-compliant industrial projects, making ZLD a prerequisite for securing project financing in the power and mining sectors.
- Cost Reduction: Advancements in membrane durability and energy recovery devices are expected to lower the total cost of ownership by 15-20% over the forecast period.
- Leading Countries: The United States, China, India, Germany, and Saudi Arabia represent the top five markets for ZLD installations and service contracts.
Zero Liquid Discharge Market Drivers Analysis
The primary catalysts for the Zero Liquid Discharge market are rooted in the dual pressures of regulatory compliance and acute resource scarcity. As groundwater tables deplete and surface water contamination reaches critical levels, governments are enforcing "no discharge" zones to protect remaining water bodies. Additionally, the rising cost of industrial water procurement is forcing companies to invest in internal recycling loops to maintain profitability. The shift toward sustainable manufacturing and the "Zero Waste to Landfill" philosophy further bolsters the adoption of ZLD technologies across diverse industrial verticals.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Strict Environmental Regulations & NGT Directives | +3.2% | India, China, USA | 2025 - 2034 |
| Rising Global Water Scarcity & Scarcity Premiums | +2.8% | Middle East, North Africa, Australia | 2026 - 2034 |
| Expansion of the Power & Petrochemical Sectors | +1.9% | Southeast Asia, Gulf Cooperation Council (GCC) | 2025 - 2030 |
| Corporate ESG & Sustainability Commitments | +1.5% | European Union, North America | 2025 - 2034 |
Zero Liquid Discharge Market Restraints Analysis
Despite the strong growth trajectory, the Zero Liquid Discharge market faces significant hurdles, primarily centered on the economic viability of these systems. The high capital expenditure required for thermal evaporators and crystallizers often deters small-scale manufacturers. Furthermore, the energy-intensive nature of ZLD processes conflicts with global efforts to reduce industrial carbon emissions. Technical challenges, such as the management of the final solid salt residue and the corrosion of specialized alloys in high-salinity environments, also serve as significant inhibitors to widespread adoption.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High CAPEX and OPEX Requirements | -2.1% | Global (Impacts SMEs) | 2025 - 2028 |
| Significant Energy Consumption and Carbon Footprint | -1.4% | Europe, North America | 2025 - 2034 |
| Complexity in Solid Waste/Salt Disposal | -0.8% | India, China | 2026 - 2030 |
Zero Liquid Discharge Market Opportunities Analysis
Opportunities in the ZLD market are increasingly found in the intersection of waste treatment and resource recovery. The development of "Value from Waste" technologies, which allow for the selective extraction of high-value salts like sodium sulfate or lithium from industrial brine, is transforming ZLD from a cost center into a profit center. Additionally, the rise of modular and prefabricated ZLD systems offers a scalable solution for remote mining sites and decentralized industrial zones, opening up previously inaccessible market segments.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Resource Recovery (Lithium & Mineral Extraction) | +2.4% | South America (Lithium Triangle), China | 2027 - 2034 |
| Adoption of Low-Energy Membrane Technologies | +1.8% | USA, Germany, Japan | 2026 - 2034 |
| Green Hydrogen Project Water Integration | +1.2% | Australia, Chile, Saudi Arabia | 2028 - 2034 |
Zero Liquid Discharge Market Challenges Impact Analysis
The operational challenges of ZLD systems remain a point of concern for facility managers. Fouling and scaling of membranes and heat exchanger surfaces lead to frequent downtime and increased maintenance costs. Moreover, the lack of standardized regulatory frameworks for ZLD in many developing nations creates an uneven playing field for international players. Fluctuating energy prices also pose a risk to the long-term operational stability of thermal-based ZLD plants, necessitating the integration of renewable energy sources.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Technical Complexity & Lack of Skilled Operators | -1.1% | Developing Nations (SEA, Africa) | 2025 - 2030 |
| Membrane Fouling and Equipment Corrosion | -0.9% | Global | Continuous |
| Regulatory Inconsistency & Policy Ambiguity | -0.7% | Latin America, parts of APAC | 2025 - 2028 |
Zero Liquid Discharge Market - Updated Report Scope
This report provides a comprehensive analysis of the global Zero Liquid Discharge landscape, covering technological advancements, market size estimations, and growth projections across multiple industrial verticals. The scope encompasses an in-depth evaluation of the competitive environment, regional regulatory shifts, and the transition toward hybrid ZLD configurations. It offers strategic insights for technology providers, industrial end-users, and investors looking to navigate the complexities of wastewater management in a water-stressed global economy.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 7.72 Billion |
| Market Forecast in 2034 | USD 17.32 Billion |
| Growth Rate | 9.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Veolia Water Technologies, Suez (Suez Water Technologies & Solutions), Aquatech International, GEA Group, Alfa Laval AB, Evoqua Water Technologies, Praj Industries, Thermax Ltd, IDE Technologies, Ion Exchange (India) Ltd, Kurita Water Industries, Saltworks Technologies Inc., Gradiant, H2O GmbH, Oasys Water, McWong Environmental Technology, Condorchem Envitech, Aquarion AG. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Zero Liquid Discharge market is primarily defined by the technological approach and the specific needs of end-use industries. While thermal evaporation remains the "gold standard" for achieving true zero discharge, membrane-based systems are increasingly utilized as pre-treatment stages to concentrate brine, thereby reducing the load on energy-intensive evaporators. The market is also segmented by end-user, with power plants and chemical manufacturers being the traditional pillars, whereas the pharmaceutical and electronics industries represent the fastest-growing niche segments due to their requirements for high-purity process water.
- By Technology:
- Thermal-Based Systems (Multi-stage Flash, Multi-effect Distillation, Mechanical Vapor Compression)
- Membrane-Based Systems (High-Recovery Reverse Osmosis, Forward Osmosis, Electrodialysis)
- By System Configuration:
- Conventional Systems (Purely Thermal)
- Hybrid Systems (Combined Membrane and Thermal)
- By End-Use Industry:
- Energy & Power (Coal, Gas, Nuclear)
- Chemicals & Petrochemicals
- Mining & Metallurgy
- Pharmaceuticals & Biotechnology
- Textiles & Tanning
- Food & Beverage Processing
Regional Highlights
Regional dynamics are heavily influenced by local water availability and the stringency of environmental policing. The Asia-Pacific region is the clear leader, with China’s "Action Plan for Prevention and Control of Water Pollution" and India’s National Green Tribunal mandates driving massive volumes of new installations. North America follows closely, with the U.S. Environmental Protection Agency (EPA) setting strict effluent limitation guidelines for steam electric power plants. In Europe, the focus is on the circular economy and the recovery of nutrients and minerals, while the Middle East is rapidly adopting ZLD to support its massive desalination and industrial diversification projects.
- Asia-Pacific: Largest market share; dominated by China and India’s coal-to-chemical and textile industries.
- North America: Significant replacement market with a focus on advanced membrane technologies and shale gas produced water treatment.
- Europe: Leading in technological innovation and high-efficiency thermal systems; driven by the EU Green Deal.
- Middle East: Fastest growth in desalination-related ZLD and the emerging green hydrogen sector.
- Latin America: Growing demand in the mining sector, particularly in the lithium and copper belts of Chile and Peru.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Zero Liquid Discharge Market.- Veolia Water Technologies
- Suez (now part of the Veolia group)
- Aquatech International LLC
- GEA Group AG
- Alfa Laval AB
- Evoqua Water Technologies (Xylem)
- Praj Industries Ltd.
- Thermax Ltd.
- IDE Technologies
- Ion Exchange (India) Ltd.
- Kurita Water Industries Ltd.
- Saltworks Technologies Inc.
- Gradiant
- H2O GmbH
- Oasys Water
- McWong Environmental Technology
- Condorchem Envitech
- Aquarion AG
- ENCON Evaporators
- Samco Technologies
Frequently Asked Questions
What is the current market size of the Zero Liquid Discharge industry?
The market is estimated at approximately USD 7.72 Billion in 2025 and is expected to grow steadily at a CAGR of 9.4% through 2034.
Which industry is the largest adopter of ZLD technologies?
The Energy & Power sector is currently the largest end-user, primarily due to the vast amounts of cooling tower blowdown and flue-gas desulfurization (FGD) wastewater generated by power plants.
What are the main technical challenges in implementing ZLD?
Key challenges include high energy consumption, equipment corrosion due to high salt concentrations, and the high cost of managing the resulting solid salt waste.
How do membrane-based ZLD systems differ from thermal ones?
Membrane systems use physical barriers to concentrate salts at lower energy costs but cannot achieve 100% water recovery alone. Thermal systems use heat to evaporate water, leaving only solids, achieving true zero liquid discharge.
Is ZLD economically viable for small-scale industries?
While traditionally expensive, the advent of modular, containerized ZLD units and "Water-as-a-Service" (WaaS) business models is making ZLD more accessible for smaller industrial players.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
