Plastic Pallet Market
Plastic Pallet Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_700318 | Published On : September 25, 2026 |
Format : 


 | Author : Ashraf Shehata
Plastic Pallet Market Size
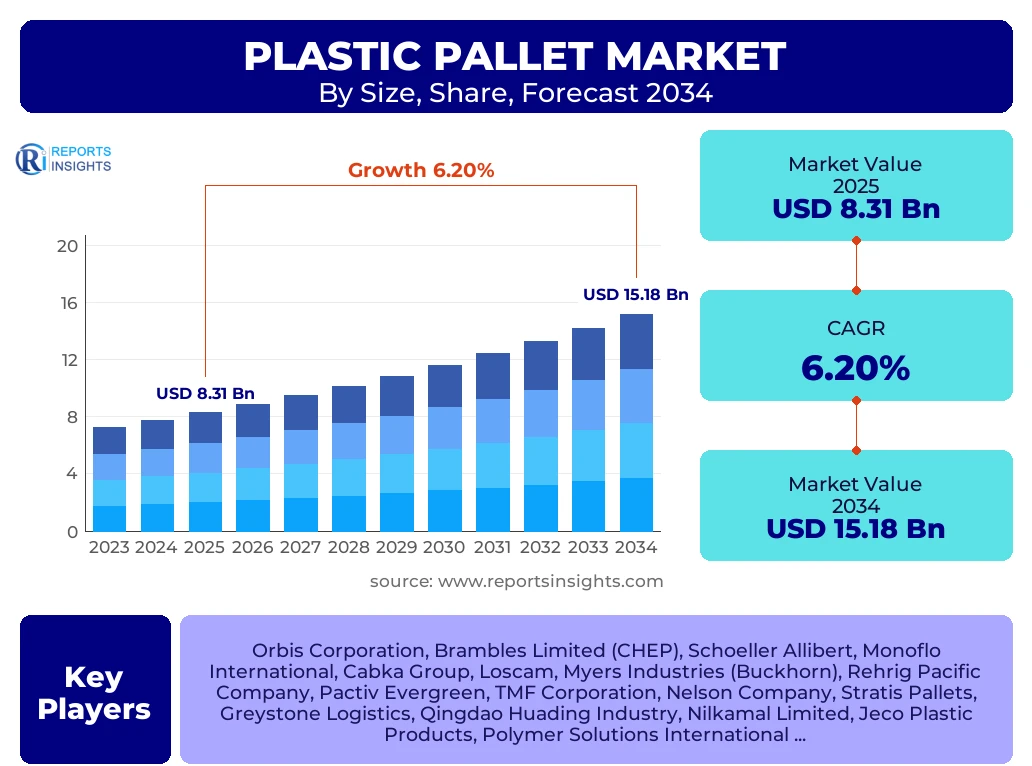
According to Reports Insights Consulting Pvt Ltd, The Plastic Pallet Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.2% between 2026 and 2034. The market is estimated at USD 8.82 Billion in 2026 and is projected to reach USD 15.18 Billion by the end of the forecast period in 2034.
Key Plastic Pallet Market Trends & Insights
The global transition toward automated warehousing and the heightening of sanitary standards across the food and pharmaceutical sectors are the primary catalysts for the Plastic Pallet market. As industries migrate away from traditional wooden pallets due to concerns regarding contamination, splinters, and moisture retention, plastic alternatives have emerged as the gold standard for high-throughput logistics. Current market intelligence indicates that stakeholders are increasingly prioritizing durability and long-term cost-efficiency over initial capital expenditure. Furthermore, the integration of advanced tracking technologies, such as RFID and IoT sensors, into pallet designs is revolutionizing inventory management and supply chain transparency.
Regional dynamics suggest a significant shift toward Asia-Pacific, fueled by rapid industrialization and the expansion of the e-commerce sector in China and India. In mature markets like North America and Europe, the focus has pivoted toward the circular economy, with manufacturers emphasizing the use of 100% recyclable high-density polyethylene (HDPE) and polypropylene (PP). Competitive benchmarking reveals that leading players are expanding their service-based models, such as pallet pooling and leasing, to provide flexible solutions to global enterprises. These trends collectively indicate a market that is maturing through technological innovation and a systemic commitment to sustainable logistics operations.
- Largest Region: Asia-Pacific (APAC) currently holds the dominant market share, accounting for over 35% of global revenue.
- Fastest Growing Region: South East Asia and India are expected to witness the highest CAGR due to burgeoning logistics infrastructure.
- Largest Segment by Type: Nestable Plastic Pallet lead the market in terms of volume due to space-saving benefits during return shipping.
- Leading End-Use Industry: The Food and Beverage sector remains the largest consumer, driven by stringent FDA and international hygiene regulations.
- Material Preference: High-Density Polyethylene (HDPE) remains the most widely used material due to its balance of impact resistance and cost-effectiveness.
Key Takeaways Plastic Pallet Market Size & Forecast
The market forecast through 2034 highlights a steady upward trajectory, underpinned by the global push for carbon footprint reduction and the optimization of supply chain assets. Analysts observe that the market is transitioning from a commodity-based sales model to a value-added service model, where durability and "smart" capabilities dictate market positioning. The increasing cost of wood and the frequent maintenance required for wooden pallets are pushing logistics managers toward plastic as a more viable, long-term asset. This shift is particularly evident in the pharmaceutical industry, where non-porous surfaces are mandatory for maintaining sterile environments.
- The global Plastic Pallet market is expected to surpass the USD 15 billion mark by 2034, reflecting a robust investment in durable logistics.
- Sustainability initiatives, specifically the demand for pallets made from recycled ocean plastics and post-consumer resin, are becoming a key competitive differentiator.
- Rackable pallets are projected to see significant growth in the North American market as high-density storage systems become standard in modern distribution centers.
- The pharmaceutical and chemical industries are the fastest-growing end-users, requiring specialized pallets that resist chemical corrosion and bacterial growth.
- Strategic mergers and acquisitions among key players are consolidating the market, allowing for better economies of scale and global distribution networks.
Plastic Pallet Market Drivers Analysis
The primary drivers of the Plastic Pallet market are rooted in the necessity for operational efficiency and compliance with international trade regulations. As global trade increases, the demand for pallets that meet ISPM 15 standards without requiring expensive heat treatment or fumigation has surged. Furthermore, the rise of automated storage and retrieval systems (ASRS) necessitates pallets with consistent dimensions and weight, a requirement that wooden pallets often fail to meet due to warping and variability. The push for a circular economy is also driving manufacturers to produce pallets that are fully recyclable at the end of their multi-year lifespans.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Adoption of Automated Warehousing (ASRS) | +2.1% | Global (High in North America/Europe) | 2025 - 2034 |
| Stringent Hygiene Standards in Food & Pharma | +1.8% | United States, Germany, Japan | 2025 - 2030 |
| Sustainability and Circular Economy Mandates | +1.4% | European Union, Canada | 2026 - 2034 |
| Expansion of E-commerce Logistics | +1.2% | China, India, Brazil | 2025 - 2034 |
Plastic Pallet Market Restraints Analysis
Despite the growth, the market faces significant restraints, primarily the high initial acquisition cost compared to traditional wooden pallets. For small and medium-sized enterprises (SMEs) with limited capital, the upfront investment required for Plastic Pallet can be a barrier to entry. Additionally, the volatility of petroleum-based raw material prices, such as polyethylene and polypropylene, can lead to unpredictable fluctuations in pallet pricing. The difficulty in repairing Plastic Pallet once they are damaged, unlike wood which can be easily patched, also remains a concern for some heavy-duty users.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Upfront Capital Investment | -1.1% | Emerging Markets (ASEAN, Africa) | 2025 - 2028 |
| Volatility in Polymer Raw Material Costs | -0.8% | Global | 2025 - 2034 |
| Limited Repairability Compared to Wood | -0.5% | Global | 2025 - 2030 |
Plastic Pallet Market Opportunities Analysis
The market is ripe with opportunities, particularly in the integration of digital technology. "Smart Pallets" equipped with GPS, temperature sensors, and shock absorbers represent a high-growth niche, especially for the cold chain logistics of vaccines and perishable goods. There is also a burgeoning opportunity in the development of composite Plastic Pallet that combine different materials to offer superior strength-to-weight ratios. As emerging economies modernize their supply chains, the replacement of low-quality single-use pallets with durable plastic pooling systems offers a massive untapped market for global providers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of IoT-Enabled Smart Pallets | +2.5% | United States, South Korea, Germany | 2026 - 2034 |
| Expansion of Pallet Pooling and Leasing Services | +1.9% | Asia-Pacific, Latin America | 2025 - 2034 |
| Utilization of Recycled Ocean-Bound Plastics | +1.3% | Global | 2027 - 2034 |
Plastic Pallet Market Challenges Impact Analysis
One of the most pressing challenges is the environmental perception of plastic. Even though Plastic Pallet are recyclable, the energy-intensive manufacturing process and the end-of-life management in regions without proper recycling infrastructure pose reputational risks. Furthermore, the market is highly fragmented with numerous local players offering low-cost, low-quality alternatives, which can erode the brand value of premium, durable pallet manufacturers. Ensuring the integrity of the pallet during extreme temperature fluctuations in global shipping routes also remains a technical hurdle for certain material formulations.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Environmental Concerns & Plastic Waste Regulations | -0.9% | Europe, North America | 2025 - 2034 |
| Intense Competition from Low-Cost Local Producers | -0.7% | China, South East Asia | 2025 - 2030 |
| Performance in Extreme Climatic Conditions | -0.4% | Middle East, Russia | 2025 - 2034 |
Plastic Pallet Market - Updated Report Scope
This market research report provides a comprehensive analysis of the Plastic Pallet industry, covering historical data from 2020 to 2024 and delivering precise forecasts for the 2026-2034 period. The scope encompasses a detailed examination of material types, pallet designs, and end-use industrial applications across six major geographical regions. The report evaluates the competitive landscape by profiling the top 20 industry leaders, analyzing their market share, strategic initiatives, and technological advancements. This study serves as a critical tool for stakeholders to understand the shift toward sustainable logistics and the impact of digital transformation on traditional material handling equipment.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 8.31 Billion |
| Market Forecast in 2034 | USD 15.18 Billion |
| Growth Rate | 6.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Orbis Corporation, Brambles Limited (CHEP), Schoeller Allibert, Monoflo International, Cabka Group, Loscam, Myers Industries (Buckhorn), Rehrig Pacific Company, Pactiv Evergreen, TMF Corporation, Nelson Company, Stratis Pallets, Greystone Logistics, Qingdao Huading Industry, Nilkamal Limited, Jeco Plastic Products, Polymer Solutions International, RPP Containers |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Plastic Pallet market is segmented by material, design type, and end-use industry, each reflecting distinct performance requirements and purchasing behaviors. Material-wise, HDPE is favored for its impact strength and durability in cold environments, while PP is chosen for high-heat applications and superior stiffness in racking. The design segmentation—comprising nestable, stackable, and rackable pallets—addresses specific logistical needs: nestability focuses on space optimization for empty returns, while stackability and rackability focus on maximizing vertical storage and load-bearing capacity in heavy industrial warehouses.
- By Material:
- High-Density Polyethylene (HDPE)
- Polypropylene (PP)
- Recycled Material Blends
- Advanced Composites
- By Type:
- Nestable Pallets
- Rackable Pallets
- Stackable Pallets
- Export/One-Way Pallets
- By End-Use Industry:
- Food and Beverage
- Pharmaceuticals and Healthcare
- Chemicals and Petrochemicals
- Consumer Goods and Retail
- Automotive and Industrial Manufacturing
- Logistics and Postal Services
Regional Highlights
Regional market performance is characterized by the varying levels of logistics automation and industrial maturity across different territories. Asia-Pacific is currently the largest and most dynamic region, driven by the massive manufacturing hubs in China and the rapid modernization of retail supply chains in India and Southeast Asia. The region benefits from lower manufacturing costs and a massive volume of export activity that requires durable, ISPM 15-exempt pallets.
- Asia-Pacific: Largest market share; driven by China's "Belt and Road" initiative and India's growing pharmaceutical exports.
- North America: High adoption of rackable and smart pallets; focused on warehouse automation and high-throughput distribution.
- Europe: Leading in sustainability; highest usage of recycled materials and strong regulatory frameworks for circular economy practices.
- Latin America: Emerging market with high potential in the agriculture and food processing sectors in Brazil and Mexico.
- Middle East & Africa: Focused on the chemical industry and oil & gas logistics, requiring specialized, heavy-duty stackable pallets.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Plastic Pallet Market.- Orbis Corporation
- Brambles Limited (CHEP)
- Schoeller Allibert
- Monoflo International
- Cabka Group
- Loscam International
- Myers Industries (Buckhorn)
- Rehrig Pacific Company
- Pactiv Evergreen
- TMF Corporation
- Nelson Company
- Stratis Pallets
- Greystone Logistics
- Qingdao Huading Industry
- Nilkamal Limited
- Jeco Plastic Products
- Polymer Solutions International
- RPP Containers
- Goplasticpallets.com
- Kamps Pallets Inc.
Frequently Asked Questions
What is the projected growth rate of the Plastic Pallet Market through 2034?
The market is expected to grow at a Compound Annual Growth Rate (CAGR) of 6.2%, reaching a total valuation of USD 15.18 Billion by 2034.
Which material is most commonly used in plastic pallet manufacturing?
High-Density Polyethylene (HDPE) is the dominant material due to its exceptional durability, impact resistance, and cost-effectiveness for heavy-duty applications.
Why are Plastic Pallet preferred over wooden pallets in the pharmaceutical industry?
Plastic Pallet are non-porous, moisture-resistant, and easy to sanitize, making them ideal for sterile environments where bacterial growth and wood-borne pests must be eliminated.
Which region currently leads the global Plastic Pallet Market?
Asia-Pacific is the leading region, accounting for the largest market share due to its expansive manufacturing base and the rapid growth of its logistics infrastructure.
How is the "Smart Pallet" trend influencing the market?
Smart pallets integrated with RFID and IoT technology are enhancing supply chain visibility, allowing companies to track assets in real-time and monitor environmental conditions of sensitive goods.
Author
A
Ashraf Shehata is a Senior Analyst Automotive Product and Automotive Services Research with over 5+ years of experience in the Automotive and Automotive Services Industry. He specializes in market intelligence, vehicle demand forecasting, aftermarket analysis, competitive benchmarking, mobility trends, EV market assessment, supply chain evaluation, and pricing strategy across passenger and commercial vehicle segments. His in-depth market research and analytical expertise help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational strategies, respond to evolving industry trends, and strengthen their competitive positioning in the global automotive marketplace.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
