Plasmid Dna Contract Manufacturing Market
Plasmid Dna Contract Manufacturing Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711130 | Published On : October 11, 2026 |
Format : 


 | Author : Jonathan Sikka
Plasmid Dna Contract Manufacturing Market Size
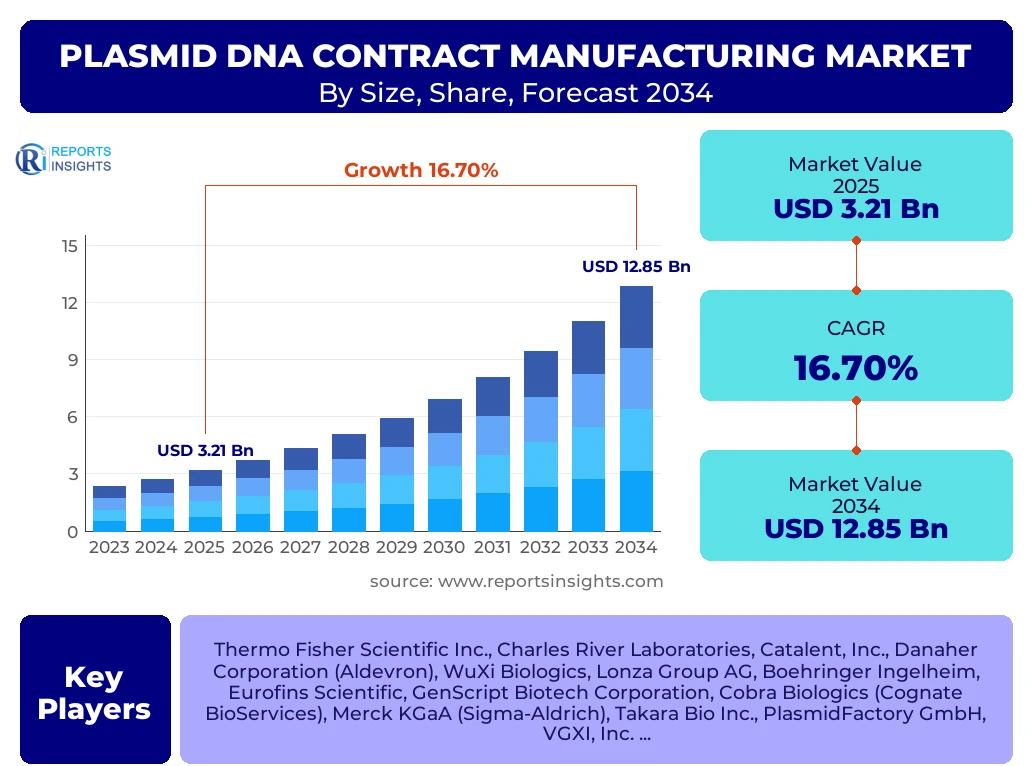
According to Reports Insights Consulting Pvt Ltd, The Plasmid Dna Contract Manufacturing Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 16.7% between 2025 and 2034. The market is estimated at USD 3.74 Billion in 2026 and is projected to reach USD 12.85 Billion by the end of the forecast period in 2034.
Key Plasmid Dna Contract Manufacturing Market Trends & Insights
The global landscape for plasmid DNA (pDNA) contract manufacturing is undergoing a seismic shift driven by the rapid maturation of cell and gene therapies (CGT) and the post-pandemic expansion of mRNA-based vaccine platforms. Market participants are increasingly focusing on vertical integration and the implementation of automated high-throughput manufacturing processes to meet the soaring demand for high-quality, GMP-grade plasmids. Strategic benchmarking reveals that companies are prioritizing lead-time reduction and yield optimization through advanced fermentation and purification technologies, such as continuous chromatography. Furthermore, there is a notable trend toward the decentralization of manufacturing hubs to mitigate supply chain vulnerabilities and ensure proximity to clinical trial sites across emerging markets.
- Largest Region: North America remains the dominant market shareholder, accounting for approximately 42% of global revenue, driven by a robust pipeline of gene therapy clinical trials and heavy investment in biotechnology.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR during the forecast period, fueled by expanding biopharmaceutical infrastructure in China and India and favorable regulatory reforms.
- Largest Segment by Grade: The GMP-grade plasmid DNA segment holds the largest market share as late-stage clinical trials and commercial product approvals necessitate stringent regulatory compliance.
- Largest Segment by Application: Gene Therapy manufacturing is the primary revenue generator, utilizing pDNA as a critical starting material for viral vector production.
Key Takeaways Plasmid Dna Contract Manufacturing Market Size & Forecast
The Plasmid DNA Contract Manufacturing market is characterized by a high barrier to entry due to the technical complexity and regulatory rigor required for GMP production. As the industry moves toward personalized medicine, the demand for "High Quality" (HQ) grade plasmids—a bridge between R&D and GMP—is surging, allowing developers to accelerate timelines while maintaining safety standards. Forecasts suggest that the integration of single-use technologies and digital twin modeling in bioprocessing will significantly enhance scalability and cost-efficiency, shaping the competitive landscape over the next decade. Stakeholders are shifting focus from small-scale academic support to large-scale commercial supply chains as several gene therapies approach blockbuster status.
- The United States is the single largest country market, hosting the majority of top-tier CDMO facilities and therapeutic developers.
- The transition from transient transfection to stable cell line development is a key technical evolution impacting long-term pDNA demand.
- Strategic partnerships and long-term supply agreements between biopharma giants and specialized CDMOs are becoming the industry norm to secure manufacturing slots.
- Viral vector production (AAV, Lentivirus) remains the most significant consumer of plasmid DNA, accounting for over 50% of the total manufacturing volume.
Plasmid Dna Contract Manufacturing Market Drivers Analysis
The primary catalysts for market expansion include the exponential growth of the global cell and gene therapy pipeline and the widespread adoption of mRNA technology for infectious diseases and oncology. Additionally, the increasing outsourcing trend among biopharmaceutical companies to mitigate high capital expenditure and leverage specialized technical expertise is significantly boosting the contract manufacturing sector.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion of Cell and Gene Therapy Pipeline | +6.2% | Global (Strongest in US & EU) | 2025-2034 |
| Adoption of mRNA Vaccine Platforms | +4.8% | North America, Germany, China | 2025-2030 |
| Increased Outsourcing by Biopharma | +3.5% | Global | 2026-2034 |
| Technological Advances in Fermentation | +2.2% | Japan, South Korea, US | 2027-2034 |
Plasmid Dna Contract Manufacturing Market Restraints Analysis
Market growth is tempered by the high cost of GMP-grade manufacturing and the scarcity of skilled workforce capable of managing complex bioprocessing operations. Furthermore, the volatility in raw material supply chains and the stringent, often divergent, global regulatory requirements for plasmid purity pose significant challenges to seamless international operations.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Production and Compliance Costs | -2.5% | Global | 2025-2034 |
| Shortage of Technical Expertise | -1.8% | Western Europe, North America | 2025-2029 |
Plasmid Dna Contract Manufacturing Market Opportunities Analysis
Emerging opportunities lie in the development of DNA-based therapeutics and the expansion of manufacturing capabilities in the Asia-Pacific and Latin American regions. The rise of personalized cancer vaccines and the potential for plasmid DNA to be used in non-viral delivery systems represent significant untapped potential for contract manufacturers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Personalized Neoantigen Vaccines | +4.1% | US, UK, Israel | 2026-2034 |
| Non-Viral Gene Delivery Systems | +3.3% | Global | 2028-2034 |
Plasmid Dna Contract Manufacturing Market Challenges Impact Analysis
The market faces challenges regarding the scalability of high-purity plasmids for large-patient populations and the need for standardized analytical methods across the industry. Competitive pressure from in-house manufacturing by large pharmaceutical companies also threatens the market share of independent CDMOs.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Scalability of Purification Processes | -2.1% | Global | 2025-2030 |
| Regulatory Harmonization Issues | -1.4% | EU, APAC, Brazil | 2025-2034 |
Plasmid Dna Contract Manufacturing Market - Updated Report Scope
This comprehensive report provides an in-depth analysis of the Plasmid DNA Contract Manufacturing market, covering historical data from 2020 to 2024 and a detailed forecast through 2034. The scope includes a granular breakdown of market segments by grade, application, and scale, alongside a competitive analysis of leading global CDMOs. It examines regional dynamics, regulatory landscapes, and the technological innovations driving the next generation of bioprocessing.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 3.21 Billion |
| Market Forecast in 2034 | USD 12.85 Billion |
| Growth Rate | 16.7% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Thermo Fisher Scientific Inc., Charles River Laboratories, Catalent, Inc., Danaher Corporation (Aldevron), WuXi Biologics, Lonza Group AG, Boehringer Ingelheim, Eurofins Scientific, GenScript Biotech Corporation, Cobra Biologics (Cognate BioServices), Merck KGaA (Sigma-Aldrich), Takara Bio Inc., PlasmidFactory GmbH, VGXI, Inc., Waisman Biomanufacturing, AGC Biologics, Resilience, Fujifilm Diosynth Biotechnologies |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The market is segmented to reflect the diverse requirements of therapeutic developers, ranging from early-stage academic research to commercial-scale pharmaceutical production. The differentiation between GMP and Research grade plasmids is a critical factor in pricing and manufacturing timelines, with GMP-grade currently dominating the value share due to the intensive validation and quality control protocols required by health authorities like the FDA and EMA.
- By Grade:
- GMP Grade: Essential for clinical trials and commercial products; highest value segment.
- High Quality (HQ) Grade: Used for tox studies and early trials; offers faster turnaround.
- Research Grade: Primarily for academic use and discovery-stage development.
- By Application:
- Gene Therapy: Use of plasmids as templates for viral vectors (AAV, LV).
- Vaccinology: DNA and mRNA vaccines requiring high-purity plasmid templates.
- Cell Therapy: Modification of immune cells using plasmid-mediated transfection.
- By Scale:
- Clinical Scale: Small to mid-size batches for Phase I-III trials.
- Commercial Scale: Large-scale production for approved therapies with high patient volume.
Regional Highlights
- North America: The largest market globally, characterized by a high concentration of biotech firms and a favorable investment environment for advanced therapies. The United States leads in both demand and production capacity.
- Asia-Pacific: The fastest-growing region, with China and India rapidly expanding their CDMO capabilities to serve both local and international markets. Government subsidies and lower operating costs are attracting significant foreign investment.
- Europe: A mature market with a strong emphasis on R&D and academic collaboration. Germany, the UK, and Switzerland are key hubs for high-tech plasmid manufacturing.
- Latin America & MEA: Emerging markets with increasing focus on infectious disease research and localized vaccine production capabilities.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Plasmid Dna Contract Manufacturing Market.- Thermo Fisher Scientific Inc.
- Charles River Laboratories
- Catalent, Inc.
- Danaher Corporation (Aldevron)
- WuXi Biologics
- Lonza Group AG
- Boehringer Ingelheim
- Eurofins Scientific
- GenScript Biotech Corporation
- Cobra Biologics (Cognate BioServices)
- Merck KGaA (Sigma-Aldrich)
- Takara Bio Inc.
- PlasmidFactory GmbH
- VGXI, Inc.
- Waisman Biomanufacturing
- AGC Biologics
- Resilience
- Fujifilm Diosynth Biotechnologies
Frequently Asked Questions
What is the current market size of the Plasmid DNA Contract Manufacturing market?
The market is estimated to be valued at approximately USD 3.21 Billion in 2025, with a strong upward trajectory as more gene therapies reach the commercialization stage.
Which region is expected to grow the fastest in the plasmid manufacturing sector?
The Asia-Pacific region is expected to witness the fastest growth due to increasing healthcare expenditure, a growing number of clinical trials, and the expansion of local CDMO facilities.
What are the main differences between GMP-grade and HQ-grade plasmids?
GMP-grade plasmids are manufactured under strict current Good Manufacturing Practices with full documentation and validation for clinical use, whereas High-Quality (HQ) grade offers similar purity but with slightly less rigorous documentation, making it faster and more cost-effective for preclinical stages.
How is the rise of mRNA vaccines impacting the plasmid DNA market?
mRNA vaccines require high-purity plasmid DNA as a template for in vitro transcription. The massive global demand for these vaccines has significantly increased the need for large-scale plasmid manufacturing capacity.
What are the primary challenges in scaling up plasmid DNA production?
Key challenges include maintaining plasmid stability in large fermenters, optimizing the removal of host cell impurities (DNA, protein, endotoxins), and managing the shear sensitivity of large DNA molecules during purification.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
