Oxygen Free Copper Market
Oxygen Free Copper Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_705625 | Published On : October 08, 2026 |
Format : 


 | Author : Erika Grotto
Oxygen Free Copper Market Size
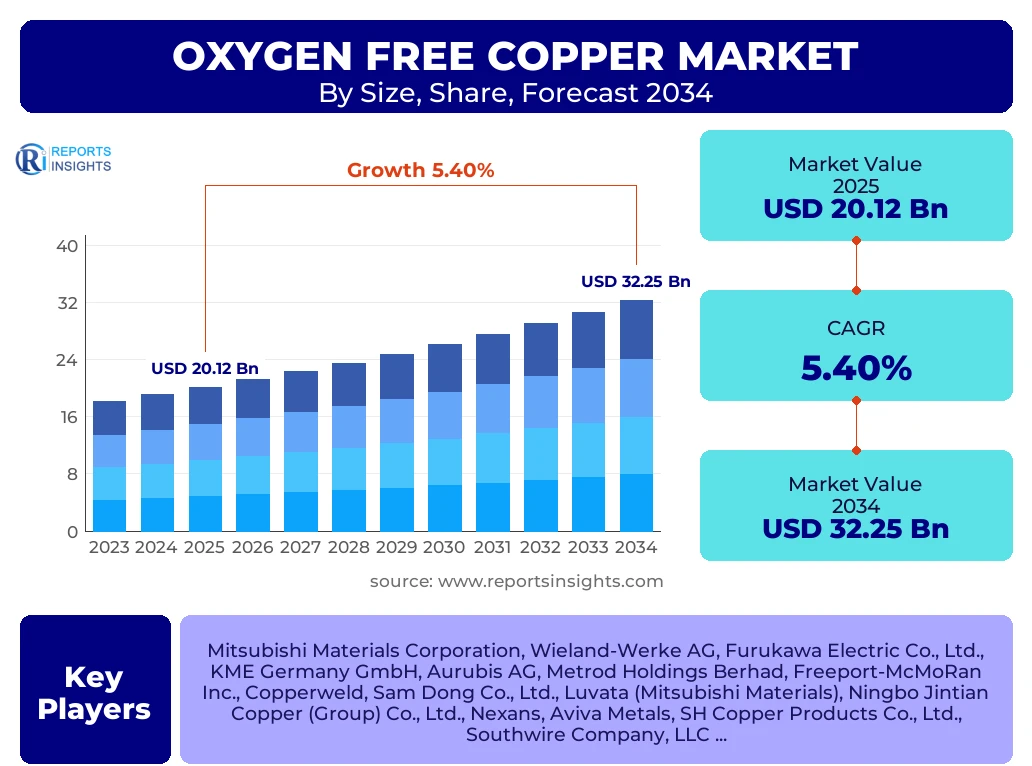
According to Reports Insights Consulting Pvt Ltd, The Oxygen Free Copper Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.4% between 2025 and 2034. The market is estimated at USD 21.21 Billion in 2026 and is projected to reach USD 32.25 Billion by the end of the forecast period in 2034.
Key Oxygen Free Copper Market Trends & Insights
The global Oxygen Free Copper market is currently navigating a period of significant technological evolution, primarily driven by the transition toward high-performance electronic components and the rapid expansion of the electric vehicle (EV) ecosystem. Users and industry stakeholders are increasingly focused on the superior conductivity and thermal properties of oxygen-free copper compared to standard Electrolytic Tough Pitch (ETP) copper. Regional insights suggest a massive pivot toward the Asia-Pacific region, which serves as the primary hub for semiconductor manufacturing and consumer electronics production. Competitive benchmarking indicates that leading companies are investing heavily in vacuum melting technologies and continuous casting processes to achieve higher purity levels, such as the 99.99% (4N) and 99.999% (5N) grades required for advanced applications.
- Largest Region: Asia-Pacific remains the dominant geographical segment, accounting for over 45% of the total market share due to its concentrated manufacturing base in China, Japan, and South Korea.
- Fastest Growing Region: North America is expected to witness the highest growth rate during the forecast period, fueled by massive investments in domestic semiconductor fabrication and 5G infrastructure deployment.
- Largest Product Segment: Oxygen Free Electronic (OFE) copper currently holds the largest market share owing to its critical role in vacuum electronics and high-frequency transmitters.
- Emerging Trend: The integration of oxygen-free copper in cryogenic applications and aerospace propulsion systems is gaining traction as a niche but high-value growth avenue.
Key Takeaways Oxygen Free Copper Market Size & Forecast
The Oxygen Free Copper market size and forecast analysis reveal a robust upward trajectory sustained by the global push for energy efficiency and high-speed data transmission. Market research indicates that the demand for Cu-OFE and Cu-OF grades is no longer restricted to traditional industrial use but is increasingly vital for the miniaturization of electronic devices. The forecast period (2025–2034) is characterized by a steady CAGR, reflecting the essential nature of this material in the green energy transition, particularly in the production of high-efficiency motors and power cables for renewable energy grids.
- Dominant Country: China is the leading consumer and producer of oxygen-free copper, supported by extensive state-led initiatives in telecommunications and electric mobility.
- Strategic Shift: Manufacturers are shifting focus from high-volume low-margin products to high-purity specialized copper rods and wires to meet the stringent requirements of the medical and aerospace sectors.
- Supply Chain Impact: Vertical integration is becoming a key strategy for top players to mitigate the volatility of raw copper cathode prices and ensure a consistent supply of oxygen-free materials.
- Growth Pillar: The proliferation of 5G technology is a primary growth pillar, as oxygen-free copper is indispensable for high-speed signal integrity in antennas and base stations.
Oxygen Free Copper Market Drivers Analysis
The primary drivers of the Oxygen Free Copper market are rooted in the global demand for superior electrical conductivity and the rising complexity of electronic architectures. As industries move toward higher power densities and smaller form factors, the traditional limitations of ETP copper, such as hydrogen embrittlement and lower thermal conductivity, become prohibitive. The surge in electric vehicle production is a massive catalyst, as EVs require high-purity copper for battery interconnects and high-voltage wiring harnesses to maximize range and efficiency. Furthermore, the global expansion of data centers and the 5G network necessitates materials that can handle high frequencies with minimal signal loss.
Another significant driver is the increasing investment in renewable energy infrastructure. Wind and solar power systems utilize oxygen-free copper in transformers and generators to improve energy conversion rates. The material's resistance to corrosion and excellent formability also make it the preferred choice for high-end audio equipment and specialized laboratory instruments. The combination of industrial modernization and the digital revolution ensures a constant demand for high-grade copper variants that can perform under extreme environmental conditions.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Electric Vehicle (EV) Expansion | +1.8% | Global (China, Germany, USA) | 2025-2034 |
| 5G Infrastructure Deployment | +1.2% | Asia-Pacific and North America | 2025-2028 |
| Renewable Energy Grid Upgrades | +0.9% | Europe and India | 2026-2034 |
| Advancements in Semiconductor Tech | +0.7% | Taiwan, South Korea, USA | 2025-2030 |
Oxygen Free Copper Market Restraints Analysis
Despite the strong growth prospects, the market faces significant restraints related to the high cost of production and the volatility of raw material prices. The process of manufacturing oxygen-free copper, which involves vacuum melting or high-purity electrolytic refining, is energy-intensive and requires specialized equipment. This results in a substantial price premium over standard copper grades, which can deter cost-sensitive industries from making the switch unless absolutely necessary for performance. Market fluctuations in the price of LME copper cathodes also add a layer of financial risk for manufacturers and end-users alike.
Environmental regulations and the carbon footprint associated with high-purity refining processes present another challenge. Strict emission norms in Europe and North America force manufacturers to invest in expensive carbon-capture and energy-efficient technologies, which can compress profit margins. Furthermore, the availability of high-quality copper scrap that is suitable for oxygen-free processing is limited, leading to a heavy reliance on primary mining and refining, which is subject to geopolitical instabilities and supply chain bottlenecks.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Production and Processing Costs | -0.8% | Global | Continuous |
| Volatility in Raw Copper Prices | -0.6% | Emerging Markets | 2025-2034 |
| Strict Environmental Regulations | -0.4% | European Union | 2025-2030 |
Oxygen Free Copper Market Opportunities Analysis
Significant opportunities are emerging in the fields of cryogenics, quantum computing, and high-energy physics. Oxygen-free copper is one of the few materials that maintains high thermal and electrical conductivity at extremely low temperatures, making it indispensable for superconducting magnets used in MRI machines and particle accelerators. As the healthcare sector expands and the demand for advanced diagnostic imaging grows, the requirement for OFE copper is expected to scale accordingly. Additionally, the development of fusion energy technology presents a long-term, high-value opportunity for manufacturers capable of producing ultra-pure copper components.
The aerospace and defense sector also offers substantial growth potential. Next-generation satellites and space exploration vehicles require materials that can withstand vacuum environments without outgassing, a property where oxygen-free copper excels. Furthermore, the push for localized semiconductor supply chains in the United States and Europe provides an opportunity for local copper refiners to establish strategic partnerships with chipmakers. Innovations in additive manufacturing (3D printing) using copper powders also open new doors for complex, custom-designed oxygen-free copper parts in industrial engineering.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Space Exploration and Satellite Tech | +0.6% | USA, Russia, India, China | 2027-2034 |
| Medical Imaging (MRI/CT) Demand | +0.5% | Global | 2025-2034 |
| Additive Manufacturing Expansion | +0.4% | Germany, USA, Japan | 2026-2032 |
Oxygen Free Copper Market Challenges Impact Analysis
One of the most pressing challenges in the Oxygen Free Copper market is the technical difficulty of maintaining purity levels throughout the entire supply chain. Even minor contamination during the drawing, annealing, or packaging stages can significantly degrade the material's properties, leading to high rejection rates in sensitive applications like semiconductor lead frames. Ensuring consistent quality across global manufacturing sites requires rigorous quality control protocols and advanced testing infrastructure, which many smaller players lack.
Geopolitical tensions also pose a significant challenge to the stable supply of high-grade copper. With a large portion of the world's copper refining capacity concentrated in specific regions, trade restrictions, tariffs, or political instability can lead to sudden shortages and price spikes. Furthermore, the competition from alternative materials, such as silver-coated copper or advanced aluminum alloys in specific low-weight applications, requires the oxygen-free copper industry to continuously innovate to justify its value proposition in the face of evolving engineering requirements.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Contamination Risks in Manufacturing | -0.5% | Global Manufacturers | Ongoing |
| Geopolitical Supply Chain Risks | -0.4% | APAC and Latin America | 2025-2034 |
| Material Substitution Competition | -0.3% | Aerospace and Electronics | 2028-2034 |
Oxygen Free Copper Market - Updated Report Scope
This report provides a comprehensive analysis of the global Oxygen Free Copper market, covering various grades, product forms, and end-use industries across six major regions. The scope includes detailed market sizing, CAGR projections, and a deep dive into the competitive landscape, highlighting the strategic initiatives of the top 20 industry leaders. By integrating historical data from 2020 to 2024 with a forward-looking forecast up to 2034, the report offers actionable insights for investors, manufacturers, and policy-makers to understand the evolving dynamics of high-purity copper applications.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 20.12 Billion |
| Market Forecast in 2034 | USD 32.25 Billion |
| Growth Rate | 5.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Mitsubishi Materials Corporation, Wieland-Werke AG, Furukawa Electric Co., Ltd., KME Germany GmbH, Aurubis AG, Metrod Holdings Berhad, Freeport-McMoRan Inc., Copperweld, Sam Dong Co., Ltd., Luvata (Mitsubishi Materials), Ningbo Jintian Copper (Group) Co., Ltd., Nexans, Aviva Metals, SH Copper Products Co., Ltd., Southwire Company, LLC, Zhejiang Hailiang Co., Ltd., Oriental Copper Co., Ltd., Watteredge LLC, Hussey Copper, GBC Metals, LLC (Olin Brass) |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Oxygen Free Copper market is segmented based on product type, grade, product form, and end-use industry. This multifaceted segmentation allows for a granular understanding of where the highest value and volume growth is concentrated. The Grade C10100 (OFE) is the premium segment, often required for vacuum applications where any impurity could lead to failure. Meanwhile, the Automotive segment is emerging as the most dynamic end-use category due to the electrification of transport systems worldwide.
- By Product Type:
- Oxygen Free (OF) Copper
- Oxygen Free Electronic (OFE) Copper
- By Grade:
- Cu-OFE (C10100 - 99.99% Purity)
- Cu-OF (C10200 - 99.95% Purity)
- By Product Form:
- Wire and Wire Rods
- Plates and Sheets
- Strips
- Tubes and Pipes
- Busbars and Profiles
- By End-Use Industry:
- Electronics and Electrical (Semiconductors, PCBs, Audio)
- Automotive (Electric Vehicles, Charging Infrastructure)
- Telecommunication (5G, Fiber Optics, Antennas)
- Medical (MRI Machines, X-ray Equipment)
- Industrial (Transformers, Generators, Heat Exchangers)
- Aerospace and Defense (Satellite Components, Radar Systems)
Regional Highlights
- Asia-Pacific: The largest market for oxygen-free copper, driven by China's dominance in electronic manufacturing and the rapid expansion of EV battery production. Japan and South Korea are key hubs for high-purity OFE copper used in high-tech instrumentation.
- North America: The fastest-growing region during the forecast period. The resurgence of domestic semiconductor manufacturing via the CHIPS Act and the acceleration of aerospace exploration projects are primary growth drivers.
- Europe: A mature market focused on high-quality standards and environmental sustainability. Germany and Italy lead in the production of high-performance automotive components and industrial machinery using oxygen-free copper.
- Latin America: Growth is primarily driven by the mining sector in Chile and Peru, which are increasingly looking to move up the value chain by producing refined copper products locally.
- Middle East & Africa: Emerging demand from large-scale infrastructure projects and the expansion of the telecommunications network in GCC countries.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Oxygen Free Copper Market.
- Mitsubishi Materials Corporation
- Wieland-Werke AG
- Furukawa Electric Co., Ltd.
- KME Germany GmbH
- Aurubis AG
- Metrod Holdings Berhad
- Freeport-McMoRan Inc.
- Copperweld
- Sam Dong Co., Ltd.
- Luvata (Grouped under Mitsubishi Materials)
- Ningbo Jintian Copper (Group) Co., Ltd.
- Nexans
- Aviva Metals
- SH Copper Products Co., Ltd.
- Southwire Company, LLC
- Zhejiang Hailiang Co., Ltd.
- Oriental Copper Co., Ltd.
- Watteredge LLC
- Hussey Copper
- GBC Metals, LLC (Olin Brass)
Frequently Asked Questions
What is the difference between OF and OFE copper?
Oxygen Free (OF) copper (C10200) has a purity of at least 99.95%, while Oxygen Free Electronic (OFE) copper (C10100) has a higher purity of 99.99% and significantly lower levels of specific impurities like phosphorus and sulfur, making it ideal for vacuum and high-frequency applications.
Why is Oxygen Free Copper preferred for electric vehicles?
It offers the highest possible electrical conductivity (101% IACS or better) and superior thermal management, which reduces energy loss and heat generation in EV batteries and motor windings, thereby improving vehicle range and safety.
Which region is expected to lead the Oxygen Free Copper market growth?
While Asia-Pacific currently holds the largest market share, North America is expected to be the fastest-growing region due to intensive investments in local semiconductor fabrication and advanced defense technologies.
What are the main industrial applications of oxygen-free copper?
Key applications include high-end audio systems, semiconductor lead frames, vacuum interrupters, particle accelerators, MRI machines, and high-voltage power cables for offshore wind farms.
How does the price of oxygen-free copper compare to standard copper?
Oxygen-free copper commands a significant price premium (often 10-30% or more) due to the high-purity cathode requirements and the specialized vacuum induction melting or continuous casting processes used in its production.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
