Otoplasty Market
Otoplasty Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711801 | Published On : November 17, 2026 |
Format : 


 | Author : Erika Grotto
Otoplasty Market Size
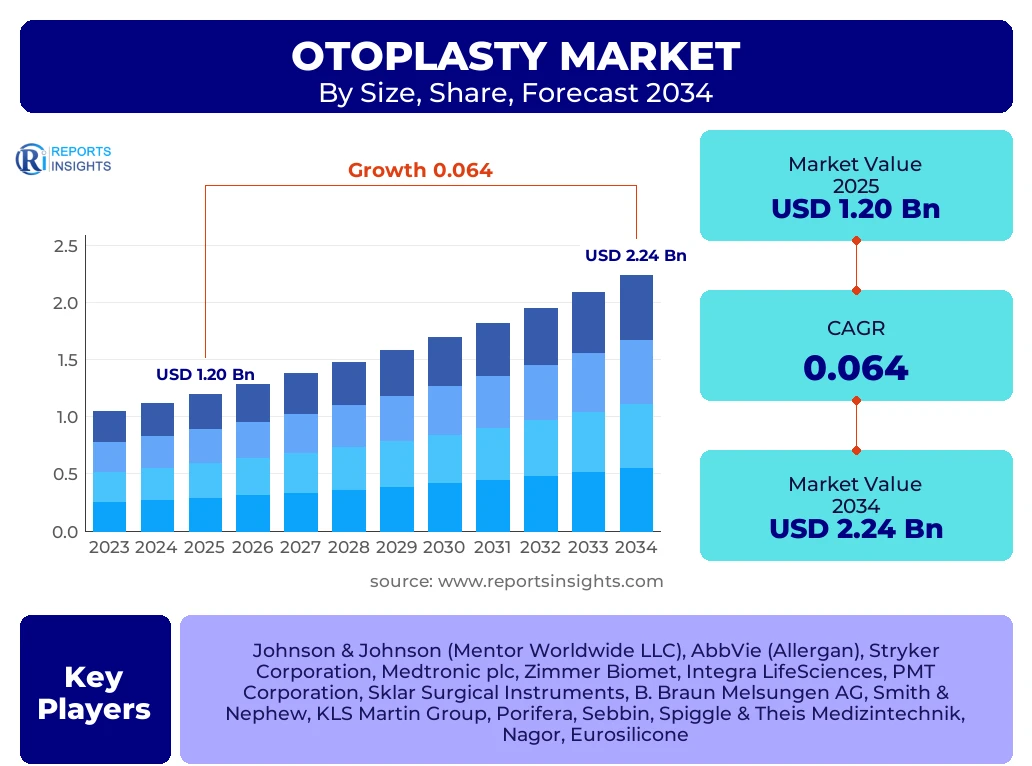
According to Reports Insights Consulting Pvt Ltd, The Otoplasty Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.4% between 2025 and 2034. The market is estimated at USD 1.28 Billion in 2026 and is projected to reach USD 2.24 Billion by the end of the forecast period in 2034.
Key Otoplasty Market Trends & Insights
The global otoplasty market is undergoing a significant transformation driven by advancements in minimally invasive surgical techniques and a burgeoning emphasis on aesthetic harmony. Stakeholders are increasingly focusing on patient-centric outcomes, particularly in the pediatric segment, where early intervention is sought to mitigate psychosocial challenges associated with ear prominence. Market intelligence suggests a shift toward the adoption of permanent implants, such as the Earfold system, which offers a less invasive alternative to traditional cartilage restructuring. Furthermore, the integration of 3D imaging and preoperative simulation tools is enhancing surgical precision, allowing clinicians to provide personalized structural blueprints for each patient. Competitive benchmarking reveals that market leaders are diversifying their portfolios to include both reconstructive and purely cosmetic solutions to capture a broader demographic across diverse socioeconomic strata.
- Largest Region: North America remains the dominant revenue generator, underpinned by high healthcare expenditure and a strong cultural acceptance of aesthetic procedures.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest growth rate due to rising disposable incomes and the expansion of medical tourism in countries like South Korea and Thailand.
- Largest Segment by Share: Ear Pinning (Pinnaplasty) accounts for the largest market share, driven by high demand among pediatric and adolescent populations.
- Technological Trend: Increasing utilization of 3D printing for the creation of customized ear scaffolds in reconstructive microtia cases.
Key Takeaways Otoplasty Market Size & Forecast
The Otoplasty market is characterized by a steady upward trajectory, supported by the convergence of clinical innovation and growing consumer awareness. Analyzing user inquiries highlights a strong focus on recovery timelines, procedural safety, and the long-term durability of surgical outcomes. As the market matures, the transition from traditional open surgeries to endoscopic-assisted otoplasty is becoming more pronounced. This evolution is expected to reduce postoperative complications and patient downtime, thereby attracting a larger volume of adult patients who were previously hesitant due to occupational commitments. Forecast models indicate that while the pediatric segment remains the cornerstone of the market, the adult cosmetic ear correction sub-segment will see incremental growth as societal stigmas surrounding plastic surgery continue to dissipate globally.
- Dominant Market Value: The market is set to cross the USD 2 billion threshold by the early 2030s, reflecting robust demand across both developed and emerging economies.
- Leading Country: The United States leads in total procedure volume, supported by a dense network of board-certified plastic surgeons and advanced clinical infrastructure.
- Crucial Growth Factor: The rising incidence of congenital ear deformities, such as microtia and anotia, is fueling the reconstructive side of the otoplasty market.
- Regulatory Influence: Stringent FDA and CE Mark regulations are ensuring high standards for surgical instruments and implantable materials, boosting patient confidence.
Otoplasty Market Drivers Analysis
The primary catalysts for the Otoplasty market include a heightened awareness of aesthetic procedures and the psychological impact of ear deformities on childhood development. Improved access to healthcare and the expansion of private insurance coverage for reconstructive cases have also played a pivotal role. The proliferation of digital media has normalized cosmetic enhancements, leading to an increase in self-referrals among young adults seeking to improve facial symmetry. Additionally, the development of specialized surgical kits and refined suture techniques has decreased the technical complexity of these procedures, allowing more surgeons to offer them as part of their standard practice.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in Minimally Invasive Techniques | +1.5% | Global | 2025 - 2034 |
| Rising Awareness of Pediatric Psychological Well-being | +1.2% | North America, Europe | 2025 - 2030 |
| Expansion of Medical Tourism | +0.9% | Asia-Pacific, Latin America | 2027 - 2034 |
Otoplasty Market Restraints Analysis
Despite the positive growth outlook, the market faces constraints such as the high cost of procedures when not covered by insurance. Otoplasty is often classified as an elective cosmetic surgery, which places the financial burden entirely on the patient. Furthermore, the potential for postoperative risks, including keloid scarring, hematoma, and asymmetry, acts as a deterrent for some individuals. The lack of standardized training for specialized ear reconstruction in certain developing regions also limits the availability of high-quality surgical interventions, thereby restricting market penetration in rural or underserved areas.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Out-of-Pocket Expenditure | -0.8% | Emerging Economies | 2025 - 2034 |
| Potential for Surgical Complications | -0.5% | Global | Short Term |
Otoplasty Market Opportunities Analysis
The integration of regenerative medicine and tissue engineering presents a frontier for growth in the otoplasty market. Research into lab-grown cartilage offers the potential to revolutionize reconstructive surgery, particularly for patients with severe congenital absence of the ear. There is also a significant opportunity for market players to develop non-surgical molding devices for infants, which can correct minor deformities without the need for future surgical intervention. Expanding into untapped markets in the Middle East and Africa, where there is a rising middle class, provides a fertile ground for market expansion and the establishment of specialized aesthetic centers.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Bio-engineered Cartilage Development | +1.8% | United States, Germany, Japan | 2028 - 2034 |
| Non-Surgical Neonatal Ear Correction | +1.1% | Global | 2025 - 2034 |
Otoplasty Market Challenges Impact Analysis
The market is challenged by the increasing popularity of alternative non-invasive cosmetic treatments that promise facial rejuvenation without surgery. Additionally, maintaining consistent quality and safety standards across a fragmented global landscape of private clinics is difficult. The global supply chain volatility also impacts the availability of high-grade surgical instruments and specialized sutures. Surgeons also face the challenge of managing patient expectations, as aesthetic outcomes are subjective and highly dependent on individual healing processes, which can lead to lower patient satisfaction rates if not addressed preoperatively.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Competition from Non-Surgical Aesthetics | -0.6% | Global | 2025 - 2034 |
| Supply Chain Disruptions for Specialized Tools | -0.4% | Global | Short to Medium Term |
Otoplasty Market - Updated Report Scope
The scope of this report encompasses a comprehensive analysis of the global otoplasty market, covering various procedure types, end-users, and patient demographics. It provides a detailed examination of the competitive landscape, focusing on technological innovations and strategic mergers that are shaping the industry. The report evaluates the market dynamics across six major regions, offering granular insights into country-level trends and regulatory frameworks that influence market access and growth.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.20 Billion |
| Market Forecast in 2034 | USD 2.24 Billion |
| Growth Rate | 6.4% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Johnson & Johnson (Mentor Worldwide LLC), AbbVie (Allergan), Stryker Corporation, Medtronic plc, Zimmer Biomet, Integra LifeSciences, PMT Corporation, Sklar Surgical Instruments, B. Braun Melsungen AG, Smith & Nephew, KLS Martin Group, Porifera, Sebbin, Spiggle & Theis Medizintechnik, Nagor, Eurosilicone |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The otoplasty market is segmented primarily by the nature of the procedure and the setting in which the surgery is performed. Ear pinning remains the most frequent intervention, largely due to the high volume of pediatric cases aimed at correcting prominent ears. Reconstructive otoplasty, while smaller in volume, is high in value due to the technical complexity and the need for specialized materials. Ambulatory surgery centers are gaining significant traction as the preferred end-user setting, offering a cost-effective and efficient alternative to traditional hospital-based surgeries for elective cosmetic procedures.
- By Procedure Type:
- Ear Pinning (Pinnaplasty): Most common procedure for correcting prominent ears.
- Ear Augmentation: Used for increasing the size of the pinna.
- Ear Reduction: Focusing on reducing the size of large ears (macrotia).
- Reconstructive Otoplasty: Complex procedures for congenital defects or trauma.
- By End-User:
- Specialty Clinics: Leading segment for cosmetic otoplasty.
- Hospitals: Primary setting for complex reconstructive cases.
- Ambulatory Surgery Centers: Rapidly growing due to lower costs and convenience.
- By Patient Group:
- Pediatric: Represents the majority of cases, typically performed after age 5.
- Adult: A growing segment seeking corrective surgery for long-standing aesthetic concerns.
Regional Highlights
- North America: Currently holds the largest market share, driven by a high concentration of skilled plastic surgeons and a culture that values aesthetic perfection. The United States is the primary contributor to this dominance.
- Asia-Pacific: Identified as the fastest-growing region. Rapid urbanization, increasing disposable income in China and India, and a booming medical tourism sector in South Korea are key growth drivers.
- Europe: Maintains a significant market share with a focus on reconstructive surgery. Countries like Germany and the UK are at the forefront of surgical innovation and clinical research.
- Latin America: Brazil is a major hub for aesthetic otoplasty, characterized by high demand and a well-established private healthcare sector for cosmetic procedures.
- Middle East & Africa: Experiencing gradual growth as healthcare infrastructure improves and international aesthetic clinic chains expand into the region.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Otoplasty Market.- Johnson & Johnson (Mentor Worldwide LLC)
- AbbVie (Allergan)
- Stryker Corporation
- Medtronic plc
- Zimmer Biomet
- Integra LifeSciences
- PMT Corporation
- Sklar Surgical Instruments
- B. Braun Melsungen AG
- Smith & Nephew
- KLS Martin Group
- Porifera
- Sebbin
- Spiggle & Theis Medizintechnik
- Nagor
- Eurosilicone
- Implantech
- Sientra, Inc.
- Matrix Medical
Frequently Asked Questions
What is the primary driver for the growth of the otoplasty market?
The primary driver is the increasing demand for pediatric ear correction to prevent bullying and psychological distress, combined with technological advancements in minimally invasive surgical techniques that offer shorter recovery times.
Which region is expected to witness the highest growth rate during the forecast period?
The Asia-Pacific region is expected to witness the highest growth rate due to rising healthcare expenditure, a growing middle class, and the popularity of aesthetic procedures in countries like South Korea, China, and Thailand.
What are the common procedures included in otoplasty?
The most common procedures include ear pinning (pinnaplasty) for prominent ears, ear reduction for macrotia, ear augmentation, and reconstructive surgery for congenital deformities like microtia.
Is otoplasty typically covered by medical insurance?
In most cases, cosmetic otoplasty is considered an elective procedure and is not covered by insurance. However, reconstructive otoplasty for congenital defects or trauma-related injuries is often partially or fully covered.
What is the impact of 3D printing on the otoplasty market?
3D printing is significantly impacting the market by allowing surgeons to create patient-specific ear scaffolds and models, which improves the precision of reconstructive surgeries and leads to more natural-looking results.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
