Non Injectable Insulin Market
Non Injectable Insulin Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711540 | Published On : November 05, 2026 |
Format : 


 | Author : Erika Grotto
Non Injectable Insulin Market Size
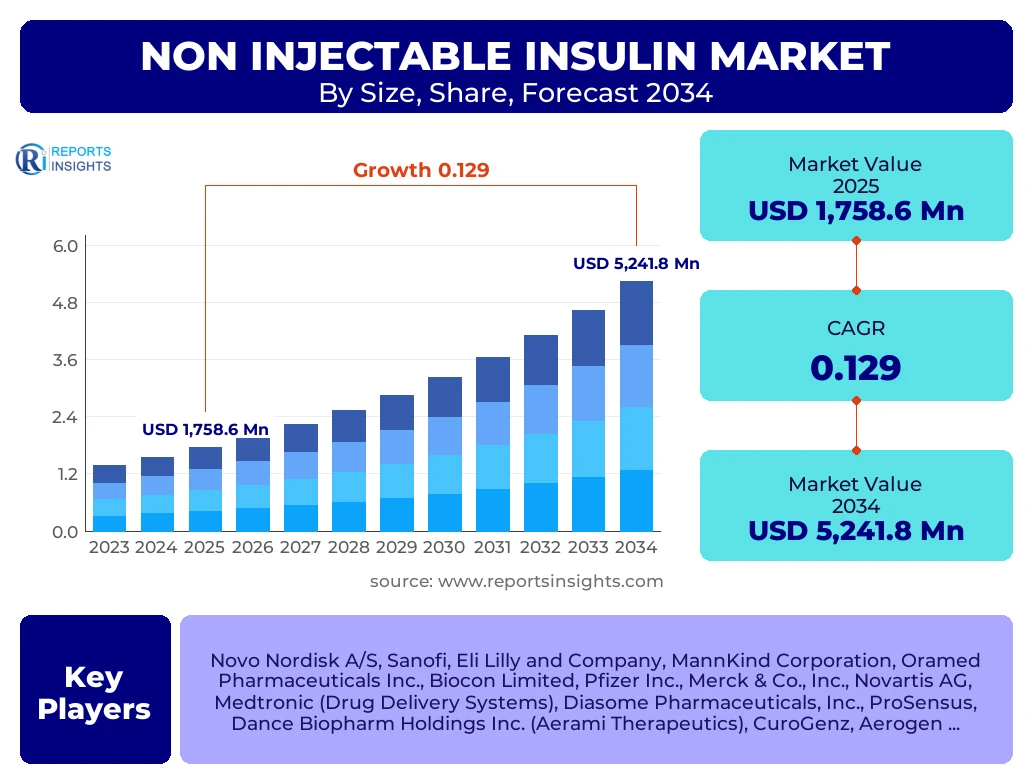
According to Reports Insights Consulting Pvt Ltd, The Non Injectable Insulin Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 12.9% between 2025 and 2034. The market is estimated at USD 1,985.4 Million in 2026 and is projected to reach USD 5,241.8 Million by the end of the forecast period in 2034.
Key Non Injectable Insulin Market Trends & Insights
The Non Injectable Insulin market is currently witnessing a transformative phase, driven by the escalating global prevalence of diabetes and a parallel demand for non-invasive therapeutic alternatives. Patients and healthcare providers are increasingly gravitating toward delivery systems that mitigate the psychological and physiological burdens associated with traditional subcutaneous injections. This shift is characterized by significant investments in biotechnology to overcome historical barriers such as low bioavailability and enzymatic degradation within the gastrointestinal tract. Furthermore, the integration of digital health technologies, such as smart inhalers and connected transdermal patches, is reshaping the competitive landscape, offering stakeholders a more data-centric approach to glucose management and patient adherence monitoring.
- North America currently stands as the largest regional market, bolstered by high healthcare expenditure and a robust pipeline of late-stage clinical trials for oral and inhaled insulin formulations.
- The Asia-Pacific region is identified as the fastest-growing market, primarily due to the massive diabetic populations in China and India and increasing government initiatives to modernize healthcare infrastructure.
- Oral Insulin represents the largest segment in terms of potential market share, as it mimics the physiological pathway of endogenous insulin through portal circulation, despite ongoing challenges in formulation stability.
- Inhaled insulin is gaining renewed traction following the refinement of delivery devices that offer more precise dosing and reduced pulmonary side effects compared to earlier-generation products.
Key Takeaways Non Injectable Insulin Market Size & Forecast
The long-term outlook for the Non Injectable Insulin market remains exceptionally bullish, with a double-digit CAGR reflecting the critical need for improved patient compliance. Market analysts observe that the transition from injectable to non-injectable formats is not merely a convenience upgrade but a clinical necessity for patients suffering from needle phobia or injection-site complications. As regulatory pathways become more defined and clinical data demonstrates non-inferiority to standard insulin glargine or lispro, the adoption rate is expected to accelerate significantly toward the middle of the forecast period. Strategic collaborations between pharmaceutical giants and specialized drug-delivery technology firms are the primary engines driving this forecasted growth.
- The United States leads the global market in value, driven by premium pricing models and a high concentration of key industry players focusing on inhaled delivery systems.
- China and India are emerging as critical hubs for the development of cost-effective oral insulin alternatives to address the massive burden of Type 2 diabetes in these regions.
- Technological advancements in mucoadhesive patches and nanoparticle-based delivery systems are expected to reach commercial maturity by 2028, further diversifying the market.
- Hospital pharmacies remain the dominant distribution channel, though online pharmacies are projected to exhibit the highest growth rate due to the increasing digitalization of chronic disease management.
Non Injectable Insulin Market Drivers Analysis
The primary catalyst for market expansion is the urgent clinical requirement to improve patient adherence in diabetes management. Studies indicate that a significant percentage of patients delay the initiation of insulin therapy due to the fear of needles, leading to poor glycemic control and long-term complications. Non-injectable formats address this barrier directly, potentially reducing the overall burden on global healthcare systems by preventing costly diabetic emergencies. Additionally, the pharmacological advantage of oral insulin, which travels directly to the liver via the portal vein, offers a more natural metabolic profile than peripheral injections.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Advancements in Nanoparticle Drug Delivery | +3.2% | Global | 2025 - 2030 |
| Rising Prevalence of Needle Phobia (Belonephobia) | +2.8% | North America and Europe | 2025 - 2034 |
| Favorable Reimbursement Policies for Non-Invasive Tech | +2.5% | USA, Germany, UK | 2027 - 2034 |
| Increase in Geriatric Diabetic Population | +2.1% | Japan and Western Europe | 2025 - 2034 |
Non Injectable Insulin Market Restraints Analysis
Despite the immense potential, the market faces stringent hurdles related to the biological stability of insulin molecules. The harsh environment of the human digestive system remains a significant deterrent for oral insulin, necessitating complex and expensive encapsulation technologies to prevent premature degradation. Moreover, the high cost of research and development, coupled with the risk of late-stage clinical trial failures, poses a financial risk to smaller biotech firms. Regulatory agencies, including the FDA and EMA, maintain rigorous safety standards regarding pulmonary health for inhaled versions, which can extend the timeline for product commercialization.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Regulatory Approval Processes | -2.4% | United States and EU | 2025 - 2029 |
| High Production and Manufacturing Costs | -1.9% | Global | 2025 - 2034 |
| Concerns Over Long-term Pulmonary Safety | -1.5% | Global (Inhaled Segment) | 2026 - 2032 |
Non Injectable Insulin Market Opportunities Analysis
The integration of "Smart" technologies presents a frontier of opportunity for the Non Injectable Insulin market. Developing delivery devices that can sync with Continuous Glucose Monitors (CGM) via smartphone applications allows for precise, automated dosing, effectively creating a non-invasive artificial pancreas system. Furthermore, emerging economies in Latin America and the Middle East represent untapped territories where the increasing incidence of metabolic disorders creates a high-demand environment for modern therapeutic solutions. Expanding the application of these delivery technologies to pediatric populations, where needle aversion is most prevalent, also offers a significant growth pathway.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration with AI and Connected Health Platforms | +4.1% | North America, APAC | 2026 - 2034 |
| Expansion into Pediatric Diabetes Care | +3.3% | Global | 2027 - 2034 |
| Growth of E-commerce Distribution Channels | +1.8% | India, China, Brazil | 2025 - 2034 |
Non Injectable Insulin Market Challenges Impact Analysis
Maintaining dosage precision remains a critical challenge, as non-injectable routes often suffer from higher variability in absorption rates compared to subcutaneous injections. Factors such as a patient's lung health (for inhaled insulin) or recent food intake (for oral insulin) can significantly alter the pharmacokinetic profile, complicating glycemic management. Additionally, the competitive pricing of generic injectable insulin makes it difficult for premium-priced non-injectable alternatives to gain immediate mass-market penetration, particularly in cost-sensitive developing nations.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Inter-patient Variability in Absorption | -2.2% | Global | 2025 - 2034 |
| Competition from Low-Cost Biosimilar Injectables | -2.0% | India, Latin America | 2025 - 2030 |
| Technical Complexity in Large-scale Manufacturing | -1.3% | Global | 2026 - 2031 |
Non Injectable Insulin Market - Updated Report Scope
This comprehensive report provides a deep-dive analysis of the global Non Injectable Insulin market, spanning historical data from 2020 to 2024 and delivering detailed forecasts through 2034. The scope encompasses an evaluation of various delivery technologies including oral, inhaled, transdermal, and nasal routes, alongside an assessment of their efficacy in treating Type 1 and Type 2 diabetes. The report also highlights the strategic moves of key players and the impact of technological convergence on market dynamics.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1,758.6 Million |
| Market Forecast in 2034 | USD 5,241.8 Million |
| Growth Rate | 12.9% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Novo Nordisk A/S, Sanofi, Eli Lilly and Company, MannKind Corporation, Oramed Pharmaceuticals Inc., Biocon Limited, Pfizer Inc., Merck & Co., Inc., Novartis AG, Medtronic (Drug Delivery Systems), Diasome Pharmaceuticals, Inc., ProSensus, Dance Biopharm Holdings Inc. (Aerami Therapeutics), CuroGenz, Aerogen, and Emisphere Technologies (acquired by Novo Nordisk). |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Non Injectable Insulin market is segmented based on the mode of delivery, which is the most critical factor determining patient adoption and clinical efficacy. The Oral segment is currently seeing the highest volume of research, aiming to utilize protein engineering and protective coatings to survive gastric acidity. Inhalation follows closely, already having commercial products on the market that cater to mealtime glucose control. The application-based segmentation highlights Type 2 diabetes as the primary revenue generator due to the sheer volume of patients and the progressive nature of the disease, which eventually requires insulin supplementation.
- By Delivery Mode:
- Oral Insulin (Capsules and Liquids)
- Inhaled Insulin (Dry Powder Inhalers)
- Transdermal Insulin (Active and Passive Patches)
- Nasal and Buccal Sprays
- By Application:
- Type 1 Diabetes (Autoimmune insulin deficiency)
- Type 2 Diabetes (Insulin resistance and progressive deficiency)
- By Distribution Channel:
- Hospital Pharmacies (Inpatient and outpatient care)
- Retail Pharmacies (Brick-and-mortar stores)
- Online Pharmacies (Digital health and direct-to-consumer)
Regional Highlights
The regional distribution of the Non Injectable Insulin market reveals a landscape where economic maturity and disease prevalence dictate growth patterns. North America, specifically the United States, continues to be the primary engine for innovation and high-value consumption. The presence of advanced healthcare infrastructure and significant insurance coverage for novel therapies supports the early adoption of high-cost non-injectable delivery systems. Europe maintains a strong secondary position, with countries like Germany and France providing robust regulatory support for pharmaceutical innovation and comprehensive diabetes care programs.
- North America: The largest market share holder, driven by aggressive R&D investments and a high prevalence of lifestyle-related Type 2 diabetes.
- Asia-Pacific: The fastest-growing region, where the rapid rise of the middle class in China and India is leading to increased demand for convenient, non-invasive chronic disease management.
- Europe: A mature market focused on patient-centric care and the integration of digital health with traditional insulin therapies.
- Latin America: Expected to show steady growth as medical infrastructure improves in nations like Brazil and Mexico, making advanced therapies more accessible.
- Middle East & Africa: A region with some of the highest diabetes prevalence rates in the world, representing a significant long-term opportunity for non-injectable alternatives.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Non Injectable Insulin Market.- Novo Nordisk A/S
- Sanofi
- Eli Lilly and Company
- MannKind Corporation
- Oramed Pharmaceuticals Inc.
- Biocon Limited
- Pfizer Inc.
- Merck & Co., Inc.
- Novartis AG
- Medtronic
- Diasome Pharmaceuticals, Inc.
- Aerami Therapeutics
- CuroGenz
- Aerogen
- Emisphere Technologies
- Wockhardt
- Julphar (Gulf Pharmaceutical Industries)
- Generex Biotechnology
Frequently Asked Questions
What is the current state of Oral Insulin development?
Oral insulin is currently in various stages of clinical trials, with several companies utilizing nanoparticle technology and pH-sensitive coatings to ensure the insulin survives the stomach's acidic environment. While commercial availability is limited, it is considered the "holy grail" of diabetes treatment due to its potential for high patient compliance and physiological mimicry of natural insulin release.
How does Inhaled Insulin compare to traditional injections?
Inhaled insulin, such as dry powder formulations, provides a rapid onset of action, making it ideal for managing mealtime glucose spikes. While it eliminates the need for needles during meals, many patients still require a long-acting injectable insulin for basal coverage, and regular lung function tests are necessary for users.
Which region is expected to lead the Non Injectable Insulin market growth?
The Asia-Pacific region is projected to experience the highest growth rate (CAGR) during the forecast period. This is attributed to the massive increase in diabetes cases, improving healthcare accessibility, and a growing emphasis on non-invasive medical solutions in major economies like China and India.
What are the main challenges facing Transdermal Insulin patches?
The primary challenges for insulin patches include the large molecular size of insulin, which makes it difficult to permeate the skin naturally. Research is focusing on "active" patches that use micro-needles or ultrasonic waves to facilitate delivery, though these must overcome concerns regarding skin irritation and dosing consistency.
What role does Digital Health play in this market?
Digital health is a major trend, where non-injectable delivery devices are being equipped with sensors and Bluetooth connectivity. This allows for real-time tracking of doses and integration with glucose monitoring apps, providing a more comprehensive ecosystem for diabetes management and improving clinical outcomes.
Author
E
Pharmaceuticals And Healthcare
Erika Grotto is a Senior Analyst Pharmaceuticals and Healthcare Research with over 8+ years of experience in the Pharmaceuticals and Healthcare Industry. She possesses expertise in pharmaceutical market intelligence, clinical pipeline analysis, healthcare demand forecasting, competitive benchmarking, regulatory landscape assessment, drug commercialization strategy, market access evaluation, and therapeutic area analysis. By combining in-depth industry knowledge with robust data analysis, she delivers actionable insights that help organizations make strategic business decisions, identify high-growth opportunities, optimize commercial strategies, anticipate healthcare market trends, and enhance their competitive positioning across global pharmaceutical and healthcare markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
