Multi Cloud Management Market
Multi Cloud Management Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711411 | Published On : October 31, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Multi Cloud Management Market Size
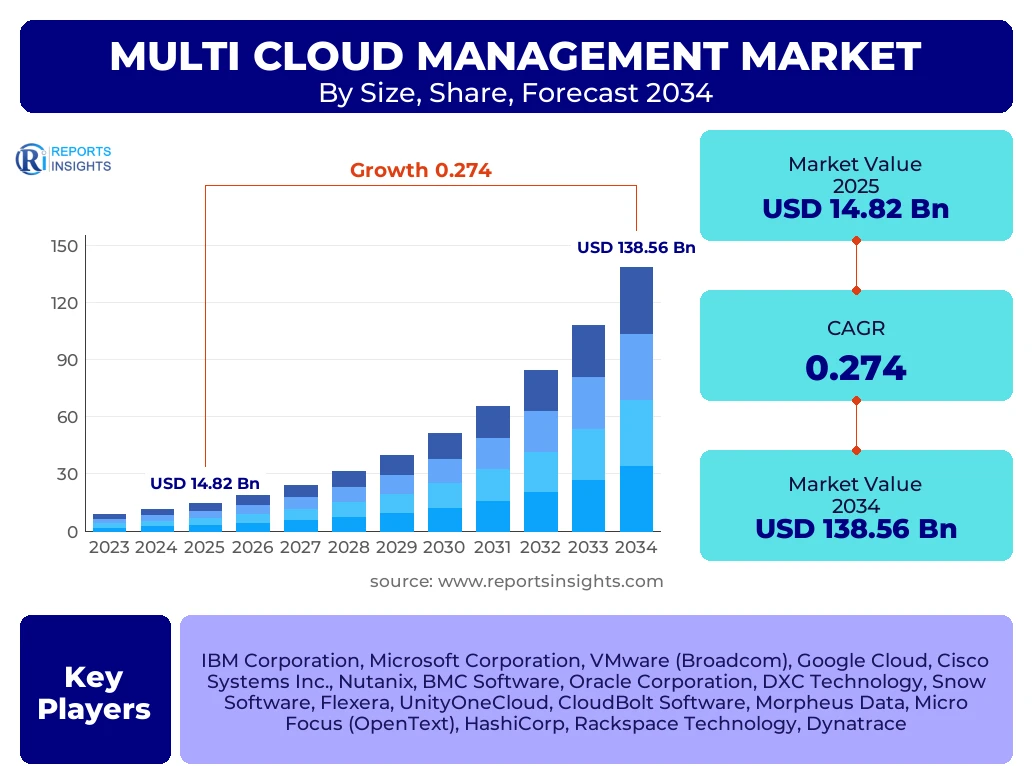
According to Reports Insights Consulting Pvt Ltd, The Multi Cloud Management Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 27.4% between 2025 and 2034. The market is estimated at USD 18.88 Billion in 2026 and is projected to reach USD 138.56 Billion by the end of the forecast period in 2034.
Key Multi Cloud Management Market Trends & Insights
The global shift toward decentralized IT infrastructure has positioned multi-cloud management as a foundational requirement for modern enterprises. Organizations are increasingly moving away from single-vendor reliance to mitigate the risks of vendor lock-in and to capitalize on the specialized services offered by different hyperscalers like AWS, Azure, and Google Cloud. This evolution is driven by the need for operational resilience, where a multi-cloud strategy serves as a robust disaster recovery framework. Furthermore, the integration of Artificial Intelligence for IT Operations (AIOps) is transforming how these environments are managed, enabling automated scaling, predictive anomaly detection, and intelligent cost allocation across disparate platforms.
Regional insights indicate that while North America remains the dominant revenue generator due to early adoption of cloud-native technologies, the Asia-Pacific region is experiencing the highest growth trajectory. This is fueled by rapid digital transformation initiatives in India, China, and Southeast Asia. From a segmental perspective, the solutions segment, particularly those focusing on security and governance, continues to hold the largest market share as regulatory pressures like GDPR and CCPA necessitate stringent cross-cloud compliance monitoring. The rise of sovereign clouds in Europe is also a significant trend, pushing management providers to offer more localized and data-resident control mechanisms.
- Largest Region: North America remains the leading contributor to market revenue, accounting for over 38% of the global share, driven by a high concentration of enterprise-level technology firms and advanced cloud infrastructure.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR during the forecast period, supported by massive investments in data center infrastructure and government-led digital economy programs.
- Leading Segment by Component: The Solutions segment dominates the market, specifically platforms that provide unified visibility and automated provisioning across public and private clouds.
- Leading Segment by Deployment: Hybrid Cloud deployment models are seeing the highest adoption rates as enterprises seek to balance the security of on-premises hardware with the scalability of public cloud services.
- Emerging Trend: FinOps integration has become a critical priority, with businesses utilizing multi-cloud management tools to curb "cloud sprawl" and optimize high-intensity compute costs.
Key Takeaways Multi Cloud Management Market Size & Forecast
The multi-cloud management market is entering a phase of hyper-growth characterized by the convergence of automation, security, and cost-efficiency. As businesses scale their digital footprints, the complexity of managing multiple interfaces and billing cycles has made centralized management platforms indispensable. The forecast suggests a significant move toward "Cloud-Agnostic" architectures, where applications can be moved seamlessly between providers without significant refactoring. This flexibility is expected to be a primary driver for the projected 27.4% CAGR through 2034.
- Exponential Market Expansion: The leap from USD 18.88 Billion in 2026 to over USD 138 Billion by 2034 reflects a fundamental shift in corporate IT spending toward managed abstraction layers.
- US Market Dominance: The United States continues to be the primary hub for innovation and adoption, with US-based enterprises leading in the implementation of advanced multi-cloud governance frameworks.
- SME Adoption: Small and Medium Enterprises are increasingly adopting cloud management tools through SaaS models, seeking to compete with larger players by utilizing high-end cloud capabilities without massive upfront capital expenditure.
- Vertical Growth in BFSI: The Banking, Financial Services, and Insurance (BFSI) sector is the leading vertical adopter, driven by the necessity for high availability and strict data sovereignty across multiple geographic jurisdictions.
- Strategic Focus on Security: Managed Security Service Providers (MSSPs) are integrating multi-cloud management into their core offerings, highlighting the critical nature of unified threat detection in fragmented environments.
Multi Cloud Management Market Drivers Analysis
The primary driver for the multi-cloud management market is the urgent corporate need to eliminate vendor lock-in. By distributing workloads across multiple providers, companies gain significant bargaining power and the ability to choose the best-of-breed services for specific tasks, such as using one provider for AI/ML capabilities and another for cost-efficient storage. Additionally, the proliferation of data sovereignty laws globally requires enterprises to maintain data in specific regions, a feat only achievable through a coordinated multi-cloud approach that these management platforms facilitate.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Mitigation of Vendor Lock-in | +6.5% | Global | 2025 - 2034 |
| Demand for Cost Optimization (FinOps) | +5.8% | North America & Europe | 2025 - 2030 |
| Rise of Hybrid Work Environments | +4.2% | Global | 2025 - 2028 |
| Data Sovereignty and Compliance Needs | +5.4% | European Union, China, India | 2026 - 2034 |
| AIOps and Automation Integration | +5.5% | Developed Economies | 2027 - 2034 |
Multi Cloud Management Market Restraints Analysis
Despite the robust growth, the market faces significant headwinds due to the inherent complexity of integrating disparate cloud architectures. The lack of a standardized API across different cloud service providers (CSPs) often leads to integration "friction," requiring highly specialized talent that is currently in short supply. Security also remains a paradoxical restraint; while multi-cloud improves resilience, it expands the attack surface, leading to concerns regarding identity and access management (IAM) consistency across various platforms.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Skill Gap and Talent Shortage | -3.2% | Global | 2025 - 2030 |
| Interoperability Challenges | -2.8% | Global | 2025 - 2034 |
| High Initial Implementation Costs | -2.1% | Emerging Markets | 2025 - 2029 |
Multi Cloud Management Market Opportunities Analysis
The emergence of Edge Computing presents a massive opportunity for multi-cloud management providers. As data processing moves closer to the source (IoT devices, autonomous vehicles), the need to manage edge nodes in conjunction with centralized cloud clusters becomes paramount. Furthermore, there is a burgeoning market for industry-specific cloud management solutions tailored for highly regulated sectors like Healthcare and Energy, where compliance-as-code can be integrated directly into the management platform.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expansion into Edge Computing Management | +7.2% | Global | 2026 - 2034 |
| Industry-Specific Compliance Platforms | +4.9% | Europe & North America | 2025 - 2034 |
| SME Focused SaaS Solutions | +3.8% | APAC & Latin America | 2026 - 2032 |
Multi Cloud Management Market Challenges Impact Analysis
The primary challenge remains the constant evolution of hyperscaler services, which forces management platform providers to continuously update their tools to remain compatible. This "feature race" can lead to technical debt and stability issues within management suites. Additionally, the lack of unified governance across different cloud types (public vs. private) often results in "shadow IT," where departments spin up resources outside the monitored management framework, undermining the very purpose of these platforms.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shadow IT and Governance Silos | -2.5% | Large Enterprises | 2025 - 2034 |
| Hyperscaler API Volatility | -1.9% | Global | 2025 - 2030 |
Multi Cloud Management Market - Updated Report Scope
This report provides a granular analysis of the global multi-cloud management ecosystem, covering technical architectures, financial optimization tools, and governance frameworks. It assesses the transition from traditional infrastructure management to cloud-agnostic, container-driven operations. The scope includes an in-depth evaluation of the competitive landscape, identifying key players who are shaping the future of automated workload distribution and cross-cloud security.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 14.82 Billion |
| Market Forecast in 2034 | USD 138.56 Billion |
| Growth Rate | 27.4% CAGR |
| Number of Pages | 264 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | IBM Corporation, Microsoft Corporation, VMware (Broadcom), Google Cloud, Cisco Systems Inc., Nutanix, BMC Software, Oracle Corporation, DXC Technology, Snow Software, Flexera, UnityOneCloud, CloudBolt Software, Morpheus Data, Micro Focus (OpenText), HashiCorp, Rackspace Technology, Dynatrace |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The multi-cloud management market is segmented to reflect the diverse needs of modern IT departments. The Solutions segment is the most significant, as it addresses the core technical requirements of orchestration and provisioning. Within this, Cost Management tools are seeing a surge in demand as companies prioritize ROI on their cloud investments. The Services segment is also growing rapidly, particularly managed services, as companies outsource the complexity of multi-cloud operations to specialized third-party providers.
- By Component:
- Solutions: Integrated platforms for provisioning, lifecycle management, and performance monitoring.
- Services: Strategic consulting, implementation, and ongoing managed support.
- By Deployment Model:
- Hybrid Cloud: Combining the privacy of on-premises with the agility of public clouds; currently the largest deployment segment.
- Public Cloud: Multi-cloud strategies utilizing two or more public providers like AWS and Azure.
- Private Cloud: Management of multiple private instances across different geographic data centers.
- By Vertical:
- BFSI: Highest security and compliance requirements.
- IT & Telecom: Early adopters focused on service delivery and latency.
- Healthcare: Increasing use for managing patient data across secure, distributed nodes.
- Retail: Utilizing multi-cloud to manage seasonal spikes in e-commerce traffic.
Regional Highlights
- North America: The largest market share holder, dominated by the United States. High adoption of advanced technologies like AI and serverless computing drives the demand for comprehensive management tools.
- Asia-Pacific: The fastest-growing region, with India and China at the forefront. The shift toward digital-first economies and massive infrastructure investments make this a key strategic region for cloud providers.
- Europe: Focused heavily on data privacy and sovereignty. The implementation of the GAIA-X project and strict GDPR compliance are steering the market toward management solutions that offer granular data control.
- Middle East & Africa: Growing at a steady pace as major CSPs open data centers in the UAE and Saudi Arabia, encouraging local businesses to adopt multi-cloud strategies.
- Latin America: Emerging market with increasing cloud spend in Brazil and Mexico, primarily driven by the modernization of the banking and retail sectors.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Multi Cloud Management Market.- IBM Corporation
- Microsoft Corporation
- VMware (Broadcom)
- Google Cloud
- Cisco Systems Inc.
- Nutanix
- BMC Software
- Oracle Corporation
- DXC Technology
- Snow Software
- Flexera
- UnityOneCloud
- CloudBolt Software
- Morpheus Data
- Micro Focus (OpenText)
- HashiCorp
- Rackspace Technology
- Dynatrace
- Apptio
- Turbonomic
Frequently Asked Questions
What is the primary driver of the Multi Cloud Management Market growth?
The primary driver is the enterprise-wide transition toward a multi-cloud strategy to avoid vendor lock-in and enhance operational resilience. By utilizing multiple cloud providers, organizations can optimize costs, improve disaster recovery capabilities, and leverage specialized services from different hyperscalers, necessitating a unified management platform to oversee these complex environments.
Which region is expected to witness the highest growth rate through 2034?
The Asia-Pacific region is projected to experience the highest CAGR. This growth is fueled by rapid digitalization, significant government investments in cloud infrastructure, and the expansion of major cloud service providers into markets like India, China, and Southeast Asia.
How does FinOps relate to the Multi Cloud Management Market?
FinOps is an integral part of multi-cloud management that focuses on bringing financial accountability to the variable spend of cloud computing. Multi-cloud management platforms provide the visibility and automated tools necessary for FinOps teams to track spending across different providers, eliminate waste, and optimize costs in real-time.
What are the main challenges in implementing a multi-cloud management strategy?
The main challenges include the complexity of integrating different cloud architectures, a significant shortage of skilled cloud architects, and concerns regarding consistent security and compliance across disparate platforms. Interoperability issues due to varying API standards among providers also present a major hurdle.
What role does AI play in Multi Cloud Management?
AI, through AIOps, is used to automate routine management tasks, predict potential outages, and optimize workload distribution. AI algorithms can analyze vast amounts of performance data across multiple clouds to provide actionable insights that human operators might miss, significantly improving efficiency and uptime.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
