Micro Led Market
Micro Led Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_707005 | Published On : September 28, 2026 |
Format : 


 | Author : Shamin Verma
Micro Led Market Size
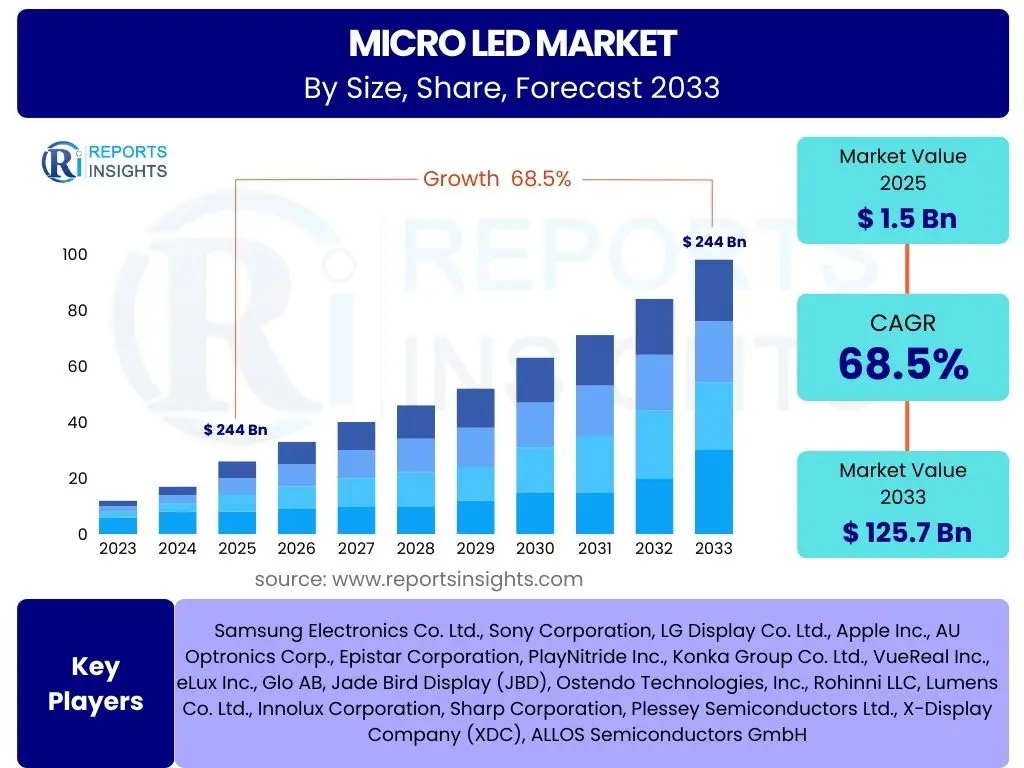
According to Reports Insights Consulting Pvt Ltd, The Micro Led Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 78.4% between 2026 and 2034. The market is estimated at USD 3.25 Billion in 2026 and is projected to reach USD 385.4 Billion by the end of the forecast period in 2034.
Key Micro Led Market Trends & Insights
The Micro LED market is currently navigating a pivotal transition from research and development to large-scale commercialization, driven by the demand for next-generation display technologies that surpass the limitations of OLED and LCD. Industry stakeholders are increasingly focusing on the integration of Micro LED technology into high-performance devices, particularly within the augmented reality (AR) and virtual reality (VR) sectors, where high brightness and rapid response times are critical. Regional insights indicate a concentrated effort in the Asia-Pacific region to dominate the manufacturing supply chain, while North American players are leading in software and application-specific integrated circuit (ASIC) development. Current benchmarking reveals that while manufacturing yields remain a challenge, the adoption of laser-based mass transfer processes is significantly reducing production time and costs, positioning Micro LED as the premier choice for premium consumer electronics.
- Largest Region: Asia-Pacific, driven by massive investments from South Korean and Chinese display manufacturers.
- Fastest Growing Region: North America, attributed to the rapid adoption of Micro LED in wearable medical devices and AR/VR technologies.
- Largest Segment by Share: Consumer Electronics, specifically high-end smartwatches and premium large-format televisions.
- Leading Application: Smartwatches and Wearables, which benefit most from the energy efficiency and high-pixel-density characteristics of Micro LED.
Key Takeaways Micro Led Market Size & Forecast
The global forecast for the Micro LED market underscores a period of exponential growth, fueled by the convergence of telecommunications advancements (6G) and the miniaturization of display components. As manufacturers overcome the technical hurdles of mass transfer and inspection, the market is expected to witness a significant shift in price-performance ratios, making the technology accessible beyond the luxury segment. Analysis suggests that the integration of Micro LED into automotive head-up displays (HUDs) and transparent windows will be a primary revenue generator toward the latter half of the forecast period, reflecting a broader trend toward ambient and interactive computing environments.
- Dominant Country: South Korea remains the technological leader due to the presence of industry giants focusing on large-scale Micro LED TV commercialization.
- Strategic Growth Driver: The shift toward 8K resolution and beyond is necessitating the use of Micro LED due to its ability to maintain brightness at high pixel densities.
- Investment Focus: Heavy venture capital and corporate investment are flowing into mass transfer startups to solve the bottleneck of moving millions of microscopic LEDs onto backplanes.
- Sustainability Impact: Micro LED displays offer up to 50 percent more energy efficiency than current OLED panels, aligning with global green energy initiatives for consumer hardware.
Micro Led Market Drivers Analysis
The growth of the Micro LED market is primarily propelled by the insatiable demand for high-performance displays in consumer electronics and the automotive sector. Unlike traditional display technologies, Micro LED offers inorganic longevity, exceptional brightness, and near-instantaneous response times, making it the ideal candidate for outdoor visibility and immersive digital experiences. Additionally, the proliferation of smart wearable devices that require long battery life and compact form factors is accelerating the adoption of Micro LED backlighting and direct-view solutions.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Surge in Demand for AR/VR Devices | +18.5% | United States, Japan | 2025 - 2030 |
| Automotive Integration (HUDs & Dashboards) | +12.2% | Germany, South Korea | 2027 - 2034 |
| Energy Efficiency Standards in Electronics | +9.8% | European Union, Global | 2025 - 2034 |
Micro Led Market Restraints Analysis
Despite its superior performance, the Micro LED market faces significant restraints related to manufacturing complexity and cost. The process of transferring millions of micrometer-sized LEDs from the growth wafer to the display backplane with 99.9999% precision remains a technical bottleneck. High initial capital expenditure for cleanroom equipment and the lack of a standardized manufacturing ecosystem further inhibit rapid market penetration in the mid-range consumer segment.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Production Costs & Low Yield Rates | -15.4% | Global | 2025 - 2028 |
| Technical Complexity of Mass Transfer | -10.2% | Taiwan, China | 2025 - 2029 |
Micro Led Market Opportunities Analysis
The Micro LED market presents immense opportunities in the field of transparent displays and flexible electronics. Because Micro LED chips are microscopic, they can be spaced to allow light to pass through the substrate, enabling the creation of smart windows for retail and automotive applications. Furthermore, the development of monolithically integrated Micro LEDs on CMOS backplanes opens new avenues for compact projectors and high-resolution spatial computing hardware.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Transparent Display Commercialization | +14.5% | China, South Korea | 2028 - 2034 |
| Medical Imaging & Surgical Displays | +7.3% | North America, Europe | 2026 - 2032 |
| Miniaturized Projection for Smart Glasses | +11.2% | United States, Japan | 2025 - 2034 |
Micro Led Market Challenges Impact Analysis
Critical challenges facing the industry include the need for advanced inspection and repair technologies. If a single Micro LED fails during the transfer process, it can result in a dead pixel, which is unacceptable for premium displays. Developing cost-effective, high-speed testing methods at the wafer level and during the final assembly is essential for achieving the yields necessary for mass-market adoption.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Standardization of Testing Protocols | -8.5% | Global | 2025 - 2027 |
| Competition from Advanced OLED (QD-OLED) | -6.8% | South Korea, Japan | 2025 - 2030 |
Micro Led Market - Updated Report Scope
This report provides a comprehensive analysis of the Micro LED market, encompassing technological advancements, manufacturing trends, and competitive dynamics. The scope includes a detailed breakdown of the value chain, from epitaxial wafer growth and chip fabrication to mass transfer and final module assembly. By analyzing both the supply and demand sides, this report offers strategic insights into the adoption rates across various industry verticals including consumer electronics, automotive, and industrial applications.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.82 Billion |
| Market Forecast in 2034 | USD 385.4 Billion |
| Growth Rate | 78.4% CAGR |
| Number of Pages | 256 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Samsung Electronics Co., Ltd., Sony Group Corporation, LG Display Co., Ltd., Apple Inc., Epistar Corporation, San'an Optoelectronics, Osram Licht AG, PlayNitride Inc., Seoul Semiconductor Co., Ltd., Lumens Co., Ltd., VueReal, Plessey Semiconductors, Jade Bird Display (JBD), Rohinni LLC, Aledia, eLUX Inc., Ostendo Technologies, Inc., X-Display Company (XDC), Sundiode Inc. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Micro LED market is segmented based on application, display size, and industry vertical, reflecting the diverse utility of this technology. The display segment is currently the most significant revenue contributor, with micro-displays for AR/VR and small-format displays for wearables leading the initial commercial rollout. As manufacturing efficiencies improve, the large-format display segment, particularly for premium home cinema and digital signage, is expected to experience the highest growth rate due to the scalability of Micro LED modules.
- By Application:
- Display: The primary segment, including Smartwatches, Televisions, and AR/VR headsets.
- Lighting: Specialized applications in automotive adaptive driving beams and high-intensity industrial lighting.
- By Display Size:
- Small-scale Displays (<2 inches): Driven by the wearable and near-eye display market.
- Medium-scale Displays (2 to 10 inches): Targeting automotive dashboards and tablets.
- Large-scale Displays (>10 inches): Focused on ultra-premium TVs and commercial video walls.
- By Industry Vertical:
- Consumer Electronics: Largest vertical, utilizing Micro LED for superior visual fidelity.
- Automotive: Growing demand for high-brightness HUDs and exterior lighting.
- Retail & Advertising: Implementation of transparent and high-impact digital signage.
- Aerospace & Defense: High-reliability cockpit displays and ruggedized tactical gear.
Regional Highlights
- Asia-Pacific: This region dominates the market share, holding approximately 55% of the total value. Countries like South Korea, Taiwan, and China are home to the world's leading display manufacturers and LED foundries. Massive government subsidies and an established electronics supply chain facilitate rapid R&D and scaling.
- North America: Identified as the fastest-growing region, North America is a hub for Micro LED innovation in the AR/VR and medical sectors. The presence of major tech giants developing proprietary Micro LED solutions for next-gen consumer hardware accelerates regional CAGR.
- Europe: Europe maintains a strong focus on automotive applications. German and French automotive manufacturers are integrating Micro LED technology for smart lighting and advanced interior displays, emphasizing safety and luxury.
- Middle East and Africa: Growth is primarily seen in high-end retail and luxury real estate developments where Micro LED video walls are used for immersive advertising and architectural integration.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Micro Led Market.- Samsung Electronics Co., Ltd.
- Sony Group Corporation
- LG Display Co., Ltd.
- Apple Inc.
- Epistar Corporation (Ennostar Inc.)
- San'an Optoelectronics
- Osram Licht AG
- PlayNitride Inc.
- Seoul Semiconductor Co., Ltd.
- Lumens Co., Ltd.
- VueReal
- Plessey Semiconductors
- Jade Bird Display (JBD)
- Rohinni LLC
- Aledia
- eLUX Inc.
- Ostendo Technologies, Inc.
- X-Display Company (XDC)
- Sundiode Inc.
- Konka Group Co., Ltd.
Frequently Asked Questions
What is the main advantage of Micro LED over OLED?
Micro LED offers significantly higher brightness, longer lifespan due to its inorganic nature (no burn-in), and better energy efficiency compared to OLED. It also provides faster response times and higher pixel density, which are crucial for AR/VR applications.
Which industry vertical will see the fastest Micro LED adoption?
The Consumer Electronics vertical, particularly in the wearable devices segment like smartwatches, will see the fastest adoption due to the immediate benefits of sunlight readability and extended battery life provided by Micro LED technology.
Why are Micro LED displays currently so expensive?
The high cost is primarily due to the manufacturing challenges associated with "Mass Transfer," where millions of tiny LEDs must be moved onto a backplane with extreme precision. Low yield rates and the high cost of cleanroom production also contribute to the premium pricing.
What is the role of the Asia-Pacific region in the Micro LED market?
Asia-Pacific is the manufacturing powerhouse of the Micro LED market. It leads in terms of production capacity, supply chain infrastructure, and investment in LED epitaxy and display panel assembly, spearheaded by companies in South Korea, Taiwan, and China.
How does Micro LED technology impact the automotive sector?
In the automotive sector, Micro LED is revolutionizing Head-Up Displays (HUDs) by providing high contrast and brightness that remains visible in direct sunlight. It is also being used for smart adaptive headlights and transparent window displays for autonomous vehicles.
Author
S
Shamin Verma is a Senior Analyst Semiconductor and Electronics Research with over 7+ years of experience in the Semiconductor and Electronics Industry. She specializes in semiconductor market intelligence, electronics supply chain analysis, wafer fabrication trends, competitive benchmarking, demand forecasting, component pricing analysis, emerging technology assessment, integrated circuit market evaluation, and industry ecosystem research. Her expertise in translating complex market data into strategic insights enables organizations to make informed business decisions, identify high-growth opportunities, optimize operational planning, anticipate evolving technology trends, and strengthen their competitive positioning in the global semiconductor and electronics market.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
