Metal Finishing Chemicals Market
Metal Finishing Chemicals Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711891 | Published On : November 20, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Metal Finishing Chemicals Market Size
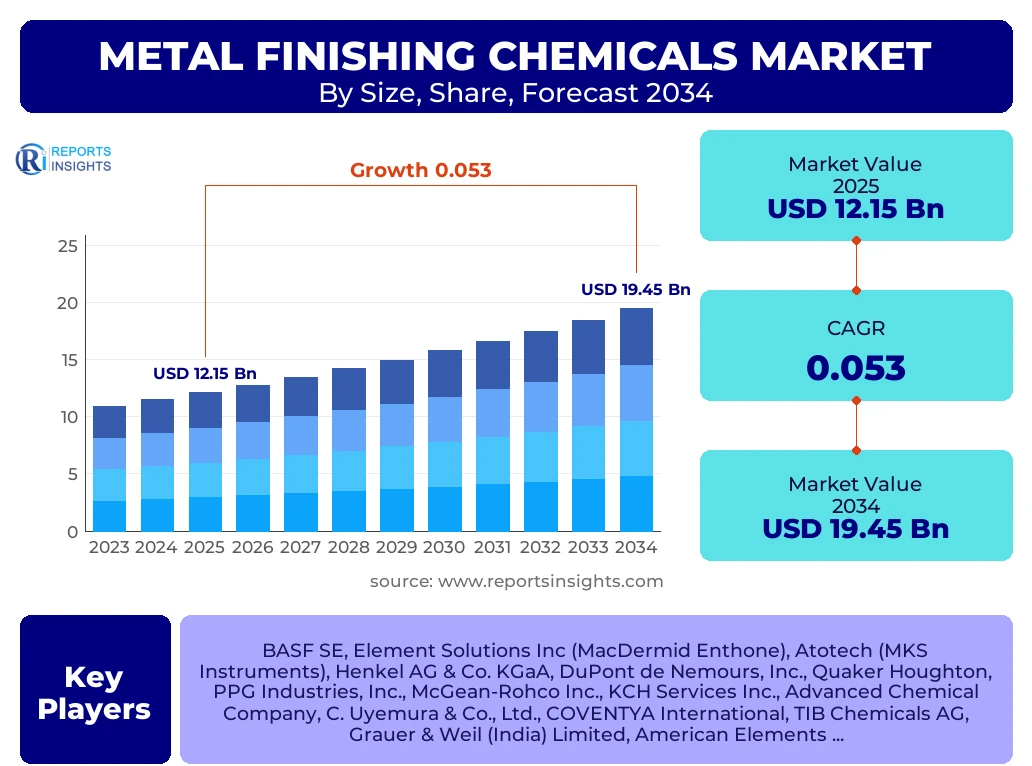
According to Reports Insights Consulting Pvt Ltd, The Metal Finishing Chemicals Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 5.3% between 2025 and 2034. The market is estimated at USD 12.8 Billion in 2026 and is projected to reach USD 19.45 Billion by the end of the forecast period in 2034.
The global metal finishing chemicals sector is undergoing a profound transformation driven by the escalating demand for durable, corrosion-resistant, and aesthetically superior metallic components across diverse industrial verticals. As manufacturing processes become increasingly sophisticated, the requirement for high-performance chemical formulations that enhance the surface properties of metals has become paramount. This market encompasses a wide array of processes, including electroplating, electroless plating, chemical conversion coatings, and industrial cleaning, all of which are essential for extending the lifecycle of metal parts used in automotive, aerospace, electronics, and industrial machinery applications.
The valuation reflects a robust recovery in global manufacturing activities post-disruption, coupled with a strategic shift toward high-value finishing solutions in emerging economies. The integration of advanced materials and the rapid expansion of the electric vehicle (EV) infrastructure are serving as primary catalysts for volume growth. Stakeholders are increasingly focusing on the development of proprietary chemical blends that offer superior adhesion and wear resistance while minimizing environmental impact, aligning with the broader industrial move toward sustainable production cycles.
Key Metal Finishing Chemicals Market Trends & Insights
The market is currently characterized by a decisive pivot toward green chemistry and the adoption of trivalent chromium processes over traditional hexavalent chromium due to stringent environmental mandates. Regional insights suggest that while North America and Europe remain hubs for high-end aerospace and medical finishing, the Asia-Pacific region is the powerhouse for high-volume automotive and electronics finishing. Competitive benchmarking indicates that market leaders are investing heavily in research and development to create multi-functional coatings that provide both decorative and functional benefits, such as anti-microbial properties and enhanced electrical conductivity.
- Asia-Pacific remains the largest and fastest-growing region, driven by massive industrialization in China, India, and Southeast Asia.
- The Automotive Industry is the largest end-user segment, accounting for a significant share of the total market value.
- Electroless Plating is emerging as a high-growth process segment due to its ability to provide uniform thickness on complex geometries.
- Sustainability and REACH Compliance are the dominant trends forcing chemical manufacturers to reformulate legacy products.
- Rise of 5G Technology is fueling demand for specialized finishing chemicals in the electronics sector to ensure signal integrity and heat dissipation.
Key Takeaways Metal Finishing Chemicals Market Size & Forecast
The forecast period from 2025 to 2034 highlights a steady upward trajectory for the metal finishing chemicals market, with a focus on value-added services and specialized formulations. Analysts note that the convergence of digital manufacturing (Industry 4.0) and surface treatment is allowing for more precise chemical application, reducing waste and improving consistency. The market size expansion is largely supported by the resurgence of the aerospace sector and the global push for infrastructure modernization, which requires long-lasting protective coatings for structural steel and equipment.
- Global CAGR of 5.3% indicates a resilient market that is successfully navigating regulatory challenges through innovation.
- China and India are identified as the primary growth engines, representing the highest concentration of finishing facilities globally.
- Electroplating remains the foundational technology, but conversion coatings are gaining ground in pre-treatment applications.
- The shift to Electric Vehicles is creating a new niche for specialized battery component coatings and connector finishes.
- Increased M&A activity among top-tier chemical providers is consolidating the market, leading to more integrated service offerings.
Metal Finishing Chemicals Market Drivers Analysis
The expansion of the metal finishing chemicals market is fundamentally anchored in the global manufacturing sector's requirement for enhanced material longevity and performance. As the cost of raw materials rises, industrial operators are seeking ways to extend the service life of existing assets, making high-quality finishing chemicals an essential investment. Furthermore, the aesthetic requirements of consumer electronics and luxury automotive segments continue to push the boundaries of what chemical finishing can achieve in terms of color, texture, and brilliance.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Rapid Expansion of the Electric Vehicle (EV) Sector | +1.4% | Global (Strongest in China, Germany) | 2025 - 2034 |
| Technological Advancements in Aerospace Manufacturing | +1.1% | United States, France | 2026 - 2032 |
| Demand for Miniaturized Electronic Components | +0.9% | South Korea, Taiwan, Japan | 2025 - 2034 |
| Infrastructure Growth in Emerging Economies | +0.8% | India, Southeast Asia, Brazil | 2025 - 2030 |
Metal Finishing Chemicals Market Restraints Analysis
While the market is growing, it faces significant headwinds from increasingly stringent environmental and safety regulations. Governments worldwide are tightening limits on heavy metal discharge and volatile organic compound (VOC) emissions, which increases the operational and compliance costs for finishing shops. Additionally, the fluctuating prices of metals such as nickel, copper, and zinc directly influence the cost structure of finishing chemicals, creating volatility in profit margins for manufacturers and end-users alike.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Environmental Regulations (REACH, EPA) | -0.7% | European Union, North America | 2025 - 2034 |
| Volatility in Raw Material Metal Prices | -0.5% | Global | 2025 - 2029 |
| High Wastewater Treatment Costs | -0.4% | Global | 2026 - 2034 |
Metal Finishing Chemicals Market Opportunities Analysis
The industry is seeing a surge in opportunities within the realm of nanotechnology and smart coatings. Developing chemicals that can provide self-healing properties or real-time corrosion monitoring represents a high-margin frontier for chemical manufacturers. Furthermore, the outsourcing of metal finishing services to specialized job shops in developing regions provides a fertile ground for chemical distributors to expand their footprints and offer localized technical support and customized chemical blending services.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Chrome-Free Finishing Solutions | +1.2% | Global (Focus on EU/US) | 2025 - 2034 |
| Growth in Medical Device Surface Treatment | +0.8% | United States, Germany, Ireland | 2027 - 2034 |
| Integration of AI in Chemical Process Control | +0.6% | Japan, South Korea | 2028 - 2034 |
Metal Finishing Chemicals Market Challenges Impact Analysis
The primary challenge remains the balance between high-performance output and ecological sustainability. As older finishing techniques are phased out, companies must invest heavily in new equipment and training to accommodate modern, eco-friendly chemical alternatives. Furthermore, supply chain disruptions affecting the availability of specialized chemical precursors can lead to production delays in critical sectors like defense and medical technology, necessitating more localized and resilient supply chain strategies.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Transition from Legacy Processes to Sustainable Alternatives | -0.6% | Global | 2025 - 2031 |
| Scarcity of Skilled Technical Personnel | -0.4% | North America, Europe | 2025 - 2034 |
| Geopolitical Trade Barriers and Tariffs | -0.3% | USA, China | 2025 - 2028 |
Metal Finishing Chemicals Market - Updated Report Scope
This report provides a granular analysis of the global metal finishing chemicals landscape, covering a wide spectrum of product types, processes, and end-user industries. It evaluates the impact of macroeconomic factors and regulatory shifts on market dynamics, offering a comprehensive forecast based on historical data and current industrial trends. The scope includes an in-depth look at the competitive environment, identifying key market participants and their strategic initiatives in the pursuit of market share and technological leadership.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 12.15 Billion |
| Market Forecast in 2034 | USD 19.45 Billion |
| Growth Rate | 5.3% CAGR |
| Number of Pages | 247 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | BASF SE, Element Solutions Inc (MacDermid Enthone), Atotech (MKS Instruments), Henkel AG & Co. KGaA, DuPont de Nemours, Inc., Quaker Houghton, PPG Industries, Inc., McGean-Rohco Inc., KCH Services Inc., Advanced Chemical Company, C. Uyemura & Co., Ltd., COVENTYA International, TIB Chemicals AG, Grauer & Weil (India) Limited, American Elements, Raschig GmbH, Chemetall (BASF), JCU Corporation, A Brite Company. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the metal finishing chemicals market reveals a diverse ecosystem where specific product functionalities cater to unique industrial requirements. The plating chemicals segment remains the dominant revenue generator, but post-treatment chemicals are seeing the fastest growth as industries focus on secondary protection and specialized surface properties. Cleaning chemicals also maintain a steady share, being indispensable for the success of all subsequent finishing steps.
- By Product Type: Cleaning Chemicals (Acidic, Alkaline, Solvent), Pre-treatment Chemicals (Degreasers, Etchants), Plating Chemicals (Nickel, Copper, Gold, Zinc, Chrome), Post-treatment Chemicals (Phosphating, Chromating, Passivation).
- By Process: Electroplating (Functional, Decorative), Electroless Plating, Chemical Conversion (Anodizing, Black Oxide), Electropolishing.
- By Material: Steel, Aluminum, Copper Alloys, Zinc Alloys, Precious Metals.
- By End-Use Industry: Automotive (Engine components, trims), Aerospace (Landing gear, turbine blades), Electronics (PCBs, connectors), Medical (Surgical instruments, implants).
Regional Highlights
- Asia-Pacific: The regional leader, holding over 40% of the market share. China is the single largest consumer of finishing chemicals globally, supported by its massive electronics and automotive manufacturing base. India is identified as the fastest-growing market due to increased government spending on infrastructure and domestic manufacturing initiatives.
- North America: Driven primarily by the aerospace and defense sectors. The region is a pioneer in adopting high-performance, environmentally compliant chemicals and is home to several major market players focused on innovation in the medical device finishing space.
- Europe: Characterized by a strong emphasis on regulatory compliance (REACH) and sustainable manufacturing. Germany and Italy are key hubs for automotive and machinery finishing, with a high demand for advanced conversion coatings.
- Latin America & MEA: Showing steady growth linked to mining activities and the expansion of the energy sector, particularly in Brazil and the GCC countries, where corrosion protection for oil and gas infrastructure is critical.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Metal Finishing Chemicals Market. These organizations are selected based on their market presence, product portfolio diversity, technological innovation, and strategic global footprint.
- BASF SE
- Element Solutions Inc (MacDermid Enthone)
- Atotech (MKS Instruments)
- Henkel AG & Co. KGaA
- DuPont de Nemours, Inc.
- Quaker Houghton
- PPG Industries, Inc.
- McGean-Rohco Inc.
- KCH Services Inc.
- Advanced Chemical Company
- C. Uyemura & Co., Ltd.
- COVENTYA International
- TIB Chemicals AG
- Grauer & Weil (India) Limited
- American Elements
- Raschig GmbH
- JCU Corporation
- A Brite Company
- Technic Inc.
- Columbia Chemical
Frequently Asked Questions
What is the projected market size of the Metal Finishing Chemicals Market by 2034?
The market is projected to reach approximately USD 19.45 Billion by 2034, growing at a steady CAGR of 5.3% from 2026 onwards, driven by industrial automation and the rise of the electric vehicle industry.
Which end-user industry holds the largest share in the metal finishing chemicals market?
The automotive industry currently holds the largest market share. This is due to the extensive use of finishing chemicals for both decorative purposes and functional protection against corrosion and wear in engine and body components.
How is environmental regulation affecting the chemical formulations in this market?
Regulations such as REACH in Europe and EPA guidelines in the US are forcing a shift away from hazardous substances like hexavalent chromium and certain solvents. This is leading to increased demand for trivalent chromium, water-based cleaners, and biodegradable chemical alternatives.
What is the difference between electroplating and electroless plating in terms of chemical demand?
Electroplating requires an external electric current and typically uses simpler chemical baths, while electroless plating relies on autocatalytic chemical reactions. Electroless plating chemicals are often more complex and expensive but are increasingly favored for coating intricate parts with uniform thickness.
Which region is expected to witness the fastest growth during the forecast period?
Asia-Pacific is expected to witness the fastest growth. Rapid industrialization, favorable government policies for manufacturing in India and Southeast Asia, and the massive consumer electronics market in China are the primary drivers for this regional expansion.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
