Pentamethylene Diisocyanate Market
Pentamethylene Diisocyanate Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711713 | Published On : November 13, 2026 |
Format : 


 | Author : Vidyuth Kothalgi
Pentamethylene Diisocyanate Market Size
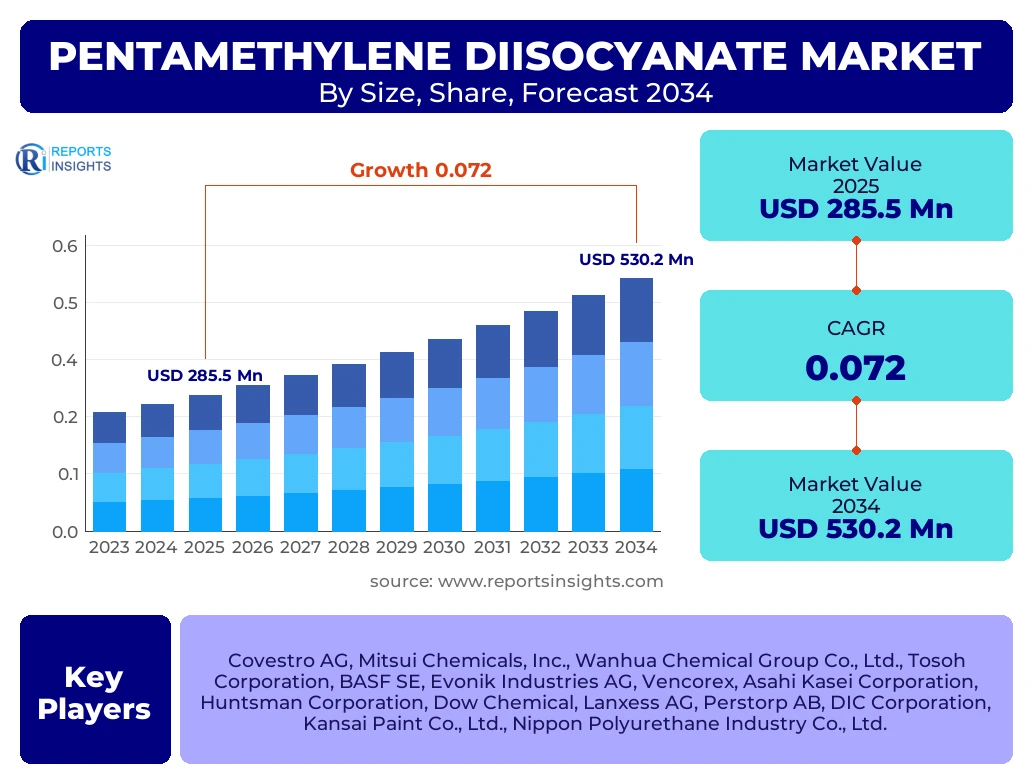
According to Reports Insights Consulting Pvt Ltd, The Pentamethylene Diisocyanate Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 7.2% between 2025 and 2034. The market is estimated at USD 306.05 Million in 2026 and is projected to reach USD 530.2 Million by the end of the forecast period in 2034.
Key Pentamethylene Diisocyanate Market Trends & Insights
The global Pentamethylene Diisocyanate (PDI) market is undergoing a structural shift driven by the transition toward bio-based chemistry and circular economy principles. As a sustainable alternative to fossil-fuel-based aliphatic diisocyanates like Hexamethylene Diisocyanate (HDI), PDI offers a significantly reduced carbon footprint without compromising mechanical performance. Market participants are increasingly focusing on vertical integration, securing renewable feedstocks such as biomass-derived starch or glucose to produce cadaverine, the primary precursor for PDI. This shift is particularly pronounced in the high-end coatings and adhesives sectors where environmental certifications and ESG (Environmental, Social, and Governance) mandates are becoming industry standards.
Innovation in polymerization techniques has led to the development of PDI-based polyisocyanates that exhibit lower viscosity and faster curing times compared to traditional counterparts. These technical advantages are accelerating adoption in the automotive refinish and industrial wood coating industries. Furthermore, the market is seeing a surge in strategic collaborations between chemical manufacturers and end-users in the consumer electronics and footwear sectors, aiming to create entirely bio-based polyurethane systems. This trend is bolstered by consumer demand for eco-friendly products and stringent VOC (Volatile Organic Compound) regulations across major manufacturing hubs.
- Largest Region: Europe remains the largest regional market due to early adoption of bio-based regulations and strong presence of automotive and premium furniture manufacturers.
- Fastest Growing Region: Asia Pacific is the fastest-growing region, fueled by massive industrial expansion in China and India and increasing investments in green chemical infrastructure.
- Largest Segment by Application: The Coatings segment holds the largest market share, specifically high-performance polyurethane coatings used in automotive and aerospace sectors.
- Emerging Trend: Rapid adoption of bio-based elastomers in the footwear industry to meet sustainability targets set by global athletic brands.
Key Takeaways Pentamethylene Diisocyanate Market Size & Forecast
The Pentamethylene Diisocyanate market is positioned for robust growth as the global chemical industry moves toward decarbonization. The forecast period between 2026 and 2034 will likely be defined by the scaling of production capacities and the optimization of supply chains for bio-based raw materials. Analysts anticipate that the market will transition from a niche sustainable alternative to a mainstream industrial chemical, driven by parity in performance with traditional HDI and Isophorone Diisocyanate (IPDI) systems. The convergence of regulatory pressure and technological maturation is creating a high-entry-barrier environment where established players with proprietary bio-refinery processes hold a significant competitive edge.
- The global market value is expected to surpass USD 500 million by 2034, reflecting a consistent upward trajectory in volume consumption.
- Bio-based content in PDI often reaches up to 70 percent, making it a critical component for companies aiming for carbon neutrality.
- Germany, China, and the United States are identified as the leading countries in terms of both production capacity and consumption.
- The automotive industry is the primary driver for high-purity PDI, utilized in weather-resistant clearcoats and interior finishes.
- Strategic pricing and the narrowing gap between bio-based and synthetic diisocyanate costs are expected to boost adoption rates in the mid-term forecast.
Pentamethylene Diisocyanate Market Drivers Analysis
The primary catalysts for the Pentamethylene Diisocyanate market are rooted in the global shift toward renewable resources and the tightening of environmental regulations. Industries are seeking drop-in replacements for petroleum-derived chemicals that can provide identical or superior physical properties, such as UV resistance and chemical stability. The push for "Green Building" certifications and the electrification of the automotive sector are also playing pivotal roles in demand generation.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shift to Bio-based Polyurethane Systems | +2.1% | Global / Western Europe | Short to Medium Term |
| Stringent VOC Emission Regulations | +1.8% | China, USA, EU | Ongoing |
| Automotive Lightweighting & Premium Coatings | +1.5% | Japan, Germany, South Korea | Medium Term |
| Expansion of Green Construction Standards | +1.2% | North America, APAC | Long Term |
Pentamethylene Diisocyanate Market Restraints Analysis
Despite the positive growth outlook, the market faces challenges related to the complexity of bio-refinery processes and the current price premium over conventional isocyanates. The availability of high-quality biomass and the logistical hurdles associated with bio-derived precursors can lead to supply chain volatility, impacting the stability of market pricing.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Higher Production Costs vs. Fossil-based HDI | -1.3% | Global | Short Term |
| Limited Bio-precursor Supply Chain Maturity | -0.9% | Emerging Markets | Medium Term |
| Technical Barriers in Formulation Adjustments | -0.5% | Global | Short Term |
Pentamethylene Diisocyanate Market Opportunities Analysis
The emergence of the textile and footwear sectors as major consumers of bio-based elastomers presents a significant opportunity for PDI manufacturers. Additionally, the development of water-borne PDI systems for eco-friendly adhesives offers a pathway into the packaging and consumer goods markets where safety and environmental impact are scrutinized by end-users.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Footwear & Textile Bio-Elastomers | +1.7% | Southeast Asia, China | Medium to Long Term |
| Water-borne PDI Coatings Development | +1.4% | EU, North America | Short Term |
| Aerospace and Marine Protective Coatings | +0.8% | Global | Medium Term |
Pentamethylene Diisocyanate Market Challenges Impact Analysis
Ensuring consistent feedstock quality and navigating the fragmented regulatory landscape for bio-based claims remain critical challenges. Competition from other emerging green diisocyanates and the necessity for significant capital investment in dedicated PDI production lines also weigh on the rapid scaling of the market.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Regulatory Standardization for Bio-content | -0.7% | EU, North America | Medium Term |
| Infrastructure Investment Requirements | -1.1% | Global | Short Term |
Pentamethylene Diisocyanate Market - Updated Report Scope
The report provides a deep-dive analysis into the global Pentamethylene Diisocyanate landscape, covering production technologies, feedstock analysis, and detailed consumption patterns across various industrial verticals. It evaluates the impact of macroeconomic factors and regional environmental policies on market dynamics from 2020 through the forecast end-point of 2034.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 285.5 Million |
| Market Forecast in 2034 | USD 530.2 Million |
| Growth Rate | 7.2% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Covestro AG, Mitsui Chemicals, Inc., Wanhua Chemical Group Co., Ltd., Tosoh Corporation, BASF SE, Evonik Industries AG, Vencorex, Asahi Kasei Corporation, Huntsman Corporation, Dow Chemical, Lanxess AG, Perstorp AB, DIC Corporation, Kansai Paint Co., Ltd., Nippon Polyurethane Industry Co., Ltd. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The segmentation of the Pentamethylene Diisocyanate market reflects its diverse utility in high-performance materials. By categorizing the market by type, we distinguish between pure monomers and derivatives like isocyanurates, which are essential for high-quality cross-linking in coatings. Application-based segmentation highlights the dominance of the CASE (Coatings, Adhesives, Sealants, and Elastomers) sector, while end-use segmentation identifies the specific industries driving volume demand.
- By Type:
- PDI Monomer (1,5-Pentamethylene Diisocyanate)
- PDI Isocyanurate (Used for high-performance weather-resistant coatings)
- PDI Biuret and other Adducts
- By Application:
- Coatings (Automotive OEM, Refinish, Industrial Wood, Marine)
- Adhesives & Sealants (Flexible packaging, Automotive bonding)
- Elastomers (TPU for footwear, Industrial parts)
- Others (Synthetic leather, Textile finishes)
- By End-Use Industry:
- Automotive and Transportation (Lightweighting and high-gloss finishes)
- Building and Construction (Sustainable insulation and wood coatings)
- Textile and Footwear (Bio-based athletic gear)
- Electronics (Protective coatings for devices)
- General Industrial
Regional Highlights
The regional analysis showcases the geographical concentration of both manufacturing expertise and demand drivers. Europe currently leads the market, primarily due to the stringent REACH regulations and the presence of pioneers like Covestro. However, the center of gravity is shifting toward Asia, where chemical production capacities are expanding rapidly to serve the massive domestic automotive and electronics markets.
- Europe: The largest market share holder, driven by the European Green Deal and high demand for premium, sustainable automotive coatings in Germany and France.
- Asia Pacific: The fastest-growing region with a CAGR exceeding 8%. China is the primary engine of growth, investing heavily in bio-based chemical infrastructure.
- North America: Significant market for specialty coatings and adhesives, with a strong focus on high-tech applications in the aerospace and electronics sectors.
- Latin America and MEA: Emerging markets with growing interest in sustainable construction materials and automotive assembly hubs.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Pentamethylene Diisocyanate Market.- Covestro AG
- Mitsui Chemicals, Inc.
- Wanhua Chemical Group Co., Ltd.
- Tosoh Corporation
- BASF SE
- Evonik Industries AG
- Vencorex
- Asahi Kasei Corporation
- Huntsman Corporation
- Dow Chemical
- Lanxess AG
- Perstorp AB
- DIC Corporation
- Kansai Paint Co., Ltd.
- Nippon Polyurethane Industry Co., Ltd.
Frequently Asked Questions
What is Pentamethylene Diisocyanate (PDI) and how is it produced?
Pentamethylene Diisocyanate (PDI) is a bio-based aliphatic diisocyanate. It is typically produced by the phosgenation of 1,5-pentamethylenediamine (cadaverine), which is derived from the fermentation of renewable feedstocks like corn or sugarcane. This makes PDI a sustainable alternative to petroleum-based diisocyanates.
What are the main advantages of using PDI over HDI?
PDI offers a significantly lower carbon footprint, often reducing CO2 emissions by up to 50 percent compared to HDI. Technically, PDI-based polyisocyanates can provide lower viscosity, faster drying times, and excellent weatherability, making them ideal for high-performance coatings.
Which industry is the primary driver for the PDI market?
The automotive industry is the leading driver, utilizing PDI in high-quality clearcoats and interior finishes to meet both performance requirements and sustainability targets. The footwear industry is also a rapidly growing consumer for bio-based elastomers.
Is PDI compatible with existing polyurethane formulation equipment?
Yes, PDI is designed as a drop-in or near-drop-in replacement for traditional aliphatic diisocyanates. While some slight adjustments to catalysts and formulation ratios may be required to optimize curing, it is generally compatible with standard industrial processing equipment.
What is the expected growth rate of the PDI market through 2034?
The market is expected to grow at a CAGR of approximately 7.2% from 2025 to 2034, driven by the global transition to green chemistry and increasing regulatory pressure to reduce the environmental impact of chemical products.
Author
V
Vidyuth Kothalgi is a Senior Analyst Materials and Chemicals Market Research with over 6+ years of experience in the Materials and Chemicals Industry. His expertise encompasses market intelligence, demand forecasting, competitive benchmarking, pricing analysis, supply chain assessment, regulatory landscape evaluation, raw material trend analysis, and strategic market sizing across specialty and commodity chemicals. By transforming complex industry data into actionable insights, he helps organizations make strategic business decisions, uncover growth opportunities, optimize operational planning, navigate evolving market dynamics, and strengthen their competitive positioning in global materials and chemicals markets.
| Single User | |
|---|---|
| Multi User | |
| Corporate User |
Buy Now
Secure SSL Encrypted
