Managed Service Market
Managed Service Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_702824 | Published On : October 11, 2026 |
Format : 


 | Author : Vigneshwaran Mahadik
Managed Service Market Size
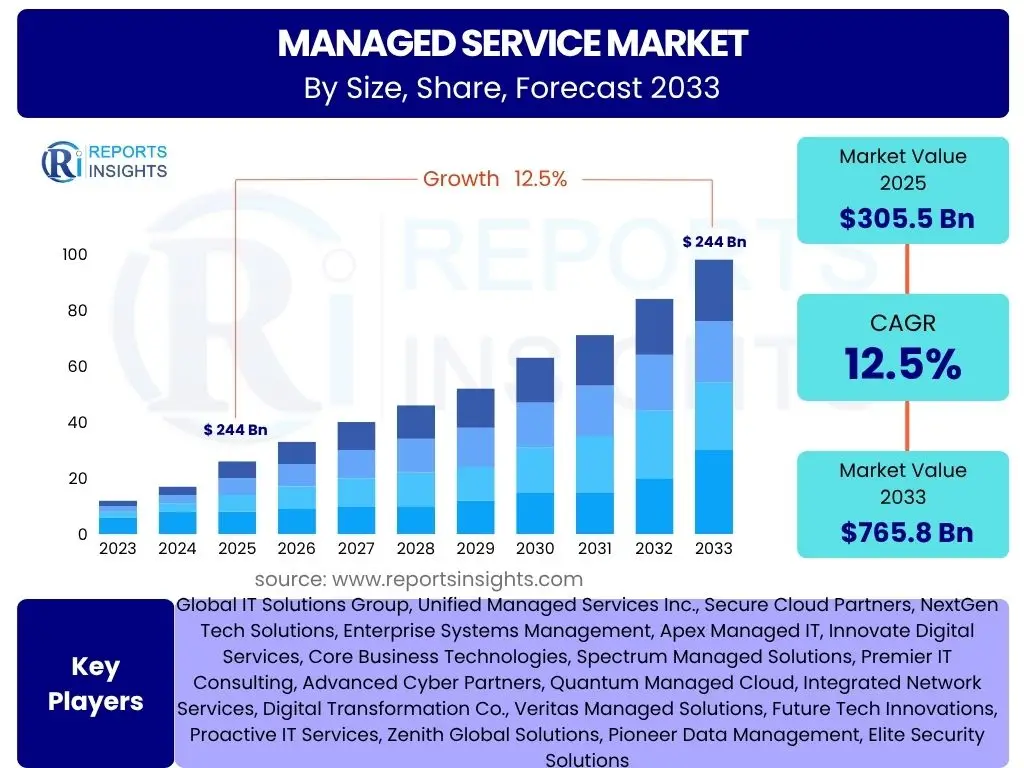
According to Reports Insights Consulting Pvt Ltd, The Managed Service Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 10.4% between 2025 and 2034. The market is estimated at USD 341.65 Billion in 2026 and is projected to reach USD 755.22 Billion by the end of the forecast period in 2034.
Key Managed Service Market Trends & Insights
The global Managed Service landscape is undergoing a radical transformation, driven by the convergence of artificial intelligence, cloud-native architectures, and a heightened focus on cybersecurity. Enterprises are increasingly shifting from traditional break-fix models to proactive, subscription-based Managed Service to achieve operational resilience. This shift is particularly evident in the rapid adoption of Artificial Intelligence for IT Operations (AIOps), which enables Managed Service Providers (MSPs) to automate routine maintenance and predict system failures before they occur. Additionally, the proliferation of hybrid and multi-cloud environments has created a demand for sophisticated orchestration services that bridge the gap between legacy infrastructure and modern digital platforms.
Regional dynamics indicate that North America continues to hold the largest market share due to early adoption of advanced technologies and a high density of Fortune 500 companies. However, the Asia-Pacific region is emerging as the fastest-growing market, fueled by massive digital transformation initiatives in India, China, and Southeast Asia. The rise of "Cybersecurity-as-a-Service" (SECaaS) is currently the most significant trend, as organizations struggle to keep pace with the evolving threat landscape and regulatory requirements like GDPR and NIS2. This has led to the emergence of specialized Managed Security Service Providers (MSSPs) who offer 24/7 Security Operations Center (SOC) capabilities.
- Largest Region: North America remains the dominant regional market, accounting for over 35% of global revenue.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR during the forecast period due to rapid industrialization and cloud migration.
- Largest Segment: Managed Infrastructure and Data Center services hold the largest share of the market by value.
- Leading Trend: The integration of Generative AI within service desks and automated ticketing systems is revolutionizing customer experience.
- Dominant Delivery Model: Cloud-based Managed Service are outpacing on-premise deployments as businesses prioritize scalability.
Key Takeaways Managed Service Market Size & Forecast
The Managed Service market is characterized by a strong trajectory of growth as businesses prioritize core competencies while outsourcing non-core IT functions. The forecast period (2026-2034) will see a significant emphasis on "Outcome-Based" service level agreements (SLAs) rather than simple "uptime-based" metrics. This evolution ensures that MSPs are directly aligned with the business goals of their clients, such as revenue growth and customer retention. The increasing complexity of regulatory compliance across different jurisdictions is also a primary catalyst for market expansion, as enterprises rely on MSPs for specialized legal and technical expertise.
- The market is expected to surpass the USD 500 billion mark by 2030, reflecting its critical role in the global economy.
- Managed Security Services (MSS) is the highest-growth sub-segment within the broader Managed Service portfolio.
- SMEs (Small and Medium Enterprises) represent a massive untapped opportunity, with a growing number of firms seeking affordable managed IT solutions.
- The United States and Germany are leading the way in adopting Managed IoT (Internet of Things) services for industrial automation.
- Consolidation through Mergers and Acquisitions (M&A) is expected to increase as larger firms seek to acquire specialized technical capabilities.
Managed Service Market Drivers Analysis
The primary drivers of the Managed Service market are rooted in the necessity for digital agility and cost efficiency. As organizations face a persistent shortage of skilled IT professionals, particularly in cybersecurity and cloud engineering, the Managed Service model provides immediate access to high-level expertise without the overhead of full-time hiring. Furthermore, the transition from Capital Expenditure (CapEx) to Operational Expenditure (OpEx) models allows businesses to maintain financial flexibility, which is critical in volatile economic environments.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shortage of Skilled IT Professionals | +2.8% | Global (High in North America & Europe) | 2025 - 2034 |
| Rapid Digital Transformation Initiatives | +3.1% | Asia-Pacific (India, China, Vietnam) | 2025 - 2030 |
| Increasing Need for Cybersecurity Resilience | +2.5% | United States, UK, Israel | 2025 - 2034 |
| Cost Optimization and OpEx Preference | +2.0% | Latin America and Africa | 2026 - 2034 |
Managed Service Market Restraints Analysis
Despite robust growth, the market faces significant hurdles, primarily concerning data privacy and the loss of internal control over critical infrastructure. Many enterprises remain hesitant to share sensitive intellectual property with third-party providers, especially in highly regulated sectors like defense and healthcare. Additionally, the complexity of integrating Managed Service with legacy on-premise systems can lead to implementation delays and unforeseen costs, acting as a deterrent for traditional manufacturing firms.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Data Security and Privacy Concerns | -1.2% | European Union (GDPR compliance) | 2025 - 2034 |
| Complexity of Legacy System Integration | -0.8% | Japan and Germany | 2025 - 2028 |
| High Initial Transition Costs | -0.5% | Emerging Markets | 2025 - 2030 |
Managed Service Market Opportunities Analysis
The next decade offers immense opportunities for MSPs who can specialize in niche vertical solutions. The rise of Edge Computing, driven by 5G technology, requires localized Managed Service that can handle data processing at the network's edge. Furthermore, the "Green IT" movement presents a chance for MSPs to offer energy-efficient data center management and sustainable infrastructure services, which are becoming a prerequisite for corporate sustainability reporting.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Edge Computing and 5G Managed Service | +1.9% | South Korea, USA, China | 2027 - 2034 |
| Sustainability and Green IT Solutions | +1.2% | Nordic Countries, Canada | 2026 - 2034 |
| SME Market Penetration via Automation | +1.5% | Global | 2025 - 2034 |
Managed Service Market Challenges Impact Analysis
Strategic challenges include the intensifying competition among global providers, which is leading to price erosion in commoditized services like basic help-desk support. Service providers must continuously innovate and move up the value chain to maintain margins. Moreover, the dynamic nature of global trade policies and data residency laws creates a fragmented landscape where a "one-size-fits-all" global service model is increasingly difficult to execute.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Intense Market Competition and Price Wars | -1.0% | Global | 2025 - 2030 |
| Evolving Regulatory and Data Residency Laws | -0.7% | India, Brazil, EU | 2025 - 2034 |
| Rapid Technological Obsolescence | -0.6% | High-Tech Hubs | 2026 - 2032 |
Managed Service Market - Updated Report Scope
This report provides a granular analysis of the global Managed Service market, covering diverse delivery models, organizational sizes, and vertical applications. It examines the strategic positioning of key market participants and assesses the impact of disruptive technologies on traditional service delivery. The scope encompasses detailed financial forecasting, competitive benchmarking, and regional deep dives to provide stakeholders with actionable intelligence for the 2025-2034 period.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 309.46 Billion |
| Market Forecast in 2034 | USD 755.22 Billion |
| Growth Rate | 10.4% CAGR |
| Number of Pages | 248 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | IBM Corporation, Accenture, Fujitsu Limited, DXC Technology, Tata Consultancy Services (TCS), Atos SE, Cisco Systems, Inc., HCL Technologies, Infosys Limited, Capgemini, NTT Data, Cognizant, Wipro Limited, Lumen Technologies, Rackspace Technology, Deloitte. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Managed Service market is segmented by service type, deployment mode, enterprise size, and industry vertical. Managed Infrastructure and Data Center services currently lead the market as organizations migrate to virtualized environments. Managed Security Services are the fastest-growing segment, driven by the escalating frequency of ransomware attacks and the complexity of hybrid work security. The SME segment is seeing rapid adoption of cloud-based Managed Service, which provide enterprise-grade capabilities without the need for significant capital investment.
- Managed Infrastructure: Monitoring and management of servers, storage, and virtualization layers.
- Managed Network Services: Includes SD-WAN management, VPNs, and network security.
- Managed Security Services (MSS): Vulnerability management, threat intelligence, and SOC-as-a-Service.
- Managed Communication and Collaboration: Unified Communications (UCaaS) and managed VoIP.
- Managed Information/Data: Database management and cloud storage optimization.
- Managed Mobility Services: Mobile device management (MDM) and application governance.
Regional Highlights
- North America: The largest market globally, characterized by high adoption of managed security and cloud-native services in the BFSI and Healthcare sectors.
- Europe: A significant market focusing on regulatory compliance (GDPR) and industrial IoT Managed Service, with Germany and the UK as primary hubs.
- Asia-Pacific: The fastest-growing region, where digital transformation in India and China is driving massive demand for managed IT infrastructure.
- Latin America: Emerging market with growing adoption in Brazil and Mexico, primarily focused on cost reduction and operational efficiency.
- Middle East & Africa: Rapidly evolving market with government-led smart city initiatives creating demand for managed network and security services.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Managed Service Market.- IBM Corporation
- Accenture
- Fujitsu Limited
- DXC Technology
- Tata Consultancy Services (TCS)
- Atos SE
- Cisco Systems, Inc.
- HCL Technologies
- Infosys Limited
- Capgemini
- NTT Data
- Cognizant
- Wipro Limited
- Lumen Technologies
- Rackspace Technology
- Deloitte
- Oracle Corporation
- Verizon Communications
Frequently Asked Questions
What is the projected size of the Managed Service Market by 2034?
The Managed Service Market is projected to reach approximately USD 755.22 Billion by 2034, growing at a CAGR of 10.4% from 2026 onwards.
Which region is expected to grow the fastest in the Managed Service Market?
Asia-Pacific is expected to be the fastest-growing region due to rapid digital transformation, increasing internet penetration, and significant investments in IT infrastructure across countries like India and China.
What are the primary drivers for the adoption of Managed Service?
The primary drivers include the need for cost optimization (shifting from CapEx to OpEx), the global shortage of specialized IT talent, and the rising complexity of cybersecurity threats.
What is the difference between an MSP and an MSSP?
An MSP (Managed Service Provider) focuses on general IT infrastructure and operations management, while an MSSP (Managed Security Service Provider) specializes exclusively in cybersecurity services, including monitoring and threat response.
Which vertical industry holds the largest share of the Managed Service market?
The BFSI (Banking, Financial Services, and Insurance) sector currently holds the largest share due to its stringent security requirements and the need for high-availability IT systems.
Author
V
Vigneshwaran Mahadik is a Senior Analyst IT and Telecommunications Research with over 6+ years of experience in the IT and Telecommunications Industry. He specializes in technology market intelligence, digital transformation analysis, cloud computing trends, telecom infrastructure assessment, competitive benchmarking, market sizing, demand forecasting, and emerging technology evaluation across enterprise and communication ecosystems. His research combines comprehensive industry analysis with data-driven methodologies to help organizations make strategic business decisions, identify new growth opportunities, optimize operational strategies, anticipate evolving market trends, and strengthen their competitive positioning in the global IT and telecommunications landscape.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
