Lentiviral Vector Contract Development Manufacturing Organizations Market
Lentiviral Vector Contract Development Manufacturing Organizations Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_711767 | Published On : November 16, 2026 |
Format : 


 | Author : Jonathan Sikka
Lentiviral Vector Contract Development Manufacturing Organizations Market Size
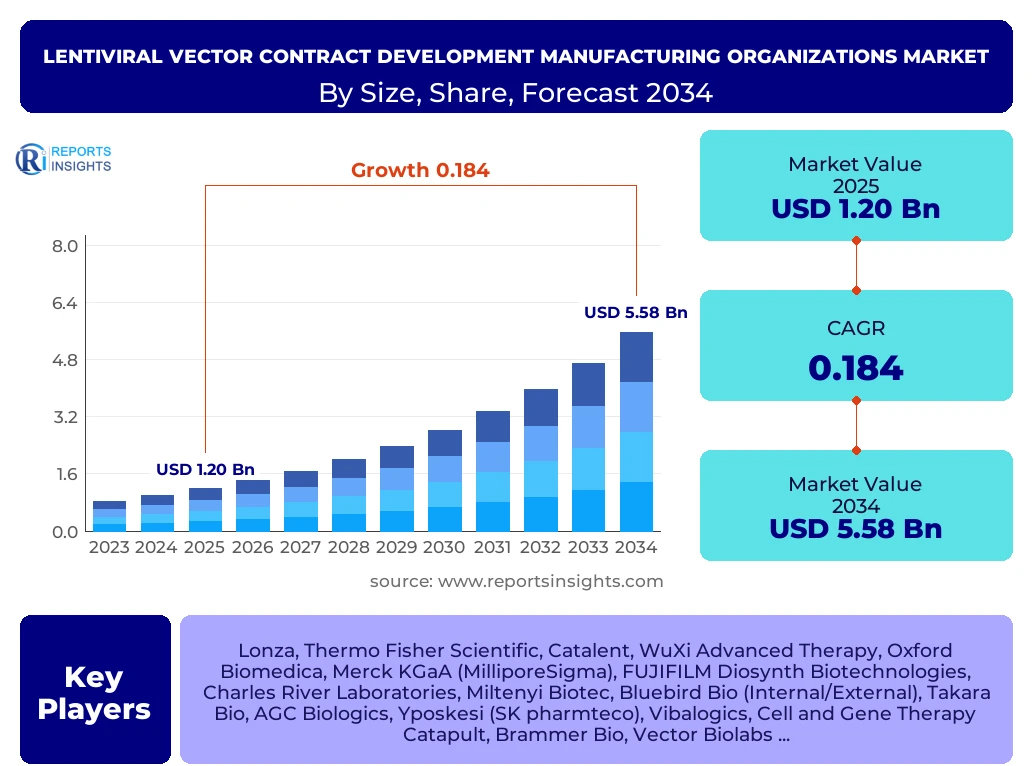
According to Reports Insights Consulting Pvt Ltd, The Lentiviral Vector Contract Development Manufacturing Organizations Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 18.4% between 2025 and 2034. The market is estimated at USD 1.42 Billion in 2026 and is projected to reach USD 5.58 Billion by the end of the forecast period in 2034.
The global landscape for Lentiviral Vector (LVV) contract manufacturing is undergoing a paradigm shift driven by the unprecedented clinical success of Chimeric Antigen Receptor (CAR) T-cell therapies. As the biopharmaceutical industry moves from early-phase clinical trials toward large-scale commercialization, the demand for high-titer, high-purity lentiviral vectors has surpassed existing in-house manufacturing capacities. This supply-demand imbalance has positioned Contract Development and Manufacturing Organizations (CDMOs) as indispensable partners in the cell and gene therapy (CGT) ecosystem. These organizations provide specialized expertise in viral vector engineering, regulatory compliance, and complex fill-finish operations that are otherwise prohibitively expensive for mid-sized biotech firms to develop independently.
Furthermore, technological advancements in manufacturing processes, such as the transition from adherent culture systems to large-scale suspension bioreactors, are significantly enhancing yield and reducing the cost per dose. The market is also benefiting from the geographical expansion of clinical trials into emerging economies and the diversification of lentiviral applications beyond oncology into rare genetic disorders and chronic infectious diseases. Strategic investments by private equity firms and heavy CAPEX expenditures by tier-one CDMOs to build "Center of Excellence" facilities are expected to sustain the double-digit growth trajectory through 2034.
Key Lentiviral Vector Contract Development Manufacturing Organizations Market Trends & Insights
The LVV CDMO market is characterized by a rapid evolution toward automation and standardized manufacturing platforms to mitigate risks of contamination and human error. Current market inquiries frequently center on the feasibility of stable producer cell lines versus traditional transient transfection methods. Regional insights suggest that while North America maintains a dominant position due to its mature biotech infrastructure, the Asia-Pacific region is emerging as a high-growth hub, driven by favorable regulatory reforms in China and the increasing number of CAR-T startups in India and South Korea. Competitive benchmarking reveals that leading players are differentiating themselves through "end-to-end" service offerings, encompassing everything from plasmid DNA production to analytical testing and cold-chain logistics.
- Largest Region: North America remains the primary revenue generator, accounting for over 45% of the global market share, supported by a high concentration of cell therapy developers and FDA-approved products.
- Fastest Growing Region: Asia-Pacific is projected to exhibit the highest CAGR, exceeding 20%, due to lower operational costs and a surging volume of regenerative medicine research.
- Leading Segment by Workflow: Upstream processing, particularly vector production and purification, holds the largest share as it constitutes the most technically demanding phase of the LVV lifecycle.
- Leading Segment by Application: Oncology applications dominate the market, primarily driven by the expansion of CAR-T pipelines for liquid and solid tumors.
- Emerging Technology Trend: The adoption of automated closed-system manufacturing is becoming a standard requirement for CDMOs to ensure scalability and regulatory alignment with cGMP standards.
Key Takeaways Lentiviral Vector Contract Development Manufacturing Organizations Market Size & Forecast
Market stakeholders are increasingly focused on the vertical integration of services and the reduction of lead times for vector production. The forecast indicates that the shift toward commercial-scale manufacturing will necessitate significant improvements in downstream processing efficiency to handle higher volumes without compromising vector potency. Investors and pharmaceutical companies are prioritizing CDMOs that possess integrated analytical capabilities to ensure rapid characterization of viral titers and impurity profiles, which is critical for meeting stringent regulatory timelines.
- The global market value is set to quadruple by 2034, reflecting the transition of numerous gene therapy candidates from Phase II/III to commercial approval.
- The United States and Germany are the most critical country-level markets for LVV manufacturing services due to their robust intellectual property frameworks.
- Process development services are seeing a surge in demand as developers look to optimize transient transfection protocols to maximize yield.
- Shortage of specialized cleanroom space and skilled workforce remains a temporary bottleneck, driving premium pricing for established CDMOs.
- Strategic partnerships and M&A activities are expected to consolidate the market, with larger life sciences companies acquiring boutique CDMOs to gain niche vector expertise.
Lentiviral Vector Contract Development Manufacturing Organizations Market Drivers Analysis
The primary driver for the LVV CDMO market is the exponential increase in the global pipeline of cell and gene therapies requiring lentiviral delivery systems. Lentiviral vectors are preferred for their ability to integrate large genetic payloads into the host genome of both dividing and non-dividing cells, making them the gold standard for CAR-T cell engineering. Additionally, the increasing burden of cancer and genetic diseases globally is compelling governments to fast-track approvals for advanced therapy medicinal products (ATMPs). The trend of "outsourcing over in-housing" is also a significant driver, as biotech companies seek to leverage the specialized infrastructure and "ready-to-use" regulatory documentation provided by experienced CDMOs to accelerate time-to-market.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Expanding CAR-T Clinical Pipeline | +6.5% | Global (Strongest in US/China) | 2025 - 2034 |
| Shift to Suspension-Based Manufacturing | +4.2% | Europe and North America | 2026 - 2030 |
| Outsourcing of Viral Vector Production | +3.8% | Global | 2025 - 2034 |
| Regulatory Designations (RMAT/Orphan Drug) | +2.5% | United States | 2025 - 2028 |
Lentiviral Vector Contract Development Manufacturing Organizations Market Restraints Analysis
The high cost associated with lentiviral vector production remains a significant barrier to market expansion. The complex nature of manufacturing, which involves multi-plasmid transfection, leads to high batch failure rates and expensive raw materials. Furthermore, the stringent regulatory landscape and the requirement for biosafety level 2 (BSL-2) or higher facilities impose significant operational hurdles. These factors can limit the participation of smaller biotech players and increase the overall cost of treatment for patients, potentially slowing down the adoption of therapies that rely on these vectors.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Cost of Raw Materials (Plasmids/Media) | -3.2% | Global | 2025 - 2034 |
| Complex Regulatory Compliance Protocols | -2.1% | EU (GDPR/EMA) and US (FDA) | 2025 - 2029 |
| Supply Chain Instability for Consumables | -1.5% | Asia-Pacific and Latin America | 2025 - 2027 |
Lentiviral Vector Contract Development Manufacturing Organizations Market Opportunities Analysis
There is a massive opportunity in the development of stable producer cell lines, which could replace the current inefficient transient transfection process and significantly lower production costs. Additionally, the expansion of lentiviral vectors into non-oncology indications, such as sickle cell disease, hemophilia, and various metabolic disorders, opens new revenue streams for CDMOs. The emerging trend of localized manufacturing in regions like the Middle East and Southeast Asia also presents a strategic opportunity for global CDMOs to establish regional hubs and cater to local clinical trial requirements.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Development of Stable Producer Cell Lines | +5.4% | Global | 2027 - 2034 |
| Expansion into Rare Disease Gene Therapies | +4.1% | Europe and North America | 2026 - 2034 |
| Emerging Market Expansion (APAC/MEA) | +3.3% | India, China, Brazil, UAE | 2028 - 2034 |
Lentiviral Vector Contract Development Manufacturing Organizations Market Challenges Impact Analysis
The primary technical challenge is achieving high titers and purity at scale, particularly during downstream purification where significant vector loss often occurs. Additionally, the shortage of specialized labor with expertise in viral vector bioprocessing is a major hurdle for CDMOs looking to expand their capacity rapidly. Intellectual property disputes regarding vector components and transfection reagents also pose a risk to operational stability and can lead to costly litigation or licensing fees.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Scalability of Downstream Purification | -2.8% | Global | 2025 - 2030 |
| Shortage of Skilled Bioprocessing Talent | -2.4% | Global (Acute in US/UK) | 2025 - 2034 |
| IP Litigation and Licensing Bottlenecks | -1.8% | North America and Europe | 2025 - 2028 |
Lentiviral Vector Contract Development Manufacturing Organizations Market - Updated Report Scope
This report provides a granular analysis of the global Lentiviral Vector CDMO landscape, covering technical workflows, therapeutic applications, and end-user requirements across major geographies. It includes a comprehensive evaluation of the competitive landscape, assessing companies based on their manufacturing capacity, service diversity, and geographic footprint. The scope also extends to future technological trends, such as the use of AI in vector design and the implementation of single-use technologies in commercial-scale production.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 1.20 Billion |
| Market Forecast in 2034 | USD 5.58 Billion |
| Growth Rate | 18.4% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | Lonza, Thermo Fisher Scientific, Catalent, WuXi Advanced Therapy, Oxford Biomedica, Merck KGaA (MilliporeSigma), FUJIFILM Diosynth Biotechnologies, Charles River Laboratories, Miltenyi Biotec, Bluebird Bio (Internal/External), Takara Bio, AGC Biologics, Yposkesi (SK pharmteco), Vibalogics, Cell and Gene Therapy Catapult, Brammer Bio, Vector Biolabs, Creative Biogene, Eurofins Scientific. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Lentiviral Vector CDMO market is segmented based on workflow, application, and end-user to provide a detailed understanding of the value chain. The workflow segment is currently dominated by vector production, but the process development sub-segment is witnessing significant growth as companies look to optimize yields early in the development cycle. In terms of application, oncology remains the primary revenue generator due to the high volume of CAR-T research, although the gene therapy segment for monogenic disorders is catching up as clinical trials reach late stages. The end-user analysis shows that while large pharmaceutical companies provide steady, high-volume contracts, emerging biotech firms are the primary drivers of innovation and early-phase clinical manufacturing demand.
- By Workflow:
- Process Development (Optimization of viral titers and transfection)
- Vector Production (Upstream manufacturing in adherent or suspension systems)
- Purification (Downstream processing and removal of impurities)
- Fill-Finish Services (Aseptic packaging and labeling)
- Analytical Testing & Quality Control (Characterization, safety testing, and potency assays)
- By Application:
- Cell Therapy (Focus on CAR-T, TCR-T, and TIL therapies)
- Gene Therapy (In-vivo and Ex-vivo applications for genetic disorders)
- Vaccine Development (Use of lentiviral vectors in recombinant vaccine platforms)
- By End-User:
- Biopharmaceutical Companies (Large-scale commercial players)
- Biotechnology Startups (Early-stage clinical trial sponsors)
- Academic & Research Organizations (Foundational research and Phase I trials)
Regional Highlights
- North America: The largest market globally, characterized by a sophisticated clinical trial infrastructure and the highest number of FDA-approved cell therapies. The United States leads in terms of both demand for LVV and the concentration of high-capacity CDMO facilities.
- Europe: A strong secondary market with a focus on advanced manufacturing technologies. Germany, the UK, and France are hubs for gene therapy research, supported by favorable EMA regulations and a robust network of academic medical centers.
- Asia-Pacific: The fastest-growing region, with China emerging as a global powerhouse for CAR-T clinical trials. India and South Korea are also investing heavily in CGT manufacturing capabilities to attract international biotech partners seeking cost-effective production.
- Latin America: An emerging market where growth is driven by the increasing presence of multinational pharmaceutical companies and the establishment of local clinical trial sites in Brazil and Mexico.
- Middle East & Africa: A niche but developing market, where countries like the UAE and Israel are investing in precision medicine and biotechnology infrastructure, creating localized demand for viral vector manufacturing.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Lentiviral Vector Contract Development Manufacturing Organizations Market.- Lonza Group AG
- Thermo Fisher Scientific Inc.
- Catalent, Inc.
- WuXi Advanced Therapy (WuXi AppTec)
- Oxford Biomedica plc
- Merck KGaA (MilliporeSigma)
- FUJIFILM Diosynth Biotechnologies
- Charles River Laboratories International, Inc.
- Miltenyi Biotec B.V. & Co. KG
- Takara Bio Inc.
- AGC Biologics
- Yposkesi (Part of SK pharmteco)
- Vibalogics (Part of Recipharm)
- Cell and Gene Therapy Catapult
- Brammer Bio (Acquired by Thermo Fisher)
- Vector Biolabs
- Creative Biogene
- Eurofins Scientific
- GenScript ProBio
- Sartorius AG
Frequently Asked Questions
What is the current market size of the Lentiviral Vector CDMO market?
The market is estimated to be worth approximately USD 1.20 Billion in 2025 and is projected to grow to over USD 5.58 Billion by 2034, driven by the surge in CAR-T cell therapy approvals.
Why are lentiviral vectors preferred for CAR-T cell therapy?
Lentiviral vectors are preferred because of their ability to permanently integrate large genetic sequences into the host genome, high transduction efficiency in T-cells, and low immunogenicity compared to other viral vectors.
Which region is expected to grow the fastest in LVV manufacturing?
The Asia-Pacific region is expected to be the fastest-growing market due to an increasing number of clinical trials in China and favorable government initiatives for biotechnology manufacturing.
What are the biggest challenges in scaling up lentiviral vector production?
Key challenges include low yields during downstream purification, high costs of plasmid DNA, and the technical difficulty of transitioning from adherent to large-scale suspension culture systems.
How does the shift to stable producer cell lines impact the market?
The shift to stable producer cell lines is expected to significantly reduce manufacturing costs and batch-to-batch variability, making lentiviral vector therapies more affordable and scalable for global markets.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
