Variable Frequency Drive Market
Variable Frequency Drive Market Size, Scope, Growth, Trends and By Segmentation Types, Applications, Regional Analysis and Industry Forecast (2026-2034)
Report ID : RI_704455 | Published On : September 11, 2026 |
Format : 


 | Author : Jonathan Sikka
Variable Frequency Drive Market Size
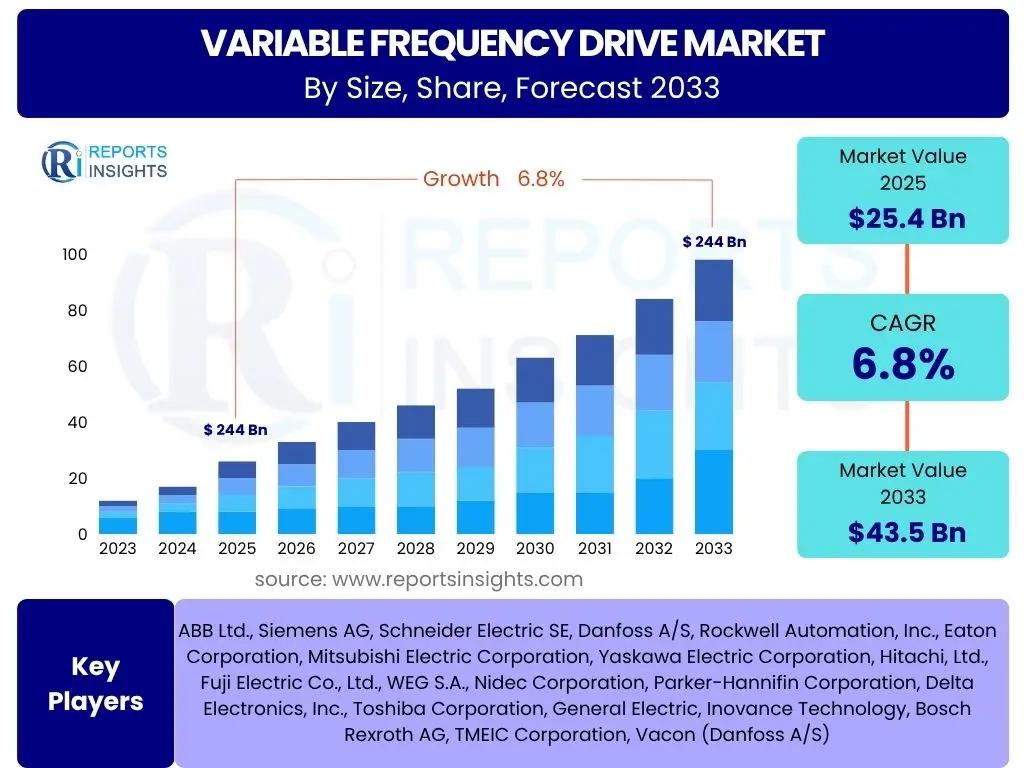
According to Reports Insights Consulting Pvt Ltd, The Variable Frequency Drive Market is projected to grow at a Compound Annual Growth Rate (CAGR) of 6.1% between 2026 and 2034. The market is estimated at USD 27.05 Billion in 2026 and is projected to reach USD 43.48 Billion by the end of the forecast period in 2034.
Key Variable Frequency Drive Market Trends & Insights
The Variable Frequency Drive (VFD) market is undergoing a significant transformation driven by the global imperative for energy efficiency and the rapid integration of industrial automation. Modern industries are increasingly adopting VFDs to optimize motor speed control, which directly translates to substantial energy savings, particularly in centrifugal pump and fan applications where power consumption is proportional to the cube of the speed. Furthermore, the advent of Industry 4.0 has introduced smart VFDs equipped with advanced sensors and communication protocols such as PROFINET and EtherNet/IP. These intelligent drives facilitate real-time monitoring and predictive maintenance, allowing operators to detect potential failures before they occur, thereby reducing downtime and operational costs in heavy industrial environments.
Regional dynamics play a crucial role in shaping the market landscape, with the Asia-Pacific region emerging as the primary hub for manufacturing and infrastructure development. The proliferation of smart city initiatives and the expansion of the water and wastewater treatment sector in emerging economies like India and China are providing a robust tailwind for VFD adoption. Additionally, stringent government regulations regarding carbon emissions and industrial energy audits in the European Union and North America are forcing legacy facilities to retrofit their existing motor systems with high-efficiency drives. The shift toward modular and compact VFD designs is also gaining traction, enabling easier integration into space-constrained control cabinets and machine architectures across various sectors including food and beverage and automotive manufacturing.
- Largest Region: Asia-Pacific remains the dominant market shareholder due to rapid industrialization and massive investments in power generation and infrastructure projects.
- Fastest Growing Region: South East Asia and parts of Africa are expected to witness the highest CAGR, spurred by localized manufacturing incentives and energy access programs.
- Largest Segment by Type: AC Drives continue to hold the largest market share, valued for their versatility, lower maintenance requirements, and compatibility with standard induction motors.
- Leading End-Use Industry: The Oil & Gas and Water & Wastewater sectors are the primary contributors to revenue, driven by the critical need for flow control and pressure management.
- Technological Shift: There is a notable transition from simple scalar control to high-performance vector control and direct torque control (DTC) for precision applications.
Key Takeaways Variable Frequency Drive Market Size & Forecast
The long-term outlook for the Variable Frequency Drive market remains highly positive, as global energy prices fluctuate and industries seek long-term cost stabilization through efficiency. Market forecasts indicate a steady upward trajectory, supported by the replacement of aging industrial infrastructure in developed nations and the greenfield investments in the developing world. Analysts observe that the convergence of power electronics and digital twins is creating new value propositions for VFD manufacturers, who are now offering software-as-a-service (SaaS) models for energy optimization. This strategic shift from hardware-centric sales to integrated solution providing is expected to redefine competitive benchmarking in the coming decade.
- Global Energy Mandates: Regulatory frameworks like the EU Ecodesign Directive are mandatory catalysts for high-efficiency motor-drive combinations.
- Urbanization Trends: Increasing demand for HVAC systems in commercial and residential high-rise buildings is a major driver for low-voltage VFD sales.
- Decarbonization Goals: Corporate ESG commitments are accelerating the phase-out of inefficient across-the-line starters in favor of VFDs.
- Cost Reduction: The declining cost of power electronic components like IGBTs (Insulated-Gate Bipolar Transistors) is making VFDs more accessible for small-scale enterprises.
- Supply Chain Resilience: Leading players are diversifying their semiconductor sourcing to mitigate risks associated with global electronic component shortages.
Variable Frequency Drive Market Drivers Analysis
The primary driver for the Variable Frequency Drive market is the urgent global requirement for enhanced energy efficiency in industrial processes. As electric motors account for approximately 40% of global electricity consumption, even minor improvements in motor control efficiency can lead to massive reductions in total energy demand and greenhouse gas emissions. Governments are incentivizing the adoption of VFDs through subsidies and tax breaks, recognizing them as a "low-hanging fruit" for achieving climate targets. Additionally, the industrial automation surge, characterized by the need for precise process control in pharmaceutical and food processing plants, necessitates the fine-tuned frequency regulation that only VFDs can provide.
| Drivers | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Stringent Energy Efficiency Regulations | +1.8% | Europe (EU-27) & North America | 2025 - 2034 |
| Expansion of Water & Wastewater Infrastructure | +1.5% | India, China, & Brazil | 2026 - 2032 |
| Adoption of Industry 4.0 and Smart Manufacturing | +1.2% | Germany, Japan, & USA | 2025 - 2030 |
| Rising HVAC Demand in Commercial Construction | +0.9% | Middle East (GCC Countries) | 2027 - 2034 |
Variable Frequency Drive Market Restraints Analysis
Despite the clear benefits, the high initial capital expenditure required for purchasing and installing high-performance VFDs remains a significant barrier for many Small and Medium Enterprises (SMEs). Beyond the purchase price, the complexity of integrating these drives into existing legacy systems often requires specialized engineering expertise, which adds to the total cost of ownership. Furthermore, VFDs can introduce harmonic distortion into the power grid, necessitating additional investments in harmonic filters or active front-end technology to comply with utility standards, which can deter potential users who are sensitive to budget constraints.
| Restraints | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| High Initial Investment & Installation Costs | -0.8% | Global / Emerging Markets | 2025 - 2034 |
| Harmonic Distortion & Electrical Interference | -0.5% | Industrial Zones with Weak Grids | 2025 - 2029 |
Variable Frequency Drive Market Opportunities Analysis
The transition toward renewable energy sources presents a massive opportunity for VFD manufacturers, particularly in wind and solar power generation where converters and drives are essential for managing variable outputs. As the world pivots toward green hydrogen production, the electrolysis process will require sophisticated power electronics and motor control systems, opening a multi-billion dollar niche market. Furthermore, the retrofitting market for older industrial plants in the United States and Western Europe provides a consistent stream of revenue, as these facilities look to upgrade to smart, connected drives to remain competitive and compliant with new environmental standards.
| Opportunities | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Integration with Renewable Energy Storage | +2.1% | Global / OECD Countries | 2028 - 2034 |
| Development of GaN & SiC Based Power Electronics | +1.4% | Technologically Advanced Markets | 2026 - 2034 |
| Expansion into Green Hydrogen Infrastructure | +1.1% | European Union & Australia | 2030 - 2034 |
Variable Frequency Drive Market Challenges Impact Analysis
One of the most pressing challenges facing the market is the acute shortage of skilled technicians capable of configuring, maintaining, and troubleshooting advanced drive systems. As VFDs become more software-defined, the overlap between traditional electrical engineering and IT/data science is growing, leaving a talent gap in the workforce. Additionally, the industry is vulnerable to supply chain disruptions affecting semiconductors and rare earth materials, which are vital for the production of high-efficiency permanent magnet motors often paired with VFDs. Rapidly changing technical standards across different jurisdictions also pose a challenge for manufacturers aiming for global product standardization.
| Challenges | (~) Impact on CAGR % Forecast | Regional/Country Relevance | Impact Time Period |
|---|---|---|---|
| Shortage of Specialized Technical Talent | -0.7% | North America & Europe | 2025 - 2034 |
| Raw Material & Semiconductor Price Volatility | -0.9% | Global Manufacturing Hubs | 2025 - 2027 |
Variable Frequency Drive Market - Updated Report Scope
This report provides a comprehensive analysis of the global Variable Frequency Drive market, covering technical specifications, end-user demand patterns, and regional economic influences. The scope extends from low-voltage micro-drives used in simple machine tools to high-power medium-voltage drives utilized in heavy mining and marine propulsion. It analyzes the entire value chain, from raw material suppliers of silicon wafers and copper windings to the end-users in critical infrastructure and manufacturing. The research incorporates a deep dive into the regulatory landscape and the technological evolution from traditional 2-level inverters to advanced multi-level topologies designed for reduced harmonic output and improved motor longevity.
| Report Attributes | Report Details |
|---|---|
| Base Year | 2025 |
| Historical Year | 2020 to 2024 |
| Forecast Year | 2026 - 2034 |
| Market Size in 2025 | USD 25.50 Billion |
| Market Forecast in 2034 | USD 43.48 Billion |
| Growth Rate | 6.1% CAGR |
| Number of Pages | 245 |
| Key Trends |
|
| Segments Covered |
|
| Key Companies Covered | ABB Ltd, Siemens AG, Schneider Electric SE, Danfoss A/S, Rockwell Automation, Inc., Mitsubishi Electric Corporation, Yaskawa Electric Corporation, Eaton Corporation, Weg S.A., Fuji Electric Co., Ltd., Hitachi, Ltd., Nidec Corporation, Toshiba Mitsubishi-Electric Industrial Systems Corp (TMEIC), Delta Electronics, Inc., Emerson Electric Co., General Electric, Honeywell International Inc., Parker Hannifin Corp, Inovance Technology, Sew-Eurodrive. |
| Regions Covered | North America, Europe, Asia Pacific (APAC), Latin America, Middle East, and Africa (MEA) |
| Speak to Analyst | Avail customised purchase options to meet your exact research needs. Request For Analyst Or Customization |
Segmentation Analysis
The Variable Frequency Drive market is segmented based on product type, voltage level, power rating, and end-user application to provide a granular view of market dynamics. AC drives represent the largest segment due to their widespread use with induction motors, which are the workhorses of modern industry. The segment for medium-voltage drives is seeing rapid growth in heavy-duty applications like mining and power generation where high torque and efficiency are non-negotiable. Furthermore, the segmentation by application reveals that pumps and fans account for the majority of the market share, as these centrifugal loads benefit most from the affinity laws of fluid dynamics when controlled by VFDs.
- By Product Type: AC Drives, DC Drives, and Servo Drives.
- By Voltage Class: Low Voltage and Medium Voltage.
- By Power Rating: Range-based categories from micro-drives (< 5kW) to high-power utility-scale drives (> 200kW).
- By Application: Detailed analysis of Pumps, Fans, Conveyors, Compressors, and Specialized Industrial Machinery.
- By End-User Industry: Vertical-specific insights for Oil & Gas, Water/Wastewater, Food & Beverage, Mining, and HVAC.
Regional Highlights
- Asia-Pacific: The region holds the largest market share, with China and India leading in industrial expansion and infrastructure upgrades. It is the global manufacturing hub for electronics and automotive sectors.
- North America: A mature market focused on replacement and high-tech retrofitting. The United States is a leader in adopting IoT-integrated drives for smart building and oil field automation.
- Europe: Driven by the world’s strictest energy efficiency standards. Germany and the UK are primary markets for high-efficiency VFDs in the manufacturing and renewable sectors.
- Middle East & Africa: Significant growth in the desalination and oil extraction industries, where large-scale medium-voltage drives are essential for operation.
- Latin America: Brazil and Chile are key markets, primarily driven by the mining sector and investments in water management systems.

Top Key Players
The market research report includes a detailed profile of leading top wise companies in the Variable Frequency Drive Market.- ABB Ltd
- Siemens AG
- Schneider Electric SE
- Danfoss A/S
- Rockwell Automation, Inc.
- Mitsubishi Electric Corporation
- Yaskawa Electric Corporation
- Eaton Corporation
- Weg S.A.
- Fuji Electric Co., Ltd.
- Hitachi, Ltd.
- Nidec Corporation
- Toshiba Mitsubishi-Electric Industrial Systems Corp (TMEIC)
- Delta Electronics, Inc.
- Emerson Electric Co.
- General Electric
- Inovance Technology
- Sew-Eurodrive
- Parker Hannifin Corp
- Honeywell International Inc.
Frequently Asked Questions
What is the primary benefit of using a Variable Frequency Drive in industrial applications?
The primary benefit of a VFD is energy savings. By controlling the speed of a motor to match the actual demand of the process, VFDs can reduce energy consumption by up to 50% in certain applications like pumps and fans. They also reduce mechanical stress and extend the lifespan of equipment.
Which industries are the largest adopters of VFD technology?
The Oil & Gas, Water & Wastewater treatment, and HVAC sectors are the largest adopters. These industries rely heavily on fluid and air movement, where VFDs provide the most significant operational efficiency and cost reductions.
How is Industry 4.0 impacting the Variable Frequency Drive market?
Industry 4.0 is driving the adoption of "Smart Drives" that feature integrated sensors and connectivity. This allows for real-time data collection, remote monitoring, and predictive maintenance, significantly reducing unplanned downtime and improving overall equipment effectiveness (OEE).
What are the main differences between Low Voltage and Medium Voltage VFDs?
Low Voltage VFDs (up to 690V) are typically used in commercial buildings and light manufacturing. Medium Voltage VFDs (above 690V) are designed for heavy industrial applications such as large-scale water pumps, mining conveyors, and power plant fans where high power density is required.
What are the key challenges in implementing VFDs in older facilities?
Key challenges include the high cost of retrofitting, potential harmonic interference with older electrical grids, and the need for upgraded motor insulation to handle the high-frequency voltage spikes produced by VFD switching.
Author
J
Manufacturing and Construction
Jonathan Sikka is a Manufacturing and Construction Research Industry with 5+ years of experience in the Manufacturing and Construction Industry. He specializes in market intelligence, construction materials analysis, industrial manufacturing trends, demand forecasting, competitive benchmarking, infrastructure market assessment, supply chain evaluation, capital investment analysis, and market sizing across commercial, residential, and industrial sectors. His analytical expertise transforms complex industry data into actionable insights that help organizations make strategic business decisions, identify emerging growth opportunities, optimize operational performance, understand evolving market trends, and strengthen their competitive positioning in global manufacturing and construction markets.
| Single User | : $3680 |
|---|---|
| Multi User | : $5680 |
| Corporate User | : $6400 |
Buy Now
Secure SSL Encrypted
